Sustainable Energy
How a Middle East Conflict Is Reshaping the Global Coal Market
Global coal demand is forecast to rise 1.2% to a record 8.94 billion tonnes in 2026, with higher gas prices linked to the Middle East conflict encouraging coal use in parts of Asia and Europe. The IEA expects demand to ease in 2027 if LNG supplies recover.

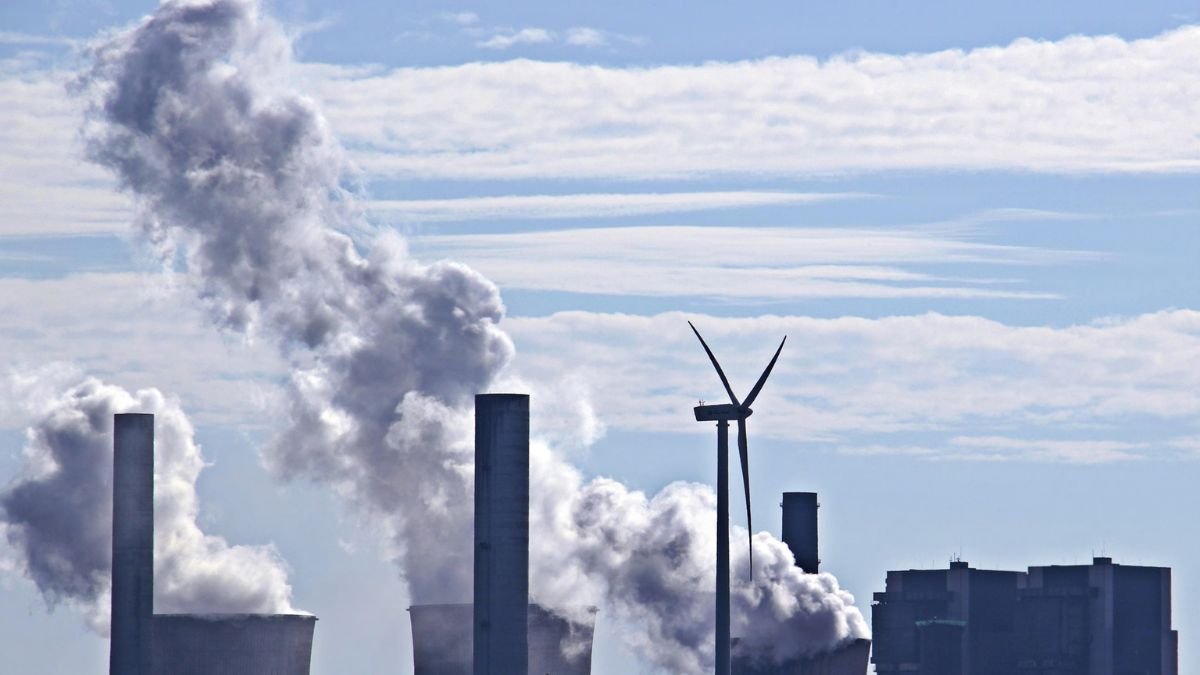
The Strait of Hormuz carries very little coal. Yet disruption there has become one of the forces shaping the international coal market in 2026. The reason is natural gas. Falling LNG shipments through the Strait pushed gas prices higher after the conflict in the Middle East intensified. In countries that have both gas-fired power plants and coal capacity available, the economics began to favour coal. Japan and South Korea, both heavily dependent on imported energy, increased their demand for traded coal. Higher gas prices also affected power markets in Europe and China.
A geopolitical crisis far from the world’s main coal mines has helped revive demand for a fuel that many economies have been trying to reduce. The International Energy Agency now expects global coal consumption to rise 1.2% in 2026, reaching 8.94 billion tonnes and setting another record. Its previous outlook had pointed towards a small decline. The revision came largely from the effects of the Middle East conflict and weather-related factors. How long that revival lasts will depend heavily on what happens to gas.
Coal is Benefiting from a Gas Shock
The connection between LNG and coal is central to the current market. The conflict has disrupted LNG flows through the Strait of Hormuz, raising concerns about gas availability and prices. Coal has consequently become more competitive in power markets where generators can switch between the two fuels.
Japan and South Korea are particularly important because their power systems rely heavily on imported fuels. The IEA says gas-to-coal switching in these markets has increased demand for internationally traded coal. Europe has experienced a similar, though more limited, effect. The impact should not be mistaken for another 2022-style coal shock.
During the energy crisis that followed Russia’s invasion of Ukraine, international coal prices surged above 400 dollars a tonne across major benchmarks. The first half of 2026 has been considerably less dramatic. Newcastle thermal coal averaged 139 dollars a tonne in June, and stood at 131 dollars a tonne in August. The market has tightened, but it is not experiencing the kind of supply panic seen four years ago.
Asia is Where the Coal Trade is Being Tested
China remains the largest force in the global coal market, but its role in international trade is changing. For years, rising Chinese coal imports helped compensate for declining imports elsewhere. That changed in 2025. Chinese imports weakened and global coal trade contracted, while growing purchases in Southeast Asia were not large enough to make up the difference.
China’s domestic market also became more complicated in 2026 after a fatal coal-mine accident in Shanxi province triggered safety inspections. Production fell sharply in June and July, tightening domestic supplies, particularly of coking coal. That disruption is changing where China obtains some of its metallurgical coal.
Mongolian coking coal exports to China are expected to rise by more than 50% in 2026, reaching about 91 million tonnes. Much of that coal moves by rail, giving Mongolia a larger role in supplying the Chinese steel industry as domestic production faces disruption. The shift is significant because it shows how quickly coal trade routes can change when domestic supply is interrupted.
Southeast Asia is Becoming the Other Growth Centre
The longer-term coal story is moving east as mature markets reduce consumption. Coal demand across ASEAN is expected to reach about 574 million tonnes in 2026. Indonesia and Vietnam account for much of the growth. Indonesia is particularly important because coal remains deeply embedded in its electricity system and in captive power generation for energy-intensive industries such as nickel, cement and aluminium.
Vietnam faces a different combination of pressures. Heatwaves have increased electricity demand, while the need to replenish coal stocks has supported imports. The IEA also expects El Niño conditions to put further pressure on coal demand by increasing cooling requirements and reducing hydropower output.
These markets are expanding at a time when Japan, South Korea and the European Union are moving in the opposite direction. That divergence is becoming one of the defining features of the international coal trade.
Europe is Still Moving Away from Coal
Europe has not reversed its coal phase-down. Higher gas prices have simply slowed the decline. The IEA expects EU coal demand to reach 276 million tonnes in 2026. The fall is expected to be less pronounced than previously forecast because higher gas prices have made coal more attractive in countries such as Germany and Poland, where coal capacity remains available.
The broader direction remains unchanged. Renewable generation is expanding, nuclear availability is improving in some markets, coal phase-out policies remain in place and industrial coal demand is weakening. The IEA therefore expects the structural decline in European coal consumption to continue.
The current increase in coal use is better understood as a response to an unusual gas-price environment than as a reversal of Europe’s energy transition.
Exporters are Feeling the Shift Differently
The changes in demand are creating winners and losers among coal exporters. Indonesia, the world’s largest thermal coal exporter, is expected to reduce production in 2026. Lower production targets and export-related regulatory measures have tightened expectations for seaborne supply. Australia is better positioned to fill part of the gap.
Australia remains the dominant exporter of metallurgical coal and is expected to ship more than 150 million tonnes in 2026. Russia is also expected to remain an important supplier to Asian markets, although sanctions, logistics constraints and higher export costs continue to weigh on its competitiveness.
For Russia, the geography of the coal trade has changed substantially since European sanctions disrupted its traditional markets. Its Far Eastern ports provide better access to Asian buyers, while Black Sea and Baltic shipments face greater pressure from route economics and market access. Russian coal therefore remains competitive in parts of Asia, but generally at a discount to Australian and South African benchmarks. The result is a coal market increasingly organised around Asian demand and the ability of exporters to reach it.
The Coal Trade is Already Preparing For a Downturn
The current recovery may prove temporary. If LNG flows through the Strait of Hormuz return towards pre-conflict levels and gas prices fall, much of the incentive for gas-to-coal switching will disappear. The IEA consequently expects global coal demand to fall by 0.4% in 2027 to 8.91 billion tonnes under that scenario.
The same pattern appears in international trade. Coal shipments are expected to resume their decline in 2027, with thermal coal trade falling across much of Asia and Europe. China is expected to remain the biggest drag on imported thermal coal, while the European Union, Japan, South Korea and Chinese Taipei continue their longer-term reductions in imports. Southeast Asia is expected to remain an exception, with Viet Nam and the Philippines providing some growth. It will not be enough to compensate for the declines elsewhere.
Metallurgical coal is likely to hold up better. India’s expanding steel production and limited domestic supplies of high-quality coking coal are expected to increase imports, offsetting weaker demand from China and other mature markets. Australia stands to capture much of that additional trade.
Geopolitics and Interconnected Fuel Markets
The most revealing part of the 2026 coal outlook may not be the record consumption figure. It is the route by which the increase has happened. A disruption affecting LNG has altered gas prices. Higher gas prices have changed the economics of electricity generation. That has increased coal demand in countries with the ability to switch fuels, tightened some international coal markets and altered trade flows between producers and consumers.
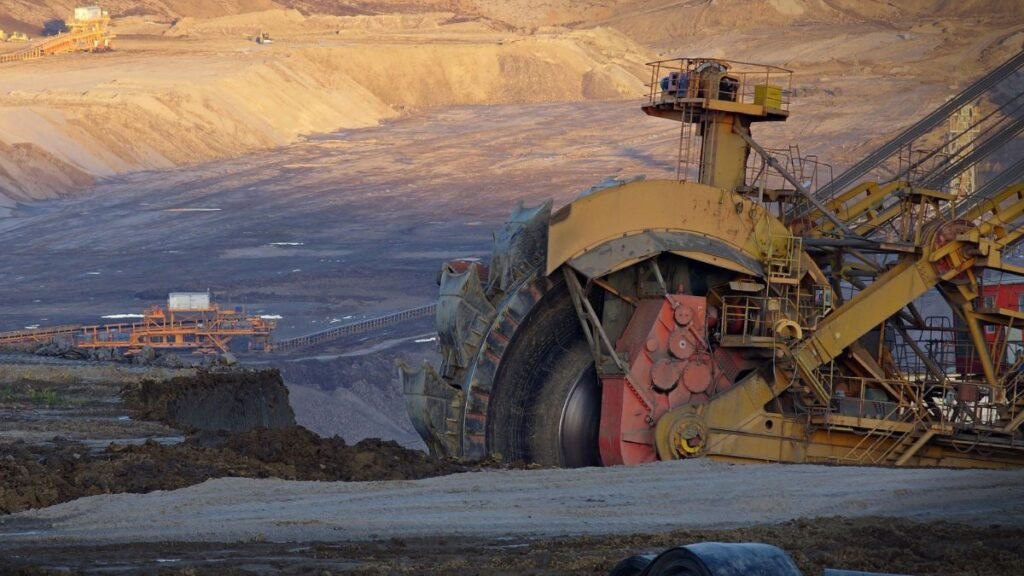
The effect is temporary in some markets and structural in others. Japan, South Korea and the European Union are still on a longer-term path towards lower coal consumption. China is producing more of its own coal and importing less thermal coal. Southeast Asia is adding coal demand as electricity consumption and industrial activity expand. India remains an important source of both thermal and metallurgical coal demand.
For the international coal market, that leaves two forces pulling in opposite directions: a short-term geopolitical shock that has made coal more valuable in some power systems, and a longer-term transition that is steadily shrinking its role in several major economies. The direction of the market in 2027 may depend on which one proves stronger.



Sustainable Energy
India’s Clean Energy Research May Not Be Keeping Pace with Its Manufacturing Ambitions, Finds Study
A study of India’s publicly funded clean-energy research examines whether investments in solar power, batteries and other technologies are aligned with the country’s ambitions for domestic manufacturing and technological development.
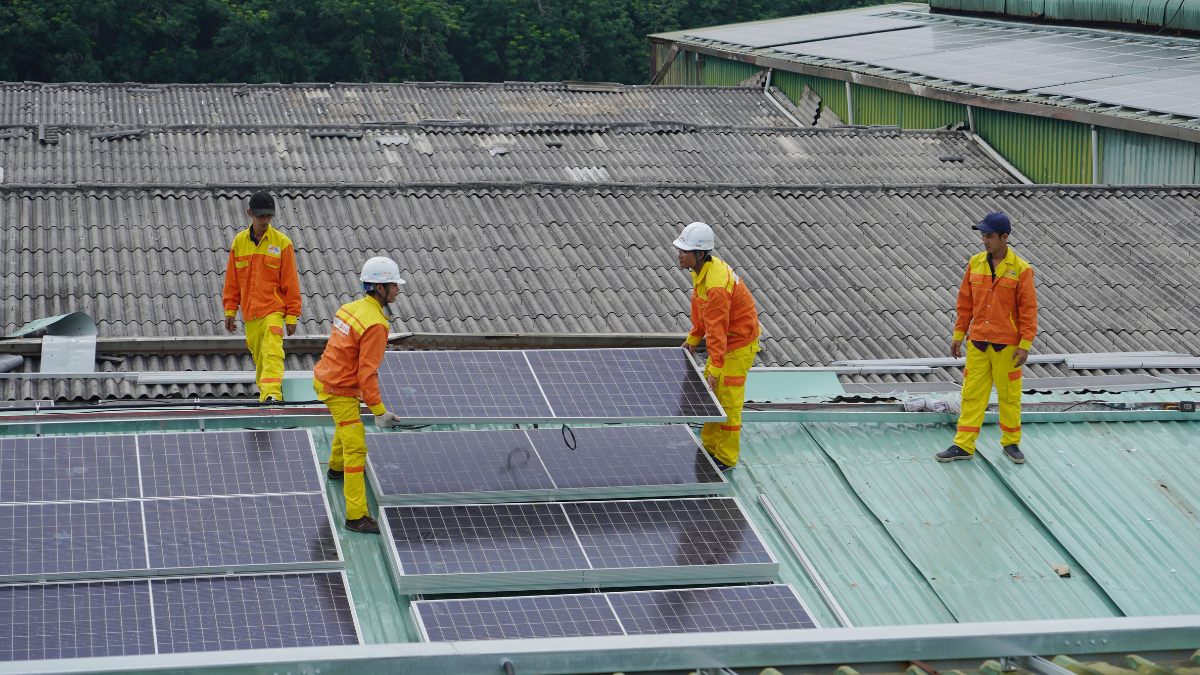
India’s public investment in clean-energy research is concentrated in established technologies, while funding for manufacturing innovation and large-scale technology development remains a challenge, according to a new study examining the country’s publicly funded research, development and demonstration (RD&D) activities.
The report, How Can India Align Its Clean Energy Innovations with Its Ambitions? An Assessment of Public RD&D Investments and Activities, by the Sustainable Futures Collaborative (SFC) and the Climate Policy Lab at Tufts University, maps 1,359 publicly funded clean-energy projects active or initiated between the financial years 2019 and 2024.
The projects span more than 90 institutions and account for approximately ₹1,443 crore in declared funding. The study finds that India has developed a substantial public research portfolio, but raises questions about whether its funding structures and research priorities are sufficiently aligned with the country’s ambitions for domestic manufacturing and technological leadership.
The findings echo concerns raised in other research on India’s clean-energy supply chains and innovation financing. Together, these studies highlight a challenge that extends beyond funding scientific research: ensuring that promising technologies can progress from laboratory development to demonstration, competitive manufacturing and commercial deployment.
Solar and storage dominate the research landscape
Renewable energy accounts for a substantial share of the mapped research portfolio. The SFC–Tufts study identifies 421 renewable-energy projects receiving approximately ₹580 crore, while another 333 projects in other power and energy-storage technologies account for around ₹492 crore.
Solar photovoltaic technology alone received approximately ₹401 crore across 234 projects, making it a major focus of public clean-energy research.
The portfolio also includes research on batteries, hydrogen, electric mobility, energy efficiency and carbon capture, utilisation and storage. However, the distribution of projects and funding varies across these areas, with electric mobility receiving less attention than solar energy, batteries and hydrogen.
The concentration of research in established technologies reflects India’s immediate clean-energy priorities. Solar power and battery storage are central to expanding renewable electricity and managing its intermittency. Research that improves the performance, reliability and affordability of these technologies can contribute directly to deployment.
India’s operating conditions also create specific research requirements. High temperatures, dust, humidity, price-sensitive demand and constraints in accessing materials and equipment can make technologies developed elsewhere less suitable without adaptation. Research into battery thermal management, solar-module degradation and affordable charging infrastructure can help technologies perform more effectively under Indian conditions.
However, the report argues that research addressing immediate deployment needs must also be considered alongside the longer-term development of domestic manufacturing capabilities and new technological solutions.
Incremental innovation dominates public funding
One of the study’s central findings is that approximately 81 per cent of the mapped projects can be classified as incremental innovations. These projects primarily seek to improve or adapt technologies that are already commercially established.
Such research is not necessarily a weakness. Incremental improvements can reduce costs, improve efficiency and make technologies more reliable in local conditions. The concern is whether the existing portfolio provides sufficient support for other forms of innovation needed to strengthen manufacturing and develop technological leadership.
The report finds that deployment-and-diffusion projects account for approximately 53 per cent of projects and 64 per cent of declared funding. Technology-leadership projects represent around 14 per cent of projects and 15 per cent of funding.
Solar panels under the backdrop of a clear sky.Image credit:Pexels
Process-oriented research receives a smaller share. Projects classified under manufacturing competitiveness account for approximately 28 per cent of projects and 18 per cent of funding, while projects targeting major changes in production processes represent around 5 per cent of projects and 3 per cent of funding.
A 2024 report by the Council on Energy, Environment and Water (CEEW), Strengthening India’s Clean Energy Supply Chains, examines manufacturing competitiveness across solar photovoltaics, wind turbines and lithium-ion batteries. It explores the supply-chain segments that matter for developing domestic industrial capabilities.
Read alongside the SFC–Tufts assessment, the CEEW report provides a broader perspective on the challenge of connecting research priorities with the industrial capabilities needed to manufacture clean-energy technologies in India.
Small grants and fragmented funding pose challenges
The SFC–Tufts study also highlights the size and distribution of research grants.Around 68 per cent of projects with declared budgets receive less than ₹50 lakh each. The median project size across technology categories ranges from approximately ₹33 lakh to ₹39 lakh.
These grants can support investigator-led research, early-stage experiments and improvements to existing technologies. However, projects involving pilot manufacturing, demonstration facilities, process development and commercial-scale validation may require different funding arrangements and substantially larger investments.
The report identifies differences in the funding approaches of government institutions. The Department of Science and Technology accounts for more than half of the mapped projects, reflecting its support for a large number of investigator-led grants. The Ministry of New and Renewable Energy supports fewer projects through comparatively larger programmes.
The study also finds that the 20 leading institutions account for close to 70 per cent of mapped projects.
These patterns matter because clean-energy innovation involves several stages, from scientific research and engineering to manufacturing, testing and commercial deployment. A funding structure suited to an early-stage research project may not be sufficient for a technology approaching industrial use.
An earlier CEEW study, Financing Clean Energy Innovation, examined the financing challenges associated with advancing clean-energy innovations. Its focus on financing complements the SFC–Tufts report’s emphasis on funding structures and the need to support different stages of technological development.
Technologies may require continued support after the initial research phase, particularly when they need to be demonstrated, tested and refined before becoming commercially viable. If funding does not adequately cover these stages, innovations can struggle to move from technical promise to market adoption.
Aligning research with industrial priorities
India already has policy mechanisms intended to promote clean-energy research and technology development. The Ministry of New and Renewable Energy’s Renewable Energy Research and Technology Development Programme includes objectives related to indigenous technology development, cost reduction, demonstration and collaboration with industry.
The question, therefore, is not simply whether India funds clean-energy research, but whether its research portfolio and funding mechanisms are appropriately structured to meet different objectives.
The SFC–Tufts report recommends clearer priorities across three broad goals: accelerating the deployment of existing technologies, strengthening domestic manufacturing competitiveness and developing technological leadership in emerging areas.
The study has limitations. Budget information was unavailable for around 16 per cent of mapped projects, while start-year information was missing for approximately 39 per cent. Private-sector innovation also falls outside its scope. Its findings therefore reflect the publicly documented research portfolio, rather than the entirety of India’s clean-energy innovation ecosystem.
Nevertheless, the findings raise an important policy question as India pursues both clean-energy deployment and domestic manufacturing: whether public research investment is supporting the entire journey from scientific discovery and technological improvement to competitive production and commercial scale.
The challenge is not simply to fund more research. It is to ensure that promising research can progress into technologies that India can manufacture, improve and deploy at scale.
Sustainable Energy
India Tightens CAFE Norms as Fuel Demand and Car Sales Rise
India’s new CAFE norms tighten fleet fuel-efficiency targets from 2027, with implications for petrol cars, hybrids, EVs and the country’s oil demand.
India will make carmakers meet stricter fuel-efficiency targets from April 2027, as the country tries to contain fuel consumption from a growing passenger-vehicle market. The new Corporate Average Fuel Economy (CAFE) norms will apply from April 1, 2027, to March 31, 2032. The fleet-average fuel-consumption target will fall from 3.996 litres per 100 km in 2027–28 to 3.3273 litres per 100 km in 2031–32.
That is a 16.7% improvement in the regulatory benchmark over the five-year period. The change matters because India’s demand for road fuel is rising while the country continues to import more than 90% of the crude oil it uses. Cars that consume less fuel can reduce the amount of petrol and diesel needed to keep the growing vehicle fleet on the road.
The new rules also give manufacturers more room to use electric vehicles, hybrids, alternative fuels and other efficiency technologies to meet their targets.
CAFE Norms: Why India Needs to Use Less Fuel
India’s passenger-vehicle market has changed considerably over the past decade. SUVs and larger cars have become more common, while overall vehicle ownership continues to rise. Every additional petrol or diesel vehicle adds to fuel demand. A more fuel-efficient fleet can slow that increase, even when the number of vehicles continues to grow.
The country’s dependence on imported crude makes this particularly relevant. India imports more than 90% of its crude oil, so higher oil consumption also means greater exposure to international oil prices and supply disruptions. The Bureau of Energy Efficiency introduced CAFE standards in 2017 with three objectives: reduce fuel consumption, lower carbon dioxide emissions and reduce dependence on imported oil. The latest notification tightens those requirements for the next five years.
CAFE: Not Same Mileage Target for Every Car
CAFE works differently from a rule that says every vehicle must deliver a particular number of kilometres per litre. It measures the average fuel consumption of a manufacturer’s passenger-vehicle fleet. The calculation takes sales volumes and vehicle weight into account. A company selling fuel-hungry SUVs, for instance, can improve its fleet average by selling more efficient cars, hybrids or electric vehicles.
That gives manufacturers several ways to meet the requirement. They can improve engines and transmissions, reduce energy losses, introduce hybrid systems, sell more EVs or use technologies that receive concessions under the CAFE framework.
What does the 16.7% Improvement Mean?
The 16.7% figure refers to the regulatory fleet benchmark. It does not mean that every new car will use 16.7% less petrol or diesel. Actual fuel consumption depends on the vehicle and how it is driven. Traffic, road conditions, speed, air-conditioning use and driving behaviour all affect mileage. The target applies to the manufacturer’s fleet as a whole.
The new framework also changes the vehicle-weight calculation. The reference weight will rise from 1,082 kg to 1,229 kg. The target curve has been revised so that heavier vehicles face greater efficiency requirements than lighter ones. That change is relevant to India’s passenger-vehicle market, where larger SUVs now account for a substantial share of sales.
Why EVs can Help Manufacturers Meet CAFE Targets
Electric vehicles have a direct advantage under a fuel-economy regulation because they do not consume petrol or diesel.
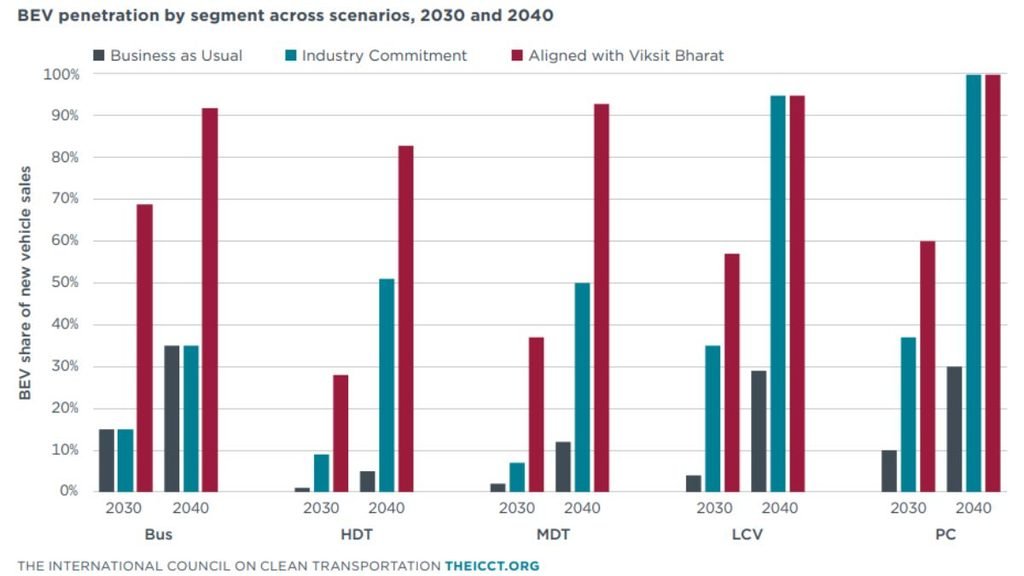
A manufacturer can therefore improve its fleet-average performance by increasing the share of EVs it sells. Hybrids can also reduce the average fuel consumption of a fleet.
The International Council on Clean Transportation (ICCT) has examined this relationship in its latest study of India’s vehicle market. Its 2026 analysis finds that stronger fuel-economy standards can support faster EV adoption and reduce oil consumption when the two policies move together. There is some evidence from India’s earlier CAFE rules as well.
An ICCT assessment of CAFE Phase II found that manufacturers relying on conventional efficiency improvements or CNG had difficulty meeting the targets. Manufacturers with significant EV sales, including Tata and MG, were able to meet the requirements with larger margins. The experience shows how a fleet standard can influence the technology choices made by manufacturers.
Stronger Standards Could Reduce Oil Demand
ICCT’s latest study models India’s road-transport oil demand under several policy pathways through 2040. In its business-as-usual scenario, road-transport oil consumption reaches about 197 million tonnes of oil equivalent (Mtoe) in 2040. An alternative scenario combines stronger fuel-efficiency standards with faster EV adoption. Under that pathway, oil consumption is about 146 Mtoe in 2040.
The difference is roughly 51 Mtoe. These are modelled scenarios, not forecasts. They show the scale of the difference that could emerge if India combines tighter efficiency rules with faster electrification. For India, lower oil demand would also reduce the amount of crude that has to be imported to supply road transport.
Technologies Beyond EVs
Electric vehicles are only one part of the new framework. The norms recognise 12 fuel-conservation technologies, compared with four under the earlier framework. These include technologies such as high-efficiency air-conditioning systems, advanced glazing and solar-reflective paints.
Each eligible technology can receive a concession of 1 gram of CO₂ per kilometre, subject to a maximum of 9 grams of CO₂ per kilometre. The framework also includes a Carbon Neutrality Factor for ethanol-blended petrol, biofuels and compressed biogas. This allows manufacturers to use a wider combination of technologies and fuels when working towards their fleet targets.
Super Credits Could Shape How Manufacturers Respond
The rules provide additional regulatory benefits for battery-electric vehicles, range-extended EVs, plug-in hybrids, strong hybrids and flex-fuel vehicles through volume derogation factors and super credits. These mechanisms give low-emission vehicles greater weight in the compliance calculation.
There is a trade-off, however. ICCT’s latest analysis points out that generous super credits can allow manufacturers to meet fleet targets with a relatively small share of EVs while continuing to sell less-efficient combustion-engine vehicles. That makes the treatment of these credits important as EV sales increase.
What Manufacturer Misses the Target?
The rules give companies several ways to manage compliance. Manufacturers can operate within two- or three-year compliance blocks. Credits can be carried forward, traded or exchanged. The Bureau of Energy Efficiency will also operate a buyout mechanism.
The system therefore gives manufacturers some flexibility in how they meet the target. It also means the effect of the regulation may not be visible in a single year’s sales figures.
Will Consumers Notice the Change?
Some changes could be visible in the showroom. Manufacturers may introduce more efficient petrol engines, expand hybrid offerings or increase the number of EVs in their portfolios. Other changes, such as improvements to air-conditioning systems or vehicle design, may be harder for buyers to notice.
The immediate effect on fuel bills is less straightforward. A regulatory improvement of 16.7% cannot be translated directly into a 16.7% saving for a driver. CAFE is calculated across a manufacturer’s fleet, while real-world mileage varies from one vehicle and driver to another. Its effect is likely to appear gradually as new vehicles replace older ones.
CAFE: One Part Larger Transport Shift
Tighter fuel-efficiency standards can reduce the amount of fuel consumed by each vehicle. They do not determine how many vehicles people buy or how much they drive. Public transport, urban planning, vehicle electrification and the availability of alternative fuels will also influence India’s future oil demand.
For the automobile industry, however, the direction is clear. The average efficiency of the vehicles sold in India will have to improve over the next five years. The new CAFE norms give manufacturers several routes to get there. They can make combustion engines more efficient, sell more hybrids and EVs, use recognised fuel-saving technologies or combine these approaches. For India, the reason for tightening the rules is straightforward. More vehicles on the road do not have to mean a matching increase in fuel consumption. The next five years will show how much the industry can narrow that gap.
Sustainable Energy
How Wind Turbines Could Produce More Power From the Same Wind
Researchers find that adjusting wind turbine blade speed when machines are misaligned with the wind could help increase power output from existing turbines.


Istanbul Floods Reveal How Climate Change and Urbanisation Combine to Raise Flood Risks

Nepal’s 4.7 Billion Flood Recovery Bill Dwarfs UN Climate Fund Allocation

India–Poland to Pursue Joint Research in AI, Semiconductors and Quantum Technology

Climate Disasters Disrupted Schooling for 171 Million Students in 2025, UNICEF Finds

Brazil’s Amazon deforestation hits record low. Can the recovery last?

Knowing When to Think for Ourselves: AI, Intuition and the Education of Discernment

After a Scorching Summer, Delhi’s Children Are Slow to Return Outdoors

Two Chemists Win Nobel Prize for Solving a Century-Old Puzzle: Why Life Picks One Hand Over the Other

Marshall Islands: Why the US Nuclear Legacy Is Back Before the UN

How Wind Turbines Could Produce More Power From the Same Wind
-

 Math3 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
EP Deep Dive: Data & Solutions3 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
EP Deep Dive: Data & Solutions4 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics5 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews1 month ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate5 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society3 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society4 months ago
From Bell Labs to the Classroom: A Second Career in Teaching