Sustainable Energy
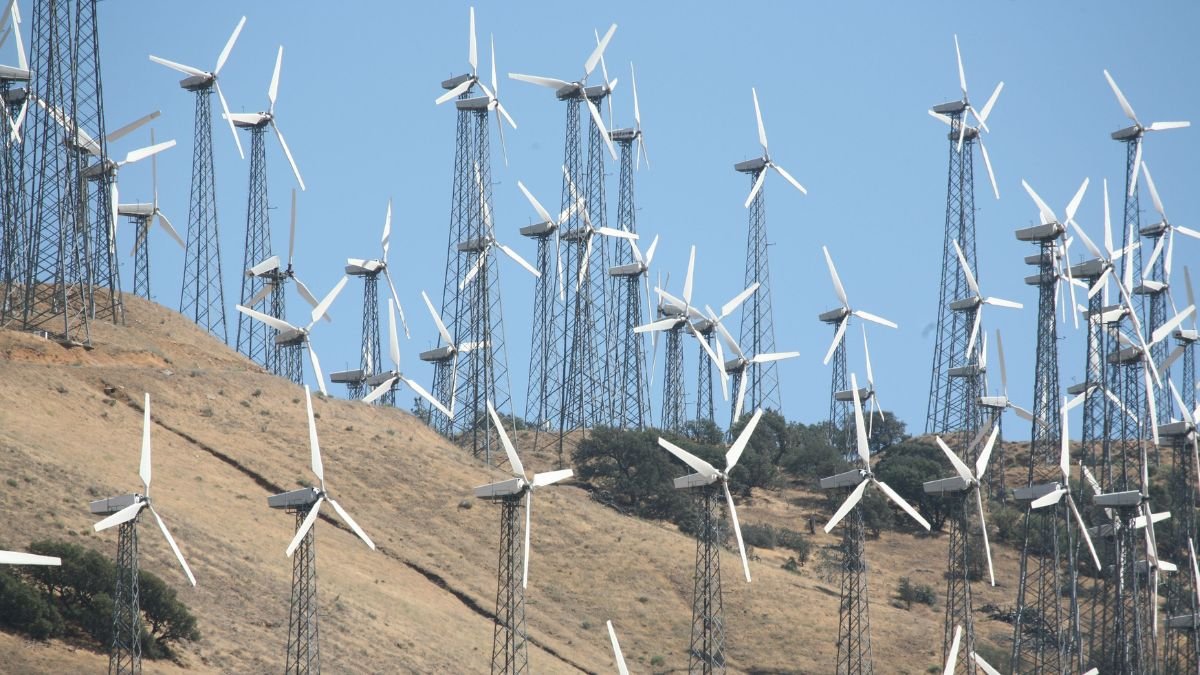
How Wind Turbines Could Produce More Power From the Same Wind
Researchers find that adjusting wind turbine blade speed when machines are misaligned with the wind could help increase power output from existing turbines.







Sustainable Energy
India’s Journey of Turning Organic Waste Into Energy. Can It Scale?
India generates more than 1.6 lakh tonnes of municipal waste every day. Across the country, organic waste is being turned into biogas, Bio-CNG, electricity and manure.
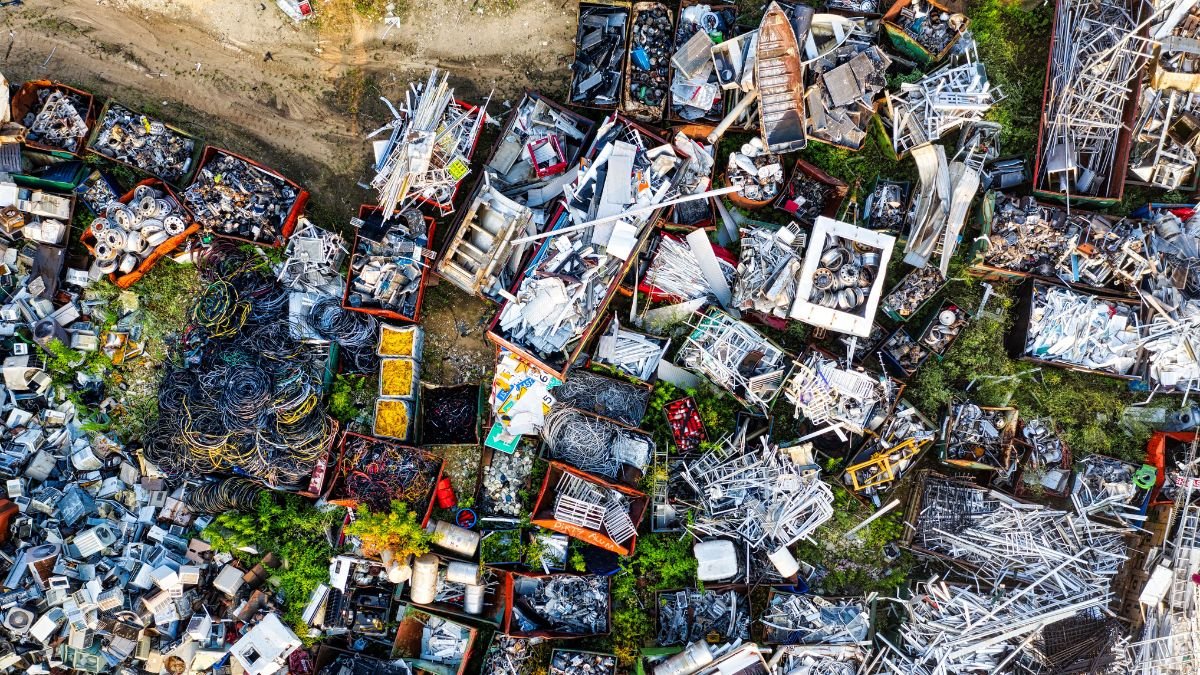
India’s cities generate about 1.62 lakh tonnes of municipal solid waste every day. Of this, around 1.32 lakh tonnes is processed, according to data reported by States and Union Territories on the Swachhatam portal in January 2026. That leaves more than 30,000 tonnes a day outside the reported processing stream.
The scale of the waste stream makes what happens to its biodegradable fraction important. Food scraps, vegetable and fruit waste, cattle dung and other organic material can either add to the disposal burden or be recovered for another use.
India’s new Solid Waste Management Rules, 2026, which came into force on April 1, make this distinction more explicit. They require waste to be separated at source into four streams, including wet waste. Kitchen waste, vegetables, fruit peels, meat and flowers are to be composted or processed through bio-methanation at the nearest facility.
Across India, projects are already using different organic waste streams to produce biogas, electricity, compressed biogas and manure. Their settings range from an educational campus and a vegetable market to a large cattle shelter and a city-scale Bio-CNG plant.
Campus that Replaced LPG with Biogas
At the Shrimati Manekba Vinay Vihar Educational Complex near Adalaj in Gujarat, the kitchen serves more than 500 people every day. Around 250 hostel students receive two meals a day, along with 15 staff families living on the campus.
The campus operates two biogas plants with a combined capacity of 90 cubic metres a day. They use dung from 222 cows kept at the institution’s cowshed, along with kitchen waste and agricultural residue from nearby fields.
The gas meets the campus’s entire cooking-fuel requirement. Without the plants, the campus would have needed around 30 LPG cylinders every month. The process also leaves behind slurry that can be used as organic fertiliser. The arrangement is relatively contained. The waste is generated within or close to the institution, and the resulting gas has a direct use on the same campus.
Vegetable Market Generating Its Own Power
At Bowenpally Vegetable Market in Hyderabad, roughly 10 tonnes of vegetable and fruit waste are collected every day. The waste was previously sent to landfills. An on-site biogas plant now processes nearly all of it. The plant generates around 400–500 units of electricity and 30 kg of biofuel every day. The electricity powers the market’s streetlights, stalls, administration building and water-supply network. The biofuel is used in the commercial kitchen.
The plant has reduced the market’s electricity bill by roughly half, from an earlier average of about ₹3 lakh a month. Five more plants have since been funded at other market yards. The project has also created work for women involved in waste sorting, machinery operation and administration. Here too, the waste source and the main users of the energy are concentrated in one location.
Prayagraj: Multiple Waste Streams Together
The Bio-CNG plant in Prayagraj operates at a much larger scale. It can process 343 tonnes of organic waste a day and produce around 21 tonnes of Bio-CNG. Its feedstock includes wet waste, paddy straw, cattle dung and poultry litter. The plant receives waste from hotels, restaurants and apartment complexes. Daily wet-waste supply has grown from around 7–8 tonnes initially to about 125 tonnes.
Along with Bio-CNG, the facility produces around 28 tonnes of compost each day, which is made available to local farmers. The gas supports city transport. The project is expected to extend piped gas access to around 45,000 households and reduce carbon emissions by approximately 57,000 tonnes annually.
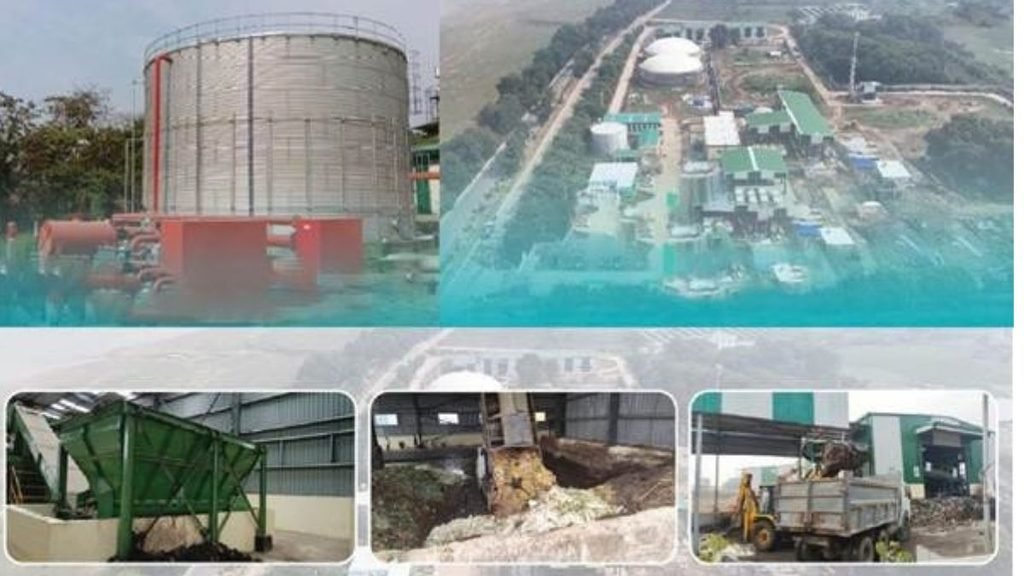
This is a different operating model from the smaller projects. Waste has to be brought in from multiple sources and supplied in sufficient quantities to keep a large facility running.
Gwalior Turns Cattle Dung Into Fuel
At Adarsh Gaushala in Laltipara, Gwalior, more than 10,000 cattle provide the main feedstock for a 100-tonne-per-day CBG plant. The ₹31-crore facility converts about 100 tonnes of cattle dung every day into two tonnes of compressed biogas. It also produces 10–15 tonnes of dry bio-manure daily.
The plant can process vegetable and fruit waste collected from markets and homes as well. The model is built around a large and concentrated source of organic material, with the resulting fuel and manure providing outlets for the products.
Waste Management: The Scale-up Problem Starts with the Waste
These projects demonstrate different ways of using organic waste. They also have conditions that are not automatically available across a city. The Gujarat campus has its own cowshed and kitchen. Bowenpally has a large quantity of similar waste concentrated in one market. Gwalior has access to thousands of cattle. Prayagraj draws from organised sources such as hotels, restaurants and apartment complexes.
Household waste presents a different problem. It is spread across thousands of locations and can contain plastics, glass and other contaminants. Recovering the organic fraction requires consistent segregation and collection. Moving it to a processing facility adds transport costs.
The plant itself is only one part of the system. A facility also needs a dependable supply of suitable feedstock. Once gas or electricity is produced, there must be a user or buyer. Compost and bio-manure need markets as well.
The 2026 rules place greater emphasis on this chain. Four-stream segregation is now mandatory, and bulk waste generators producing 100 kg or more of waste a day are required to ensure that their waste is collected, transported and processed properly. They must process wet waste on-site as far as possible or obtain an Extended Bulk Waste Generator Responsibility certificate where that is not feasible.
What the Projects Tell Us About Waste-to-energy
The four projects provide evidence of what can work when the waste stream, technology and end use are aligned. They do not establish that the same economics will apply across India’s urban areas.
The Bowenpally example, for instance, shows a substantial reduction in the market’s electricity bill, but the available account does not provide enough information on capital expenditure, operating costs or the time required to recover the investment. The same questions become more important as systems grow larger.
There is also a distinction between expected and demonstrated environmental benefits. The approximately 57,000-tonne annual carbon reduction cited for Prayagraj is an expected outcome, not a measured result reported in the source material. And the climate value of these systems cannot be judged only by what comes out of the plant. Collection, transport, processing and the energy source being replaced all form part of the calculation.
India’s waste figures show why the issue matters. More than 1.6 lakh tonnes of municipal waste enters the urban system every day, even as the country reports processing around 81% of it. The opportunity for organic waste lies in what happens before disposal becomes necessary. The challenge is making segregation, collection, processing and end-use work reliably enough for waste-to-energy to become part of that larger system.
Sustainable Energy
IEA’s New Report on What Would a Net-Zero Compatible Electricity System Require
Global electricity demand is rising rapidly, but building a net-zero-compatible power system will require far more than new generation. The IEA outlines the grids, storage and flexibility needed to keep pace.
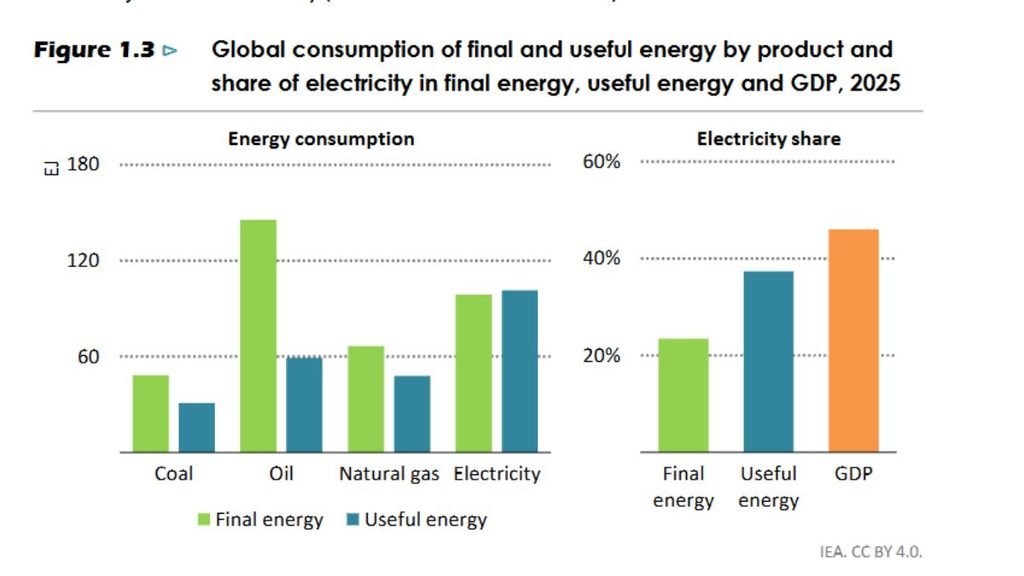
An electric car plugged in at night, a heat pump warming a home and a factory replacing a gas-fired process with an electric one may look like separate changes. They are becoming part of the same transformation or some say, the age of electrification. The change is already underway if we look closer. Global electricity demand exceeded 28,500 terawatt-hours in 2025 and has grown by more than 3% a year over the past decade, almost twice as fast as overall energy demand.
The International Energy Agency’s latest Special Report on Electrification points to the same scale of change. Its High Electrification Scenario, or HES, sees electricity rising from 23% of global final energy consumption today to 35% by 2035. The scenario is designed to be compatible with the IEA’s net-zero pathway when combined with measures such as energy efficiency.
That would mean another 1,400 TWh of electricity demand every year through 2035, about twice the annual increase recorded during the previous decade. But are we ready to keep up with this mass consumption?
Jan Rosenow, Professor of Energy and Climate Policy at Oxford University, said the technologies needed for faster electrification are already available, but current progress remains insufficient.
“Electrification is the most important lever we have to build a clean, secure and affordable energy system. today’s report shows the technologies are ready and the economic case is strong, but current progress falls well short of what is needed. We are still in the middle of an energy crisis with crippling oil and gas prices and governments must now act across every sector, from buildings and transport to industry.”
A Rapid Power Build-Out
Much of the new demand is likely to come from activities that currently depend on fossil fuels. The IEA estimates that, using current costs, prices and financing conditions, the share of electricity in final energy use could rise from 23% to around 33% globally through cost-effective opportunities alone. The HES pushes that further, to 35% by 2035.
But that extra electricity cannot simply come from whatever power plants happen to be available. Electricity generated from low-emissions sources accounted for 42% of global generation in 2025, up from 33% in 2015. Solar deployment increased more than tenfold during the decade and wind deployment more than doubled.
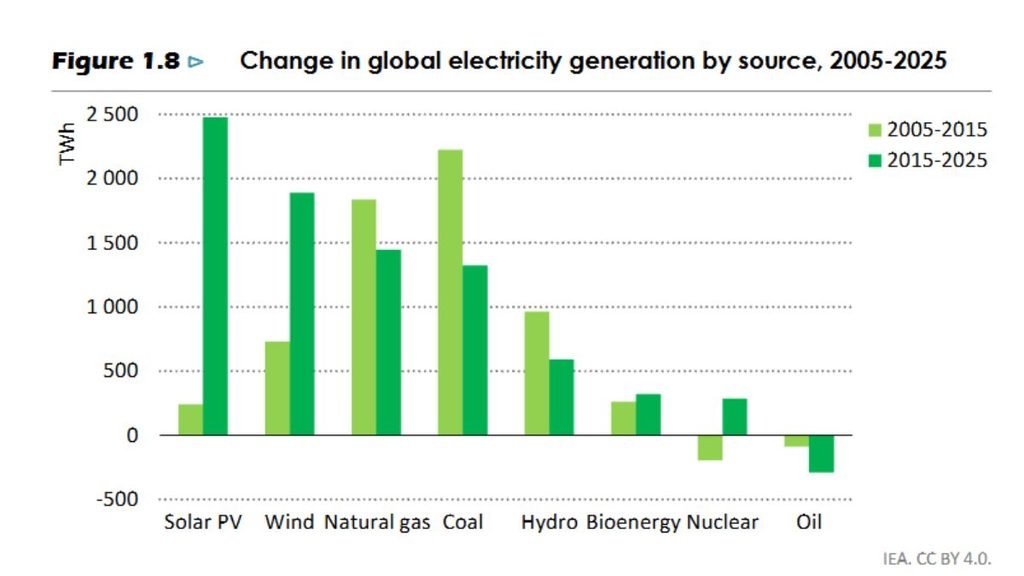
At the same time, fossil-fuel generation also increased. Power generation still produces around 14 billion tonnes of CO₂ a year, and global power-sector emissions have not yet peaked. For a net-zero-compatible system, the problem is therefore twofold: generate much more electricity while changing what generates it.
Janet Milongo, Senior Manager Energy Transition at CAN International, said the proposed 35-by-35 target would need to be assessed not only by how much energy becomes electric, but by how that electricity is generated and governed.
“The 35 by 35 target will only represent climate progress if it is powered by sustainable renewable energy. Success cannot be measured simply by how much of the world’s final energy consumption becomes electric. We must ask what generates that electricity, who has access to it, who owns the infrastructure, and whether it is helping countries transition away from fossil fuels. Developing countries must have the resources and capacity to own, govern and shape their electricity systems in the public interest.”
Solar Panels are Only the Beginning
By 2035, annual solar additions would need to exceed 1,200 GW, while annual wind additions would reach around 400 GW. Nuclear power would also expand substantially. This would provide electricity for the new demand created by electrification while replacing part of the fossil-fuel generation already on the system.
If an electric vehicle is charged with electricity produced by a fossil-fuel power plant, the energy system has changed, but its emissions have not disappeared. Electrification can deliver its full climate benefit only as the electricity supplying it becomes cleaner.
The same applies to factories, buildings and other major users. The result is a system that needs to expand generation at the same time as it changes its composition. That makes the transition more demanding than simply replacing one technology with another.
The Problem of Transfering Power
None of the sources of electricity can serve a household or factory without a network connecting generation to demand. The IEA estimates that the global electricity network would need to reach around 115 million kilometres by 2035 under the HES, with network expansion accelerating by about 40% compared with the previous decade.
That is a major infrastructure requirement, particularly because the geography of electricity supply and demand is changing. Solar generation is concentrated in certain hours. Wind output varies with weather. New renewable projects may be located far from industrial centres or cities. Meanwhile, electric vehicles, cooling and heating can create new peaks in demand.
A system built for relatively predictable electricity flows therefore has to become much more flexible. The IEA identifies connection queues, grid congestion and renewable curtailment among the problems that could slow the transition. Building transmission and distribution infrastructure earlier, improving the use of existing networks and speeding up planning and permitting become part of the climate strategy.
The grid is no longer simply the infrastructure that delivers electricity after it has been generated. It becomes one of the conditions for adding more clean generation in the first place.
Demand Side Matters
Storage is one response to this changing system. Under the IEA’s net-zero pathway, battery storage capacity would rise to around 2,900 GW by 2035, almost ten times current levels.
But the report’s picture of flexibility is broader than batteries. An electric vehicle does not necessarily have to charge at the moment it is plugged in. Some industrial processes can be shifted. Heating and cooling systems can respond to changing electricity availability. Water heaters can operate at times when the grid has more capacity.
That means electricity demand itself can become more flexible. This could become particularly important in countries where solar generation peaks during the day while electricity demand rises later in the evening.
India is one example. The country has been adding solar capacity while its electricity demand increasingly extends into evening and night-time hours. A larger solar fleet can increase daytime supply without automatically solving an evening peak.
How much electricity generated can move, store or shift to when people need it?
Richer Countries: Different Problem
In wealthier economies, electricity access is largely established. The challenge is what happens when an existing system suddenly has to serve much more demand and more variable sources of supply.
Electric vehicles, cooling, heat pumps, data centres and industrial electrification can all add load. At the same time, many of these countries have grids and power infrastructure designed around older patterns of electricity consumption. Some networks will need to be strengthened or replaced; others will need better digital controls to manage increasingly complex electricity flows.
There is also a financial problem at the household level. An electric technology can cost more to purchase while costing less to operate. That creates a barrier for households and businesses that cannot afford the initial investment, even when the technology may make economic sense over its lifetime. The IEA therefore sees financing and targeted support as part of the electrification challenge rather than as an issue separate from the energy transition.
India Sits Across Both Worlds
India illustrates how different parts of the challenge can exist within the same electricity system. Electricity demand grew by around 5% a year between 2015 and 2025. The country is also rapidly expanding renewable generation and electrifying transport.
There is significant room to electrify industrial processes. Nearly 30% of India’s industrial heat demand is below 150°C, a range where the IEA identifies substantial potential for electrification. Electric two- and three-wheelers provide another important opportunity.
But the changing timing of electricity demand creates a separate challenge. As solar generation grows during daylight hours, demand continues into the evening and night. That makes storage, flexible demand, electricity pricing and better use of the grid increasingly important. India therefore faces both sides of the global transition: expanding access to reliable electricity and preparing an already large electricity system for a much more electricity-intensive economy.
Test Between Generation and Consumption
The IEA’s proposed “35-by-35” target is ultimately a measure of how deeply electricity could enter the global energy system by 2035. But reaching that level would require much more than a larger supply of electricity.
It would require clean generation to grow fast enough to meet new demand and replace fossil generation. It would require transmission and distribution networks to expand before they become bottlenecks. It would require batteries and other forms of storage, alongside demand flexibility, to manage when electricity is produced and consumed.
Dave Jones, co-founder of Ember, described faster electrification as having benefits across household costs, emissions and energy security.
“Today’s report gives us the evidence we have all been waiting for to show that faster electrification is a triple win. A win for cheaper bills, a win for less emissions and pollution, and a win for cutting the huge fossil fuel import bill many countries face today.”
And it would require very different approaches in different parts of the world. In advanced economies, the priority is largely to transform and expand existing systems. In countries with major access gaps, electricity infrastructure has to grow alongside basic services and economic activity. Countries such as India are dealing with both challenges at once.
The technologies for much of this transition already exist. The harder task is putting them together at the required scale — and making sure the money, infrastructure, skills and institutions move with them.
That is the central question behind a net-zero-compatible electricity system: not simply whether the world can produce more electricity, but whether it can build an electricity system capable of carrying an increasingly electrified economy without carrying fossil-fuel emissions along with it.
Sustainable Energy
How a Middle East Conflict Is Reshaping the Global Coal Market
Global coal demand is forecast to rise 1.2% to a record 8.94 billion tonnes in 2026, with higher gas prices linked to the Middle East conflict encouraging coal use in parts of Asia and Europe. The IEA expects demand to ease in 2027 if LNG supplies recover.
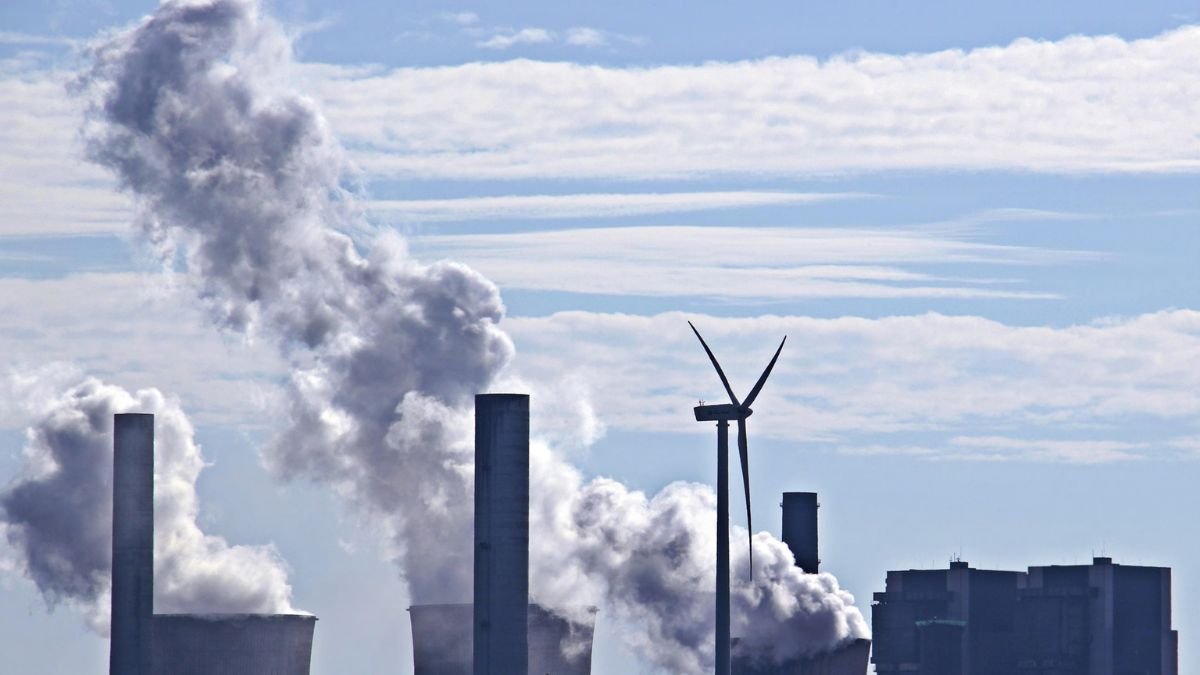
The Strait of Hormuz carries very little coal. Yet disruption there has become one of the forces shaping the international coal market in 2026. The reason is natural gas. Falling LNG shipments through the Strait pushed gas prices higher after the conflict in the Middle East intensified. In countries that have both gas-fired power plants and coal capacity available, the economics began to favour coal. Japan and South Korea, both heavily dependent on imported energy, increased their demand for traded coal. Higher gas prices also affected power markets in Europe and China.
A geopolitical crisis far from the world’s main coal mines has helped revive demand for a fuel that many economies have been trying to reduce. The International Energy Agency now expects global coal consumption to rise 1.2% in 2026, reaching 8.94 billion tonnes and setting another record. Its previous outlook had pointed towards a small decline. The revision came largely from the effects of the Middle East conflict and weather-related factors. How long that revival lasts will depend heavily on what happens to gas.
Coal is Benefiting from a Gas Shock
The connection between LNG and coal is central to the current market. The conflict has disrupted LNG flows through the Strait of Hormuz, raising concerns about gas availability and prices. Coal has consequently become more competitive in power markets where generators can switch between the two fuels.
Japan and South Korea are particularly important because their power systems rely heavily on imported fuels. The IEA says gas-to-coal switching in these markets has increased demand for internationally traded coal. Europe has experienced a similar, though more limited, effect. The impact should not be mistaken for another 2022-style coal shock.
During the energy crisis that followed Russia’s invasion of Ukraine, international coal prices surged above 400 dollars a tonne across major benchmarks. The first half of 2026 has been considerably less dramatic. Newcastle thermal coal averaged 139 dollars a tonne in June, and stood at 131 dollars a tonne in August. The market has tightened, but it is not experiencing the kind of supply panic seen four years ago.
Asia is Where the Coal Trade is Being Tested
China remains the largest force in the global coal market, but its role in international trade is changing. For years, rising Chinese coal imports helped compensate for declining imports elsewhere. That changed in 2025. Chinese imports weakened and global coal trade contracted, while growing purchases in Southeast Asia were not large enough to make up the difference.
China’s domestic market also became more complicated in 2026 after a fatal coal-mine accident in Shanxi province triggered safety inspections. Production fell sharply in June and July, tightening domestic supplies, particularly of coking coal. That disruption is changing where China obtains some of its metallurgical coal.
Mongolian coking coal exports to China are expected to rise by more than 50% in 2026, reaching about 91 million tonnes. Much of that coal moves by rail, giving Mongolia a larger role in supplying the Chinese steel industry as domestic production faces disruption. The shift is significant because it shows how quickly coal trade routes can change when domestic supply is interrupted.
Southeast Asia is Becoming the Other Growth Centre
The longer-term coal story is moving east as mature markets reduce consumption. Coal demand across ASEAN is expected to reach about 574 million tonnes in 2026. Indonesia and Vietnam account for much of the growth. Indonesia is particularly important because coal remains deeply embedded in its electricity system and in captive power generation for energy-intensive industries such as nickel, cement and aluminium.
Vietnam faces a different combination of pressures. Heatwaves have increased electricity demand, while the need to replenish coal stocks has supported imports. The IEA also expects El Niño conditions to put further pressure on coal demand by increasing cooling requirements and reducing hydropower output.
These markets are expanding at a time when Japan, South Korea and the European Union are moving in the opposite direction. That divergence is becoming one of the defining features of the international coal trade.
Europe is Still Moving Away from Coal
Europe has not reversed its coal phase-down. Higher gas prices have simply slowed the decline. The IEA expects EU coal demand to reach 276 million tonnes in 2026. The fall is expected to be less pronounced than previously forecast because higher gas prices have made coal more attractive in countries such as Germany and Poland, where coal capacity remains available.
The broader direction remains unchanged. Renewable generation is expanding, nuclear availability is improving in some markets, coal phase-out policies remain in place and industrial coal demand is weakening. The IEA therefore expects the structural decline in European coal consumption to continue.
The current increase in coal use is better understood as a response to an unusual gas-price environment than as a reversal of Europe’s energy transition.
Exporters are Feeling the Shift Differently
The changes in demand are creating winners and losers among coal exporters. Indonesia, the world’s largest thermal coal exporter, is expected to reduce production in 2026. Lower production targets and export-related regulatory measures have tightened expectations for seaborne supply. Australia is better positioned to fill part of the gap.
Australia remains the dominant exporter of metallurgical coal and is expected to ship more than 150 million tonnes in 2026. Russia is also expected to remain an important supplier to Asian markets, although sanctions, logistics constraints and higher export costs continue to weigh on its competitiveness.
For Russia, the geography of the coal trade has changed substantially since European sanctions disrupted its traditional markets. Its Far Eastern ports provide better access to Asian buyers, while Black Sea and Baltic shipments face greater pressure from route economics and market access. Russian coal therefore remains competitive in parts of Asia, but generally at a discount to Australian and South African benchmarks. The result is a coal market increasingly organised around Asian demand and the ability of exporters to reach it.
The Coal Trade is Already Preparing For a Downturn
The current recovery may prove temporary. If LNG flows through the Strait of Hormuz return towards pre-conflict levels and gas prices fall, much of the incentive for gas-to-coal switching will disappear. The IEA consequently expects global coal demand to fall by 0.4% in 2027 to 8.91 billion tonnes under that scenario.
The same pattern appears in international trade. Coal shipments are expected to resume their decline in 2027, with thermal coal trade falling across much of Asia and Europe. China is expected to remain the biggest drag on imported thermal coal, while the European Union, Japan, South Korea and Chinese Taipei continue their longer-term reductions in imports. Southeast Asia is expected to remain an exception, with Viet Nam and the Philippines providing some growth. It will not be enough to compensate for the declines elsewhere.
Metallurgical coal is likely to hold up better. India’s expanding steel production and limited domestic supplies of high-quality coking coal are expected to increase imports, offsetting weaker demand from China and other mature markets. Australia stands to capture much of that additional trade.
Geopolitics and Interconnected Fuel Markets
The most revealing part of the 2026 coal outlook may not be the record consumption figure. It is the route by which the increase has happened. A disruption affecting LNG has altered gas prices. Higher gas prices have changed the economics of electricity generation. That has increased coal demand in countries with the ability to switch fuels, tightened some international coal markets and altered trade flows between producers and consumers.
The effect is temporary in some markets and structural in others. Japan, South Korea and the European Union are still on a longer-term path towards lower coal consumption. China is producing more of its own coal and importing less thermal coal. Southeast Asia is adding coal demand as electricity consumption and industrial activity expand. India remains an important source of both thermal and metallurgical coal demand.
For the international coal market, that leaves two forces pulling in opposite directions: a short-term geopolitical shock that has made coal more valuable in some power systems, and a longer-term transition that is steadily shrinking its role in several major economies. The direction of the market in 2027 may depend on which one proves stronger.


15,800 Additional Heat Deaths Projected: Can India’s Mortality Data Capture the Real Toll?

How Wind Turbines Could Produce More Power From the Same Wind

Artemis Accords Reach 76 Countries: What It Means for India

Why Delhi’s Air Gets Worse in Winter

AI Is Growing Fast, But Women Remain Underrepresented

From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story

Farmers Borrowed to Build ‘Diggis’. Two Years Later, They Are Still Waiting for the Subsidy

Aim for the Stars: Anjali Thomas’s Journey from a Small College in Kerala to the Frontiers of Medical Imaging

When the Himalayas Collapse Without Warning, What Counts as Preparedness?

Anxiety Freezes Career Decisions. Curiosity Unfreezes Them
-

 Math2 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
Climate2 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
Society3 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics4 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews6 days ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate4 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society3 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society4 months ago
From Bell Labs to the Classroom: A Second Career in Teaching