Society
79 Years After Independence: Is India Investing Enough in Science and Technology?
India’s R&D spending remains below 1% of GDP despite rising research output and patents. Is the country investing enough to achieve technological independence by 2047?

India’s research and development (R & D) spending has more than doubled in absolute terms, but R&D intensity remains below 1% of GDP. As India approaches 2047, the bigger question is whether its investment in science is sufficient to build the technologies and industries needed for technological independence.
When India became independent in 1947, the country had only 17 universities and 636 colleges serving about 2.38 lakh students. Literacy was around 14%. Nearly eight decades later, India has built a vastly larger education and research system. The country had 1,168 universities, 45,473 colleges and 12,002 standalone higher-education institutions in 2021–22, according to the All India Survey on Higher Education.
But as India looks towards its centenary of Independence in 2047, its scientific ambitions are running into a persistent question: is the country investing enough in research and development to build the technologies it will need? India’s R&D spending has increased sharply in absolute terms. Yet as a share of the economy, it has remained below 1%.
India’s R&D Spending Remains Below 1% of GDP
India’s gross expenditure on research and development rose from ₹60,197 crore in 2010–11 to ₹1,27,381 crore in 2020–21, according to the Department of Science and Technology. However, R&D expenditure as a share of GDP was 0.64% in 2020–21. The corresponding figure was 0.66% in both 2018–19 and 2019–20.
This means that while India’s research spending more than doubled over the decade, R&D intensity remained at roughly two-thirds of 1% of GDP. The latest detailed official figure available for India is therefore 0.64% for 2020–21. WIPO’s Global Innovation Index 2025 uses an R&D intensity figure of 0.65%, based on 2020 data. One of the most commonly used measures of a country’s research effort is R&D intensity—the amount a country spends on research and development as a percentage of its gross domestic product (GDP). It allows researchers to compare the relative priority given to R&D across economies of very different sizes.
There is currently no single internationally comparable R&D figure for every country for 2026. UNESCO’s new global R&D data collection is still underway, with the resulting data scheduled for release in November 2026.
Government Still Funds the Larger Share
The issue is not only how much India spends on R&D, but who pays for it. Government accounted for 59.2% of India’s gross expenditure on R&D in 2020–21, while business enterprises accounted for 40.8%, according to DST data.
The figures point to India’s continuing dependence on public funding for research. That becomes significant as research moves into areas such as semiconductors, biotechnology, artificial intelligence, quantum technologies, advanced materials and clean energy. These fields can require expensive infrastructure, specialised equipment and long development cycles before research produces commercially viable technologies.
Increasing private-sector participation is therefore likely to be as important as increasing the overall R&D budget.
India is Producing More Patents and Research
Despite its relatively low R&D intensity, India has become a significant contributor to global research and innovation. The latest Nature Index data, covering April 2025 to March 2026, records 3,565 research articles from India in the journals tracked by the index.
Patent activity has also grown rapidly. Indian applicants filed 76,470 patent applications worldwide in 2024, according to the World Intellectual Property Organization. This was a 19.2% increase over 2023 and placed India sixth among origins for worldwide patent applications.
The growth marks the sixth consecutive year of double-digit growth in patent applications from India-based applicants, according to WIPO. But patent filings do not necessarily mean that inventions reach the market.
A patent can protect an invention without it becoming a commercially manufactured product. For research to generate wider economic value, it has to move through several stages—from discovery to patent, prototype, product and eventually large-scale deployment. That transition remains one of the important challenges for India’s innovation ecosystem.
India Ranks Higher on Innovation Than Its R&D Spending Suggests
India’s relatively low R&D intensity has not prevented it from performing strongly on broader measures of innovation. WIPO’s Global Innovation Index 2025 ranked India 38th among 139 economies. India was also ranked first among lower-middle-income economies and first in Central and Southern Asia.
WIPO identifies India as an innovation overperformer, citing strengths including ICT services exports, venture-capital activity and the country’s ability to translate scientific knowledge into commercial impact. The contrast is significant.
India is generating considerable innovation despite spending a relatively small share of its GDP on R&D. But that does not necessarily mean that the existing level of investment is enough to support the next generation of technologies. As research becomes more capital-intensive, countries seeking technological leadership require sustained investment in infrastructure, specialised researchers and long-term development.
China Spends Four Times India’s Share
The gap becomes clearer when India is compared with major research economies. WIPO’s latest internationally comparable estimates for 2024 put R&D intensity at 6.33% of GDP in Israel and 5.32% in South Korea. Japan and the United States were both at 3.45%, while Germany stood at 3.11%.
China’s R&D intensity reached 2.65%. By comparison, India’s latest available figure is about 0.65%. China therefore spends roughly four times India’s share of GDP on R&D. Other emerging economies also show different levels of research intensity. WIPO estimates Brazil at 1.15%, Thailand at 1.16%, Türkiye at 1.42%, Vietnam at 0.42%, the Philippines at 0.32% and Indonesia at 0.28%.
The figures are not all based on the same data year, making direct comparisons imperfect. However, the broad difference between India and the world’s leading research economies remains clear.
Government Changing The Funding Model
India has begun introducing policies aimed at expanding research funding and encouraging greater industry participation. The Anusandhan National Research Foundation was established through legislation in 2023, with a planned five-year outlay of ₹50,000 crore for 2023–28.
The foundation is intended to strengthen research across universities, colleges and research institutions and encourage collaboration between academia, industry and government.
In July 2025, the government also approved a ₹1 lakh crore Research, Development and Innovation Scheme. The scheme is intended to encourage private-sector investment in high-risk and high-impact R&D, particularly in strategic and emerging areas.
The initiatives reflect an attempt to address a longstanding problem: India’s research system needs greater private-sector participation if overall R&D investment is to rise substantially.
What Would Higher R&D Spending Change?
There is no fixed relationship between R&D spending and the number of patents, papers or technologies a country will produce. Reaching a particular percentage of GDP cannot guarantee scientific breakthroughs.
But higher sustained investment could expand the country’s research capacity. Moving from 0.64% to 1% of GDP would represent an increase of about 56% relative to India’s current R&D intensity. It could provide greater resources for research grants, laboratory infrastructure, doctoral training and advanced equipment.
At 2%, India would move much closer to China’s current R&D intensity and have a substantially larger pool of resources for research in areas such as biotechnology, advanced manufacturing, AI, semiconductors and clean energy. At 3%, India would enter the range of several major research economies. The outcome, however, would depend on how effectively that money is used.
From Research Papers to Technologies
For India, the next phase of science policy may therefore need to focus as much on the movement of research into the economy as on increasing research output. Universities need stronger research infrastructure and stable funding. Public laboratories need effective technology-transfer mechanisms. Companies need stronger incentives to conduct R&D domestically. Researchers need access to advanced equipment and long-term funding.
Success could also be measured through indicators beyond publications and patents: technologies licensed to companies, university spin-offs, industry-funded research, prototypes entering production and revenue generated from publicly supported research. This is particularly important for technologies that could shape India’s economic future.
A semiconductor process developed in an Indian laboratory, a new pharmaceutical platform, an energy-storage technology or an agricultural innovation can have an economic impact far beyond the research paper that first describes it. At the same time, basic research cannot be judged only by immediate commercial returns. Some of the technologies that eventually transform economies begin as discoveries with no obvious market.
India therefore faces a two-part challenge: expand research that pushes scientific boundaries while building the institutions and industrial capacity needed to convert discoveries into technologies.
The Science Challenge India Faces in 2047
The scientific challenge India faced in 1947 was largely about building capacity. The country needed universities, laboratories, trained researchers and institutions capable of supporting scientific inquiry. Much of that foundation now exists.
The challenge approaching 2047 is different. India is no longer simply trying to establish a scientific system. It is trying to use that system to compete in technologies that will determine economic and strategic strength. That will require more sustained investment, greater participation from industry and stronger links between research institutions and the market.
As India approaches 100 years of Independence, the question is therefore no longer only how much science the country produces. It is whether India can invest enough in that science—and build the systems around it—to turn research into technologies, technologies into industries and scientific capability into technological independence.
Editor’s Note
Dipin Damodharan, Co-founder & Editor-in-Chief, EdPublica
South Korea offers an instructive comparison. R&D intensity—the share of a country’s GDP devoted to research and development—is not, by itself, a guarantee of economic transformation. But South Korea’s experience shows what sustained investment can achieve when it is accompanied by strong university research, private-sector participation and technological development.
UNESCO’s Institute for Statistics reported that South Korea’s R&D expenditure had reached 4.03% of GDP in 2011, compared with 0.81% for India at the time. The private sector accounted for a substantial share of South Korea’s R&D expenditure, highlighting the importance of industry participation alongside public investment.
The lesson for India is therefore not simply to spend more. It is to build an ecosystem in which increased R&D funding translates into research capacity, technologies, companies and productive industries.






Society
As Indian Cities Change, What Happens to the House Sparrow?
India’s house sparrows are still common in many places, but their urban habitats are changing fast. Here’s what the shift in buildings, greenery and food sources means for a familiar city bird.
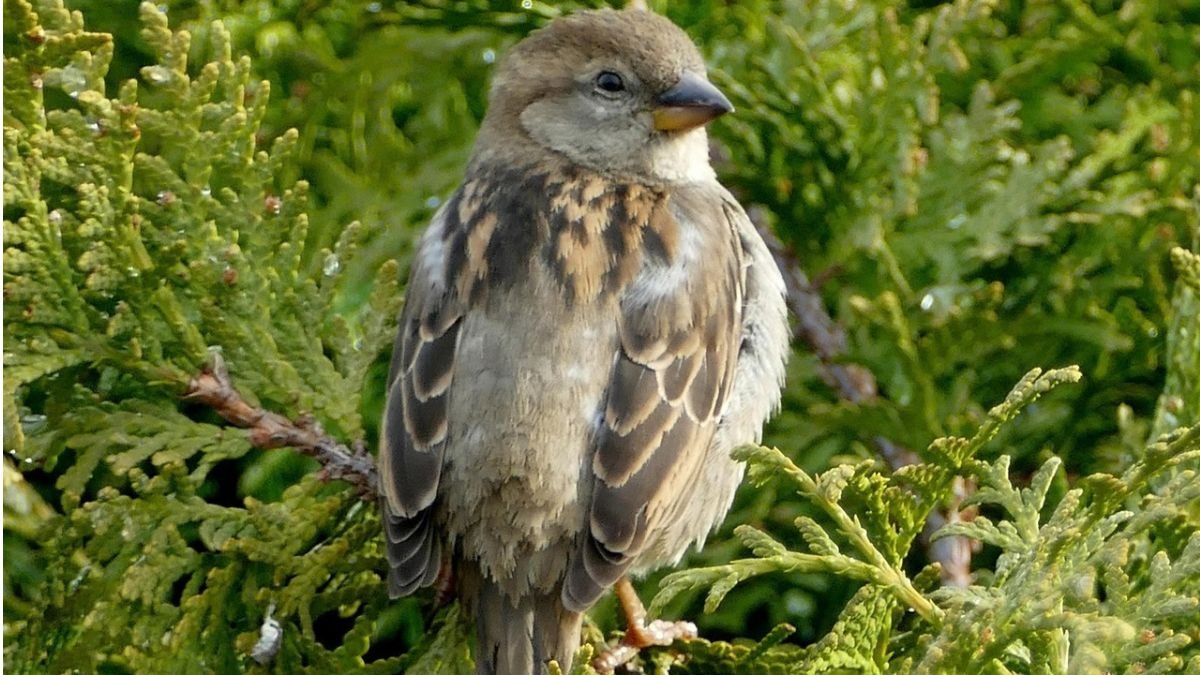
For generations, the house sparrow has been part of India’s everyday soundscape. Nesting in roof spaces, feeding near homes and markets, and appearing in balconies and courtyards. Today, however, many of the spaces that once accommodated the bird are changing. Older houses are giving way to sealed apartment buildings. Open areas are being paved. Green spaces are becoming fragmented, while traffic and construction are reshaping urban habitats.
Across Indian cities, the spaces house sparrows once used for nesting and feeding are becoming harder to find. This has led to severe decline in the number of sparrows in urban areas.
Why March 20 is World Sparrow Day
World Sparrow Day has been observed every March 20 since 2010. It was initiated by the Nature Forever Society, an India-based conservation organisation, to raise awareness about the house sparrow and declining populations of common birds. The initiative has since become an international observance.
In India, the campaign has also helped bring urban bird conservation into the public conversation. Delhi declared the house sparrow its state bird in 2012.
Are Sparrows Disappearing from India?
The house sparrow remains widespread, and available evidence does not support treating the species as uniformly declining across every part of India. Recent research from Karnataka illustrates the point. A study of 16 small and medium-sized cities recorded 57 bird species, with the house sparrow ranking among the five most abundant species observed. Researchers recorded 118 house sparrows during the survey.
But abundance in one region does not rule out declines elsewhere. Government and conservation reports have pointed to loss of nesting spaces, habitat changes and reduced food availability as potential pressures on urban sparrows. Rather than a nationwide disappearance, India is seeing a more uneven picture, with sparrows persisting in some urban areas and declining in others
The Architecture Problem
For a bird that commonly nests in cavities, buildings are more than structures. Rapid urbanization has destroyed their habitat. Older houses often had gaps beneath roofs, openings in walls and other spaces where sparrows could build nests. Modern construction tends to seal these spaces.
The result is an unintended shift in urban ecology: buildings may become more efficient and secure for people while providing fewer nesting opportunities for birds. Government sources have previously identified the replacement of older houses and courtyards by concrete multi-storey construction as one factor affecting sparrow habitat.
Survival in Question?
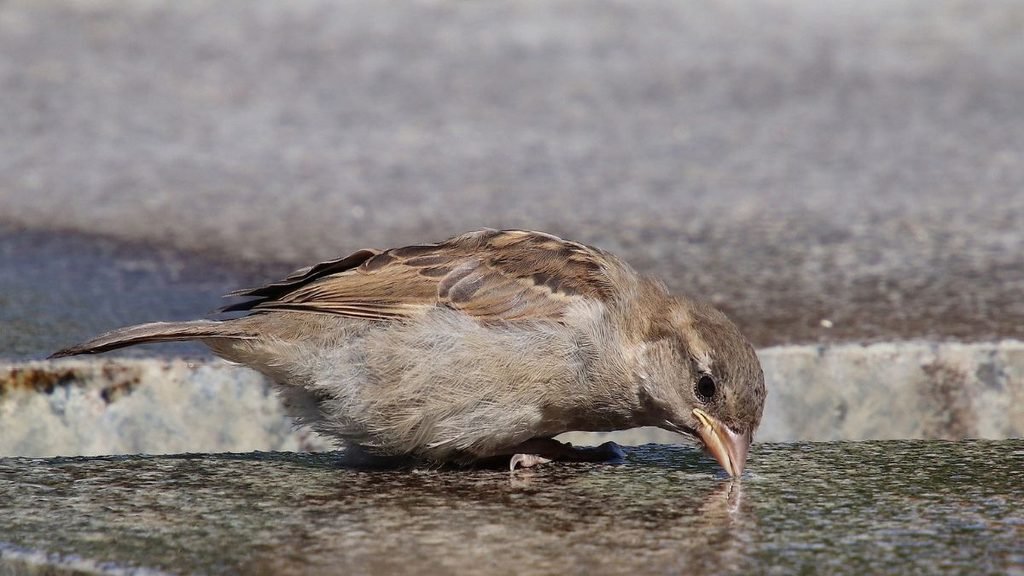
Food availability is another part of the story. Sparrows can feed on grains and seeds, but insects are important in the diet of growing chicks. Changes in vegetation and pesticide use can therefore affect the food available during the breeding season. This means putting out grain on a balcony may help individual birds, but it cannot replace the wider habitat they require.
A functioning urban habitat needs food, nesting sites, water and vegetation—not just bird feeders. Recent research in Karnataka adds another dimension to the urban bird story. The study found that the number of motor vehicles and the amount of local greenery were among the most important environmental factors associated with bird species richness and diversity across the cities surveyed.
Researchers found that greenery can provide opportunities for feeding and breeding, while traffic can create disturbance. The finding is significant because urban biodiversity is not determined only by large parks. Street trees, gardens, shrubs and smaller patches of vegetation can also shape which birds are able to live in a neighbourhood.
What Cities Can Do?
Sparrow conservation does not necessarily require large-scale wildlife projects. Nest boxes can provide alternative nesting spaces where natural cavities are unavailable. Native plants can support insects and provide food and shelter. Clean water sources can become particularly important during hot weather.
Building renovations can also take wildlife into account by avoiding the unnecessary destruction of active nesting sites. In Chennai, for instance, the Koodugal Trust has involved schoolchildren in building sparrow nest boxes. A PIB report said the organisation had built more than 10,000 nests between 2020 and 2024.
At Delhi’s National Zoological Park, World Sparrow Day activities in 2025 included a sparrow count and the distribution of 100 nest boxes to students and visitors.
Why the Sparrow has Become an Urban Warning Sign
The house sparrow is not India’s most threatened bird, nor does its presence alone measure the health of an ecosystem. Its importance is different. It is a species that has learned to live alongside people. When its habitat changes, the effects can be observed at the level of homes, streets and neighbourhoods.
That makes the sparrow an accessible entry point into a much larger issue of how India’s rapidly expanding cities can accommodate its biodiversity as well as people.
India’s urban population and built environment will continue to grow. Development will bring new roads, buildings and infrastructure. The conservation challenge is not to stop that growth, but to understand what ecological space is being lost in the process. For the house sparrow, that could be something as small as a cavity in a wall, a patch of vegetation, a supply of insects or a quiet corner in which to raise its young.
Interviews
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
As the NSE gets listed, veteran capital markets expert Uday Tardalkar reflects on the exchange’s transformation of India’s capital markets, technology, investor participation and financial inclusion.

Society
Keralam’s Western Ghats ESA debate is now about the land between forests and farms
Kerala’s latest Western Ghats ESA debate is over where conservation should end and farms, homes and settlements begin, as the state seeks changes to the Centre’s 9,993.7-sq-km proposal.
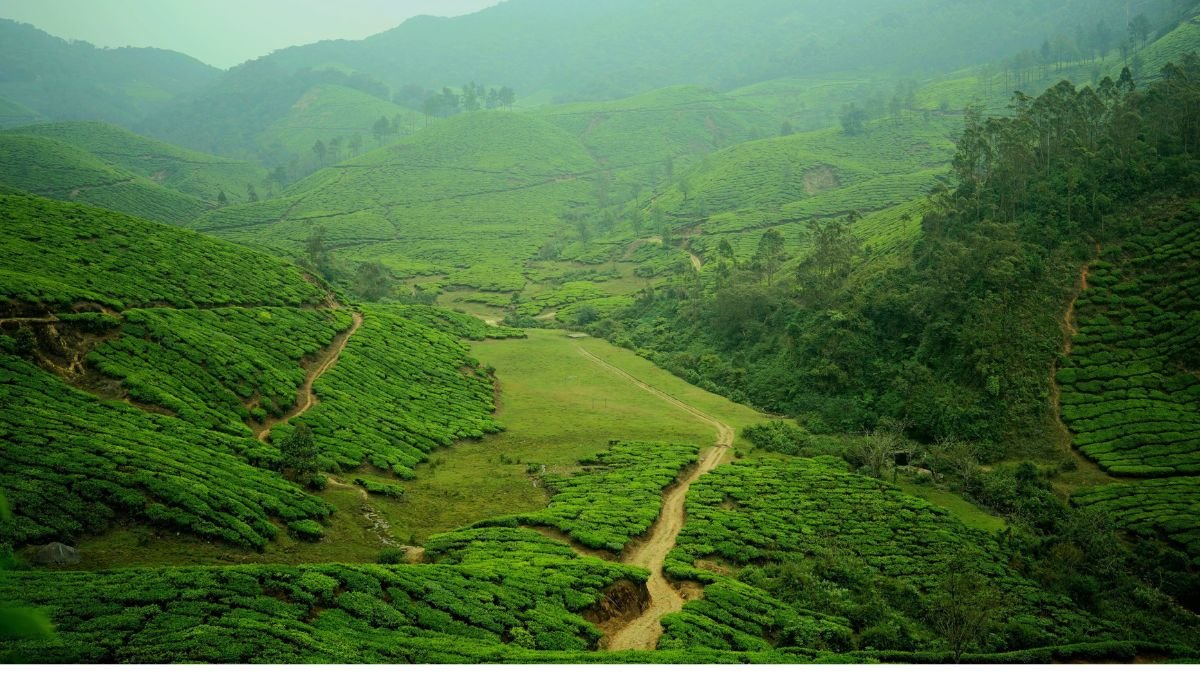
The Western Ghats, with a geological history stretching back hundreds of millions of years, is now a landscape where forests, farms and settlements coexist. Protecting it while accounting for generations of human habitation makes Keralam’s ESA boundary a particularly complex question. While there is broad recognition of the ecological importance of the Western Ghats, the question of which lands should fall within the ESA remains contentious.
Keralam is home to nearly a quarter of India’s plant diversity, with the Western Ghats accounting for much of this richness. The mountain range is also one of the world’s biodiversity hotspots, supporting species found nowhere else.
For the people living across this landscape, however, the ESA debate concerns what happens to their farms, homes and private land if they fall within the proposed boundary?
The ESA: Already Shrunk Considerably
The area proposed for ESA status in Keralam has changed substantially since the Kasturirangan exercise. The High Level Working Group headed by K. Kasturirangan had identified 13,108 sq km across 123 villages in Kerala. Subsequent physical verification by the state resulted in a smaller proposal of 9,993.7 sq km.
The composition of this area is important. About 9,107 sq km is forest, while 886.7 sq km is non-forest land. It is this non-forest portion that has become a source of concern for residents.
Environment Minister of Keralam, Sunny Joseph said people had been requesting that private properties and agricultural land should not be included in this category. He said there was no need for unnecessary anxiety over the ESA proposal and stressed the importance of creating greater public awareness about what the designation actually means.
The concern is not new. Kerala has previously sought the exclusion of populated areas and agricultural land during the process of identifying the ESA.
Why Keralam’s Landscape Makes the Debate Complicated
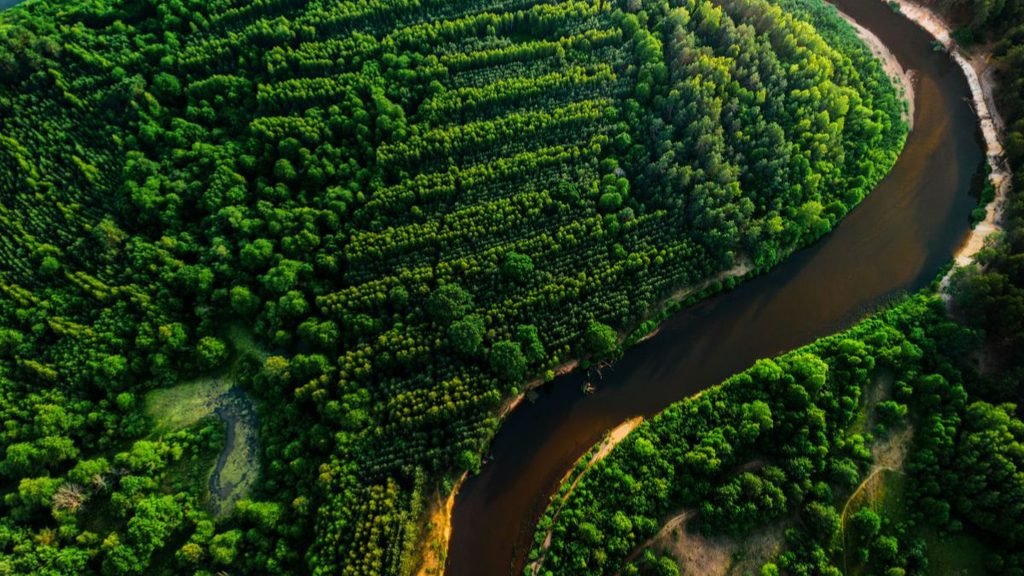
Keralam cannot easily separate its Western Ghats into neat blocks of forest and human habitation. Agricultural land, plantations and settlements are scattered through the mountain landscape. In several places, human activity exists close to forests and wildlife habitats, making the question of ecological sensitivity more nuanced than a simple forest-versus-development debate.
Oommen V Oommen, who headed the committee that examined Kerala’s ESA proposal, said the committee had interacted with people living in the Western Ghats region before making its recommendations. He pointed to the distinction made in the Kasturirangan exercise between natural and cultural landscapes.
According to Oommen, about 37% was identified as natural landscape and 63% as cultural landscape. The natural landscape, he said, should be completely protected. Farmland and other private properties were not included in the natural landscape identified for protection.
That distinction is important in Keralam, where people have lived in the Western Ghats for generations. The ESA discussion is therefore not simply about how much land should be protected, but about identifying which landscapes have the ecological characteristics that warrant stronger protection.
Joseph also pointed to Keralam’s densely populated landscape while contrasting it with states such as Tamil Nadu. Conservation boundaries that work in sparsely populated forest landscapes can have very different implications in a state where agriculture, settlements and forests are closely interwoven.
Keralam’s forests themselves cover a substantial part of the state, while the Western Ghats are central to its ecological security. The range feeds most of the state’s major rivers and supports a concentration of endemic species. While on the other hand there are many families depending on agriculture and tourism in these areas.
The Map is Changing
Even the 9,993.7 sq km figure is not necessarily the final boundary. The Keralam government has subsequently sought a further reduction in the proposed ESA and the exclusion of additional villages and populated and agricultural areas.
That makes the present debate less about whether Keralam needs to protect the Western Ghats and more about where protection is most necessary and how accurately those areas can be identified.
For residents, the distinction matters. An ESA notification can bring restrictions on certain categories of development and land use, making clarity over the boundary crucial. For conservationists, meanwhile, leaving ecologically important landscapes outside protection could weaken the purpose of the designation.
The main dilemma faced by Keralam is how they should focus on protecting a globally significant biodiversity landscape without treating every inhabited or cultivated patch of the Western Ghats in the same way.
-

 Math2 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
Climate2 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
Society3 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics4 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Climate4 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society2 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society3 months ago
From Bell Labs to the Classroom: A Second Career in Teaching
-
Interviews1 day ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story