Energy
India’s Clean Energy Research Funding Falls Short of Manufacturing Ambitions, Study Finds
A study of 1,359 publicly funded projects finds that India’s clean energy research priorities may not be sufficiently aligned with its manufacturing ambitions, highlighting the need for a clearer strategy linking innovation, industrial capacity and the Viksit Bharat @2047 vision.

As India works towards its Viksit Bharat @2047 vision, the ambition to become a developed economy will depend in part on whether the country can turn its clean energy research into the technologies, manufacturing expertise and industrial capacity needed to power its transition. But along with sits the the Department of Science and Technology’s Research & Development Statistics 2025–26 where India’s gross R&D expenditure at ₹2.45 lakh crore in 2023–24, equivalent to 0.84% of GDP. Private-sector spending contributed 51.8% of the total that year, overtaking the government sector’s 48.2% share.
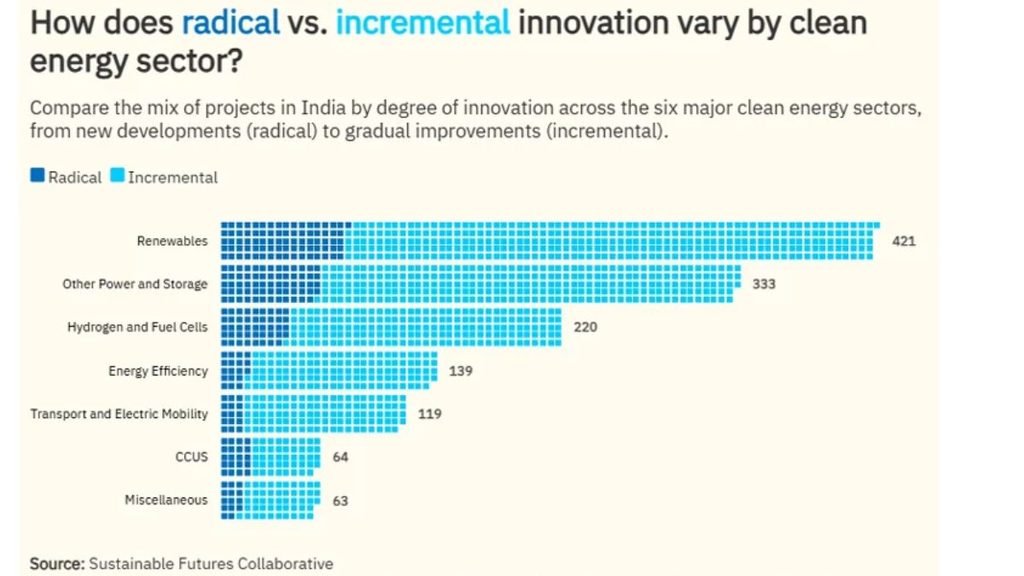
A study by the Sustainable Futures Collaborative (SFC) and the Climate Policy Lab at Tufts University has mapped 1,359 publicly funded clean energy research, development and demonstration projects across more than 90 institutions between 2019 and 2024. The projects account for approximately ₹1,443 crore in declared funding.
The study found that 81% of the projects focused on improving or adapting technologies already in commercial use, while 67% concentrated on products rather than manufacturing processes. Research into manufacturing processes accounted for about a third of projects but received only a fifth of the declared spending. India’s clean energy industrial policy now focuses on the question on how much public research funding is helping the country develop the capabilities needed to manufacture its own technologies, rather than primarily improving products that already exist?
Solar Manufacturing Exposes the Research Challenge
India’s solar industry illustrates why that question matters. Manufacturing capacity has grown rapidly, but capacity to produce solar modules and the cells inside them has developed at different rates. An analysis by the Council on Energy, Environment and Water (CEEW) estimated India’s solar module manufacturing capacity at 173 gigawatts, compared with approximately 30 gigawatts of solar cell manufacturing capacity. The difference means that the industry remains dependent on imported cells for a substantial share of its module production.
According to CEEW, around 80% of India’s module manufacturing capacity would depend on imported solar cells, primarily from China, based on the capacities assessed in its study. Solar cells are also a major component of module costs, accounting for nearly 60% of the cost of a solar module, according to the analysis.
This gap illustrates the difference between expanding assembly capacity and developing a more integrated manufacturing supply chain. Domestic cell production requires technological expertise, specialised equipment and the ability to manufacture increasingly efficient cells at competitive costs.
The SFC–Tufts study found that solar photovoltaic research received ₹401 crore, making it the largest individual technology category in the publicly funded research portfolio. That was more than the combined funding allocated to hydrogen, energy efficiency, transport and carbon capture, utilisation and storage.
The concentration of funding in solar does not, by itself, establish that the allocation is misplaced. The research portfolio also covers different stages of technological development. The concern raised by the study is whether the overall balance of funding adequately supports manufacturing capability alongside deployment and product development.
Battery Manufacturing Shows the Cost of Capability Gaps
India’s battery industry faces a related challenge. The government approved a production-linked incentive scheme in 2021 with an outlay of ₹18,100 crore to establish 50 gigawatt-hours of domestic advanced chemistry cell manufacturing capacity.
A February 2026 response by the Ministry of Heavy Industries to Parliament reported that 40 GWh of capacity had been awarded to four beneficiary companies. However, only 1 GWh of manufacturing capacity had been installed under the scheme as of the end of December 2025. The ministry said domestic demand for advanced chemistry cells continued to be met largely through imports.
The ministry identified several implementation challenges, including limited technology availability, shortages of skilled workers, dependence on imported machinery and the lack of upstream components such as cathode and anode active materials and electrolytes.
These constraints help explain why manufacturing ambitions require a supporting research and technology ecosystem. Building a battery factory involves more than securing investment and installing production lines. Manufacturers also need access to cell technologies, materials, specialised equipment and technical expertise.
Small Grants Dominate Public Research Funding
Another problem is that the funding structure is dominated by relatively small grants. Around 68% of the projects received less than ₹50 lakh each, while the median grant size varied little across technology areas, ranging from ₹33 lakh to ₹39 lakh.
The Department of Science and Technology funded just over half of the projects, largely through numerous small grants. The Ministry of New and Renewable Energy supported a smaller number of substantially larger programmes. The 20 institutions with the highest project counts accounted for 68% of all projects.
Small grants can support early-stage research, enable researchers to test ideas and allow institutions to explore different technological approaches. The study does not assess whether individual grants produced useful results or whether their size was appropriate for their objectives.
Its concern is about the combined portfolio. The available public record does not reveal an explicit strategy connecting the distribution of research funding with India’s broader priorities for clean energy deployment, manufacturing and technological leadership.
The researchers therefore raise a question about the purpose of the funding system: should public investment maintain a broad range of exploratory research, or should a greater share be directed towards selected technological capabilities that are important to India’s industrial ambitions?
The answer would influence how research programmes are designed, how funding is distributed and how progress is assessed. Manufacturing-oriented research, for instance, may require different funding scales and longer development periods than projects focused on incremental improvements to existing products.
Clean Energy Research: Wider Strategy for Innovation
India has introduced manufacturing incentives to expand domestic production of solar modules and advanced chemistry cells. These programmes demonstrate that industrial capacity is already a policy priority. The research study examines a different part of the same challenge: whether public research investment is organised to help develop the technologies and production capabilities those industries need.
The distinction matters because manufacturing capacity figures alone do not establish how much technological value is being created domestically. A country can expand final-product manufacturing while remaining dependent on imported cells, components, machinery or materials.
The report calls for greater alignment between clean energy research and India’s manufacturing and deployment ambitions. Such alignment would require a clearer view of which capabilities India already possesses, where critical gaps remain and how public research funding can help address them.
The study also has important limits. It relies on publicly available disclosures, with budget information missing for around 16% of projects and start years missing for 39%. Private-sector research—which the report says accounts for roughly half of India’s national research and development spending—is not captured. Demonstration projects and industry-linked research may also be underrepresented.
The database is therefore a substantial mapping of publicly visible research activity, rather than a complete account of India’s clean energy innovation system or an assessment of the outcomes of individual projects. Its central finding is about coordination. India has set ambitious goals for clean energy deployment and domestic manufacturing, but the public record does not yet show clearly how the country’s research investments add up to a strategy for achieving both.







Energy
Fossil Fuels Linked to Millions of Premature Deaths as Ministers Call for Healthy Energy Transition
A new ministerial declaration is calling for public health to become central to the global transition away from fossil fuels. Highlighting the health and economic costs of air pollution, it urges governments to accelerate the shift towards clean energy and strengthen the role of health systems in climate action.
The transition away from fossil fuels is not merely an environmental necessity but also a public health imperative, according to a new ministerial declaration calling on governments to accelerate the shift towards clean and renewable energy. The Political Declaration on a Healthy Transition seeks to place public health at the centre of international energy and climate policies as the 31st Conference of the Parties (COP31) to the UN Framework Convention on Climate Change (UNFCCC), which began on November 9, continues in Antalya, Türkiye.
The declaration highlights the health consequences of fossil fuel dependence, including air pollution, respiratory illnesses, cardiovascular diseases and the growing risks associated with climate change. It argues that transitioning towards cleaner energy systems could reduce the burden of disease, lower healthcare expenditure and improve workforce productivity.
According to the World Health Organization (WHO), ambient and household air pollution together account for approximately 6.7 million premature deaths annually. The declaration cites estimates that fossil fuel dependence contributes to between five and eight million premature deaths every year.
The health consequences extend beyond direct exposure to polluted air. The extraction and combustion of coal, oil and natural gas contribute to global warming, intensifying heatwaves, droughts, floods and storms. These changes threaten food and water security, increase heat-related illnesses and create conditions favourable for the spread of infectious diseases.
The Lancet Countdown 2025 Report on Health and Climate Change estimated that fossil fuel-derived outdoor air pollution caused approximately 2.52 million deaths in 2022, while household air pollution from polluting fuels and technologies accounted for another 2.3 million deaths. The report also found that heat-related mortality had increased by 23% since the 1990s, reaching an average of 546,000 deaths annually during 2012–2021.
The economic case for cleaner energy
Beyond the human toll, the declaration draws attention to the economic costs of fossil fuel dependence. World Bank estimates cited in the document put the global economic damage associated with air pollution at approximately $8.1 trillion annually, equivalent to 6.1% of global gross domestic product (GDP).
The declaration also refers to International Monetary Fund (IMF) estimates suggesting that eliminating explicit and implicit fossil fuel subsidies could prevent 1.6 million premature deaths annually and generate an additional $4.4 trillion in government revenue.
The benefits of reducing fossil fuel dependence are also reflected in improvements in air quality. The 2025 Lancet Countdown report estimated that reductions in coal-related outdoor air pollution between 2010 and 2022 helped avoid approximately 160,000 premature deaths annually.
However, the transition must also address unequal access to energy. The declaration notes that approximately 750 million people lacked access to electricity in 2023. For communities dependent on traditional biomass fuels, access to clean electricity and cooking technologies remains essential to reducing household air pollution. Off-grid solar systems and mini-grids are identified as potential solutions for underserved populations.
Healthcare systems must also reduce emissions
An important aspect of the declaration is its recognition that healthcare systems themselves contribute to climate change. The document estimates that the healthcare sector accounts for approximately 5% of global carbon emissions, reflecting its dependence on energy-intensive infrastructure, pharmaceutical manufacturing and supply chains.
It calls for healthcare institutions to lead by example through energy-efficient hospital buildings, sustainable waste management and low-carbon pharmaceutical manufacturing. Healthcare systems also have considerable purchasing power, which could help create demand for cleaner technologies.
Representative image.Image credit:Unsplash
The declaration encourages countries to incorporate health considerations into their Nationally Determined Contributions (NDCs) and National Adaptation Plans (NAPs). It also calls on the WHO to provide technical assistance and coordinate international efforts towards a just and orderly energy transition.
From commitments to implementation
The initiative builds on momentum from COP30, where around 90 countries expressed support for a roadmap to transition away from fossil fuels. It also follows the first international conference on transitioning away from fossil fuels, co-organised by Colombia and the Netherlands in April 2026.
The declaration identifies three ways health ministries can influence the transition: raising public awareness about the health costs of fossil fuels, using the healthcare sector’s purchasing power to promote cleaner technologies, and working with other ministries to align climate and health policies.
However, translating these commitments into measurable outcomes remains a challenge. The declaration acknowledges differences in national capacities, development priorities and energy security requirements, particularly among least developed countries and small island developing states.
It does not establish binding emissions targets, dedicated funding commitments or country-specific implementation deadlines. Its effectiveness will therefore depend on whether governments translate its recommendations into national policies and allocate resources for implementation.
As countries are negotiating at COP31 and looking forwards to the 80th World Health Assembly in May 2027, the declaration seeks to strengthen the connection between climate action and public health. Its central argument is that cleaner energy is not simply about reducing carbon emissions; it is also about preventing avoidable deaths, reducing health inequalities and building more resilient healthcare systems.
Energy
India’s renewable energy boom faces a growing challenge as power grids struggle to absorb clean electricity
India’s renewable energy expansion is facing a growing challenge as grid constraints and limited power storage lead to clean electricity curtailment. New research highlights the need for stronger transmission infrastructure, battery storage and greater flexibility in coal-fired power generation.
India’s rapid expansion of solar and wind energy is creating a new challenge for its electricity sector: ensuring that the power generated from renewable sources can be absorbed and supplied when needed. A growing volume of clean electricity is being curtailed because of grid constraints and the operational limitations of coal-fired power plants, raising questions about whether the country’s electricity infrastructure can keep pace with its energy transition.
An analysis published by energy think tank Ember on June 17, 2026, estimates that India curtailed approximately 2.1 terawatt-hours (TWh) of renewable electricity during the financial year 2025–26 because coal-fired power plants had to maintain their minimum technical operating levels. This represents around 1.3% of total renewable electricity generation and an estimated ₹629 crore worth of foregone electricity.
The report, titled Bottleneck to the Next Phase of Renewable Energy Growth in India, identifies the limited operational flexibility of coal-based power plants as a significant obstacle to integrating additional renewable electricity into the grid. It estimates that around 10 gigawatt-hours (GWh) of battery storage capacity is immediately needed to prevent this form of renewable energy curtailment.
The findings highlight a growing mismatch between India’s expanding renewable energy capacity and the flexibility of its existing electricity infrastructure.
Coal dependence and grid constraints complicate the energy transition
Solar power generation is concentrated during daylight hours, particularly around midday, while electricity demand often remains high after sunset. Coal-fired power plants, which continue to provide a substantial share of India’s electricity, cannot always reduce their output sufficiently during periods of high solar generation without affecting their stable operation.
Coal plants have minimum technical load requirements, below which they cannot operate safely and reliably. When these plants reach their operating limits, grid operators may have to reduce renewable electricity generation to maintain the balance between electricity supply and demand.
Ember’s analysis found that coal plants were operating at or below their minimum technical load in more than half of midday dispatch intervals in April 2026. During the same month, renewable energy curtailment accounted for 37% of down-regulation, compared with almost zero a year earlier.
More recent findings from the Centre for Research on Energy and Clean Air (CREA) indicate that the problem extends beyond coal-related operational constraints.
Its Quarterly Energy Snapshot for India: Q2 2026–27, published on October 12, estimates that approximately 1,835 million units of renewable electricity were curtailed during July and August 2026 because of grid and operational constraints. Of this, 1,462 million units came from solar generation and 373 million units from wind.
The report also records India’s peak electricity demand reaching 270 GW on July 16, 2026, an 18% increase from the corresponding quarter of the previous financial year. Coal and lignite continued to account for approximately 66% of electricity generation during the quarter, supplying 351 billion units.
These figures illustrate the difficulty of balancing increasing renewable generation with a power system that continues to depend heavily on conventional sources.
Energy storage emerges as a critical solution
Energy storage systems could help address this mismatch by storing surplus solar and wind electricity when generation is high and releasing it when demand increases or renewable output declines.
Battery energy storage systems (BESS) can respond quickly to fluctuations in electricity supply and demand. Pumped-storage hydropower offers another option, using surplus electricity to pump water to an elevated reservoir and generating power when it is released through turbines.
A 2026 report by the Rocky Mountain Institute (RMI), titled Catalysing Energy Storage in India: From Procurement to Reliable Power, estimates that India will require at least 60 GW of grid energy storage capacity by 2030. This includes 42 GW, equivalent to 208 GWh, of battery energy storage systems.
According to CREA, approximately 9.1 GWh of battery storage capacity was operational in India as of its Q2 2026–27 assessment. Although tenders for nearly 290 GWh of storage capacity had been issued by August 2026, the gap between planned and operational infrastructure remains substantial.
The International Energy Agency’s (IEA) India Renewable Energy Market Report 2026, released on November 3, also identifies faster investment in electricity grids and energy storage as essential to sustaining renewable energy expansion.
The report notes that India’s renewable power capacity has surpassed 300 GW in 2026, almost quadrupling over the past decade. It projects that capacity could reach approximately 530 GW by 2030, with solar photovoltaic technology accounting for more than 80% of new additions.
The IEA also warns that faster transmission development, improved forecasting, energy storage and greater flexibility in electricity generation will be necessary to integrate increasing volumes of variable renewable power.
India’s renewable energy expansion has already delivered significant energy security benefits. According to the IEA, renewable electricity helped the country avoid more than $100 billion in cumulative coal and natural gas import expenditure between 2011 and 2025.
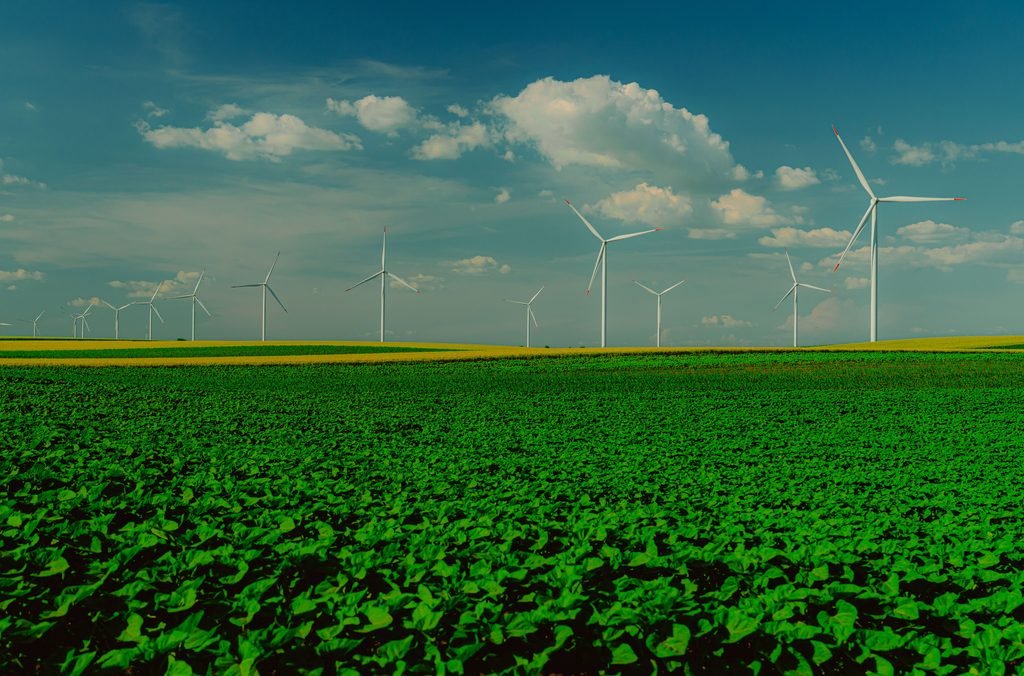
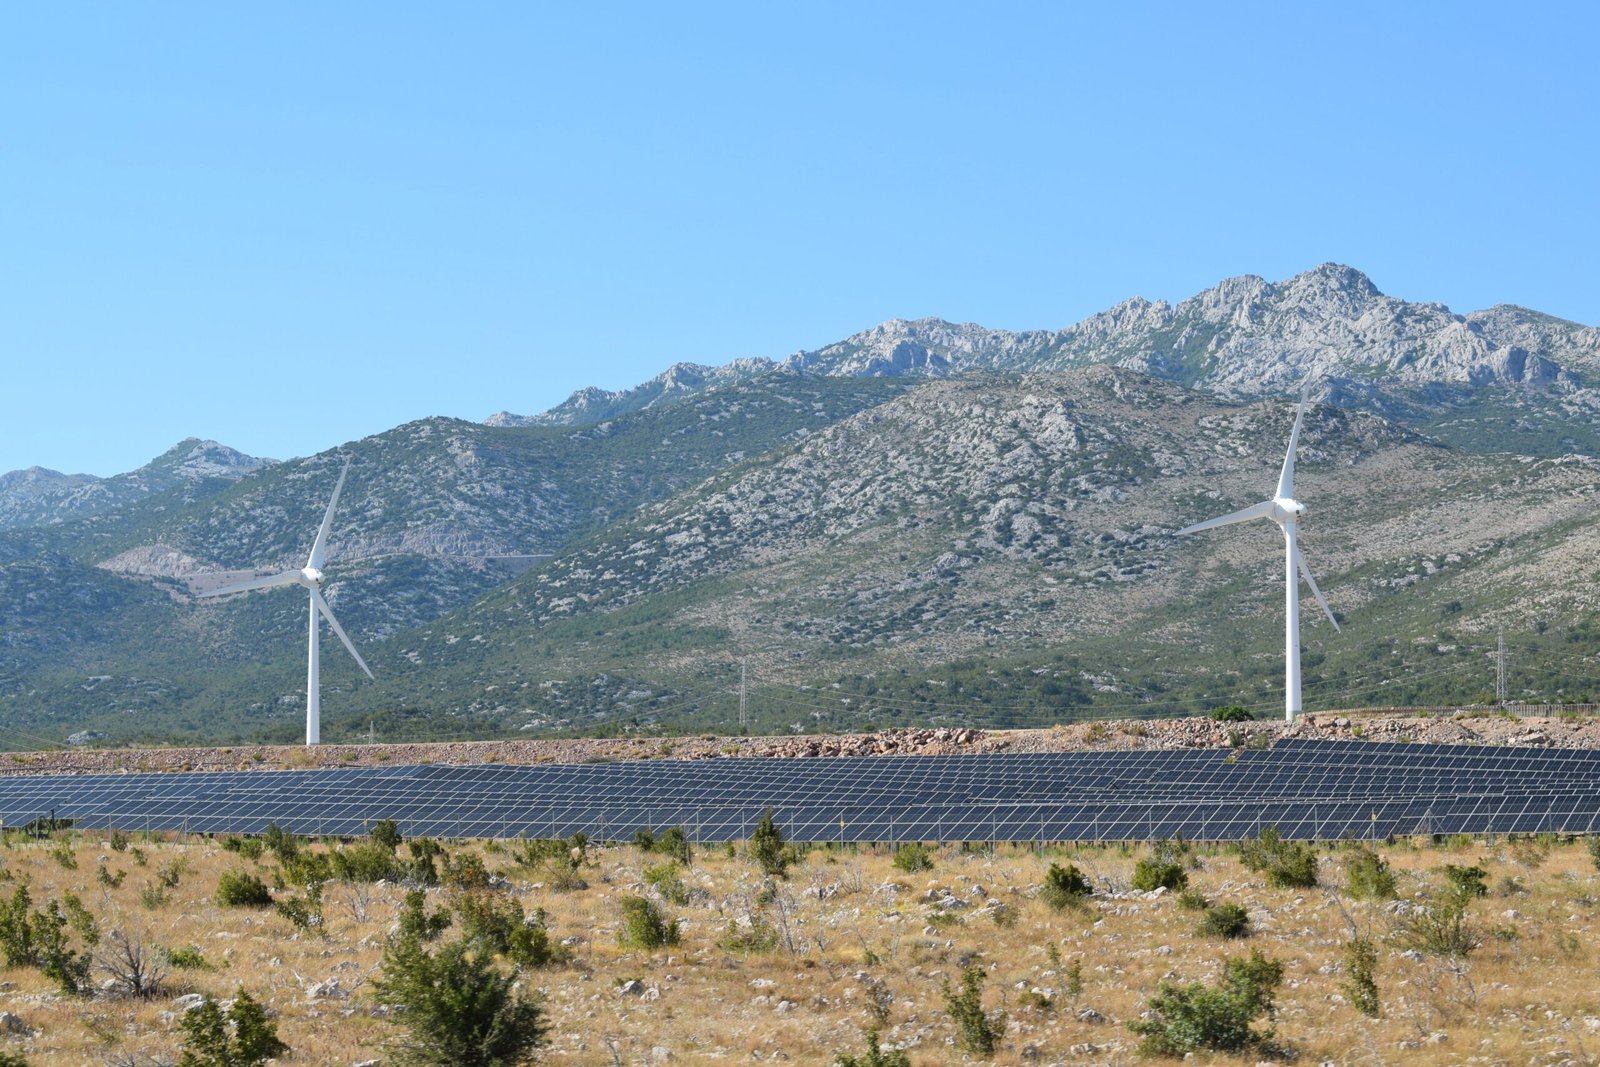
A vast field of wind turbines.Image credit:Pexels
However, the growing incidence of renewable electricity curtailment highlights the need to strengthen the infrastructure supporting this transition. Expanding generation capacity alone will not ensure that clean electricity reaches consumers when it is needed.
As India moves towards its 2030 renewable energy targets, investments in storage, transmission networks and more flexible power generation will be critical to reducing electricity losses and making its transition away from fossil fuels more effective.
Energy
The Global Race for Critical Minerals: Where Does India Stand?
As countries negotiate access to lithium, cobalt, nickel and other critical minerals, India is expanding its international partnerships and domestic processing capacity. An IISD analysis of 211 agreements reveals how the global race is evolving and where India stands.
Lithium from Argentina, cobalt from the Democratic Republic of the Congo and nickel from Indonesia are becoming increasingly important to countries investing in electric vehicles, battery manufacturing and renewable energy. But access to these resources is uneven. Some countries hold these critical minerals’ reserves, while others have the industries and technology needed to process them.
India sits on the demand side of this equation. Its plans to expand electric mobility, renewable energy and domestic manufacturing will require reliable supplies of minerals that it does not produce in sufficient quantities. Securing these resources has therefore become an important part of its industrial and energy strategy.
This is part of a wider shift in international trade. An analysis by the International Institute for Sustainable Development (IISD), covering 211 trade and economic agreements signed between January 2025 and September 2026, found that 139 contained provisions related to critical raw materials. India was among the most active countries, with 15 such agreements. The findings offer a glimpse of how countries are competing for mineral supplies—and where India stands in that contest.
Why Countries are Negotiating Over Minerals
Critical minerals are not distributed evenly across the world. Some countries possess substantial mineral reserves, while others have developed the industrial capacity to refine them and manufacture finished products. This geographical imbalance has created a complex international supply chain. A country may have the mineral resources needed for battery production but lack the technology and infrastructure to process them. Another may have advanced manufacturing industries but depend on imports for the raw materials.
China, for instance, occupies an important position in the global critical mineral industry, particularly in processing and refining. Its influence over several mineral supply chains, along with restrictions on certain rare earth exports and magnets, has raised concerns among countries dependent on these materials.
The United States, European Union, India and Japan are among those seeking to diversify their sources of supply and reduce vulnerabilities in their supply chains. This has brought critical minerals into international trade negotiations, a development commonly described as mineral diplomacy. Through bilateral agreements, memoranda of understanding and wider economic partnerships, governments are negotiating access to mineral resources, investment in mining and processing, and cooperation on supply chains.
The scale of this shift is evident in a recent analysis by the International Institute for Sustainable Development (IISD). Its Trade & Climate Tracker mapped 211 trade and economic agreements signed between January 2025 and September 15, 2026. Of these, 139, or approximately two-thirds, contained provisions related to critical raw materials. The agreements involved 79 countries and blocs. The United States accounted for 41 critical mineral-related agreements, followed by India with 15. China, Canada, Saudi Arabia and the European Union had 11 each, while Japan and the United Arab Emirates had 10 apiece. The findings indicate how mineral access has become a significant part of economic diplomacy, with both resource-consuming and resource-producing countries seeking to strengthen their positions.
Mineral-producing Countries Seek a Larger Share of the Value
The changing nature of mineral diplomacy is also giving resource-rich countries greater bargaining power. Rather than remaining suppliers of raw materials, several governments are using trade policies to encourage companies to establish processing and manufacturing facilities within their borders.
Indonesia offers a prominent example. The country has restricted exports of unprocessed nickel to encourage investment in domestic smelting and processing. The policy was intended to move the country further up the industrial value chain, allowing it to export processed nickel products rather than relying primarily on raw ore exports. The strategy has attracted substantial investment in nickel processing, although the resulting industrial expansion has also raised questions about the environmental costs of mining and processing.
The Democratic Republic of the Congo (DRC), which accounts for a major share of global cobalt production, has also tightened control over mineral exports. In February 2025, it suspended cobalt exports and subsequently introduced an export quota system. The restrictions have been used to regulate supply and stabilise the cobalt market, while forming part of wider efforts to exercise greater control over the country’s mineral resources.
Zimbabwe has taken a similar approach to lithium. It prohibited exports of unprocessed lithium-bearing ore in December 2022 to encourage domestic processing. In June 2025, its government also announced plans to prohibit exports of lithium concentrates from January 2027, allowing exports of more processed products instead. These policies reflect a wider shift in how mineral-producing countries approach international trade. Their objective is to attract investment in domestic industries, create employment and retain a greater share of the economic value generated from their natural resources.
However, restricting exports does not automatically create a strong domestic manufacturing industry. The OECD‘s 2025 analysis of export restrictions on cobalt, lithium and nickel found that the benefits of these policies depend on investment conditions and domestic industrial capacity. In some cases, value addition remained concentrated in early processing stages or accrued substantially to foreign investors.
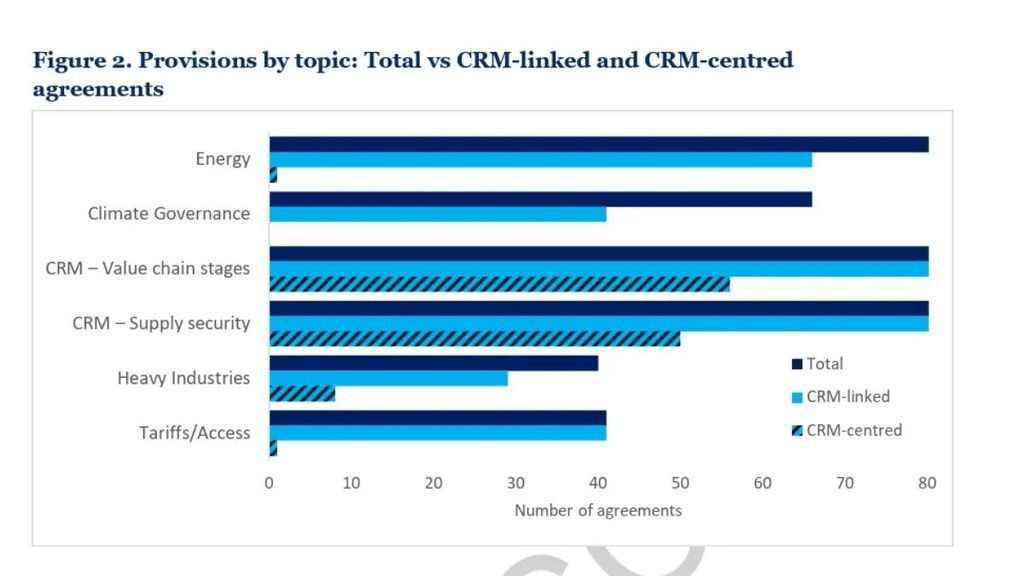
The IISD analysis similarly found that 84 of the 139 critical mineral-related agreements contained provisions intended to develop value chains in producing countries, including local processing, exploration and skills development. Supply-security provisions appeared in 94 agreements. This suggests that negotiations increasingly involve both sides of the mineral trade: consumers seeking dependable supplies and producers seeking opportunities to develop their own industries.
India’s Strategy: Securing Minerals From borders
India is also positioning itself in this changing mineral landscape. The country has identified 30 minerals as critical to its economic development and strategic requirements. These include lithium, cobalt, nickel, graphite, copper, gallium, germanium and rare earth elements. Their importance is closely linked to India’s plans for electric mobility, battery manufacturing, renewable energy, electronics and advanced technologies.
One challenge is that India remains dependent on imports for several critical minerals and their processed forms. Limited domestic availability, alongside inadequate processing capacity, makes the country vulnerable to disruptions in international supply chains.
The government has introduced several measures to address these gaps. The National Critical Mineral Mission (NCMM), approved in January 2025, has an expenditure outlay of 16,300 crore rupees, with an expected investment of 18,000 crore rupees from public sector enterprises and other stakeholders over seven years. It covers exploration, mining, processing, recycling and the acquisition of mineral assets overseas.
Overseas partnerships form an important part of this strategy. Khanij Bidesh India Ltd (KABIL), a joint venture of three public sector companies under the Ministry of Mines, has entered into an agreement with Argentina’s state-owned CAMYEN to explore and develop five lithium brine blocks covering approximately 15,703 hectares in the Catamarca province. Argentina is part of the Lithium Triangle, along with Chile and Bolivia, a region holding a substantial share of the world’s lithium resources.
India has also signed an agreement with Australia’s Critical Mineral Facilitation Office to undertake joint due diligence and explore potential investments in lithium and cobalt assets. These partnerships are intended to diversify India’s sources of supply and reduce its dependence on a limited number of suppliers. Securing overseas resources, however, addresses only part of the problem. India also needs the capacity to process these minerals into materials that domestic manufacturers can use.
A recent policy announcement reflects this concern. On November 4, 2026, the Union Cabinet approved a 2,814-crore rupees capital support scheme to promote domestic processing of lithium and nickel. The five-year scheme will support the establishment of four processing plants, two each for lithium and nickel. Cobalt is also expected to be recovered as a by-product of nickel processing. The government will provide a capital subsidy of 30% of eligible investment.
The initiative is intended to address the limited domestic capacity to process critical minerals and produce high-purity materials. It also reflects a broader policy objective: ensuring that access to raw materials translates into industrial capabilities within India. The IISD data provides an indication of India’s growing engagement in this area. With 15 critical mineral-related agreements between January 2025 and September 2026, India was the second most active country in the Tracker after the United States.
The Missing Link: Critical Minerals and Climate Action
The growing demand for critical minerals is closely connected to the global energy transition. However, the agreements securing access to these resources do not necessarily address the environmental consequences of extracting and processing them. Mining can involve land-use changes, water consumption and pollution, while mineral processing can require substantial amounts of energy. If processing relies heavily on fossil fuels, the production of materials needed for clean energy technologies can itself generate significant emissions.
This creates a policy challenge. Countries need more critical minerals to manufacture batteries, electric vehicles and renewable energy equipment, but the expansion of mining and processing also needs environmental safeguards. The IISD analysis identifies a gap in this area. Of the 60 agreements specifically centred on critical minerals, only one included additional energy provisions, while eight addressed cooperation related to heavy industries. None addressed broader climate governance, including issues such as emissions reduction, climate finance and a just transition.
Governments are increasingly negotiating access to minerals needed for the energy transition, yet the agreements rarely establish how mining and processing should align with climate objectives. For India, this issue will become increasingly relevant as the country expands domestic mineral exploration and processing. Building a secure supply chain will require more than identifying mineral deposits or acquiring overseas assets. It will also involve developing cleaner processing technologies, strengthening recycling systems and ensuring that mining does not impose disproportionate environmental costs on local communities.
The IISD recommends that future agreements go beyond supply security and include commitments to reduce emissions from mining and processing, provide transition finance and develop skills in mineral-producing regions. It also calls for greater transparency, noting that 39% of critical mineral-related agreements in its Tracker are not publicly available. The expansion of mineral diplomacy presents an opportunity for resource-rich countries to develop industries and for importing countries to build more resilient supply chains. But whether this cooperation contributes to a fairer energy transition will depend on how its economic benefits and environmental responsibilities are shared.
The scale of these agreements will ultimately depend on whether they create lasting industrial opportunities for producing countries, strengthen supply chains without increasing environmental damage and contribute to the climate goals that made these minerals important in the first place. The challenge for India and other countries is to ensure that the race for critical minerals does not leave sustainability behind.

India’s Farm Subsidies Fail to Offset Price Pressures on Farmers, OECD Report Finds

As India’s Space Economy Opens Up, Can Private Investment Deliver Public Value?

Fossil Fuels Linked to Millions of Premature Deaths as Ministers Call for Healthy Energy Transition

Kerala’s Pink Water Lily Paradise is in an Ecological Question

Intellectual disabilities linked to severe educational disadvantage in India, study finds

Indian universities lead Asia in research output per faculty, but the country’s top six all slip in QS ranking

Why Delhi’s Geography Makes It Vulnerable to Severe Air Pollution

Europe Braces for Extremes as Commission Unveils Climate Resilience Framework

NASA recruits new astronauts for future Moon Base and Mars missions

Between Lectures and Lyrics: Kabeer Is Building a Malayalam Hip-Hop Career One Self-Taught Skill at a Time
-

 Math4 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
EP Deep Dive: Data & Solutions4 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
EP Deep Dive: Data & Solutions4 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics6 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews2 months ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate & Environment6 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society4 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society5 months ago
From Bell Labs to the Classroom: A Second Career in Teaching