Connect with us

Sustainability

Smarter AI, Lower Power Bills? Study Says Flexible Data Centers Could Cut Energy Costs

A new MIT study finds flexible data center energy use could reduce electricity costs, ease pressure on power grids and reshape AI’s energy footprint.

Published

on

A new MIT study finds flexible data center energy use could reduce electricity costs, ease pressure on power grids and reshape AI's energy footprint.
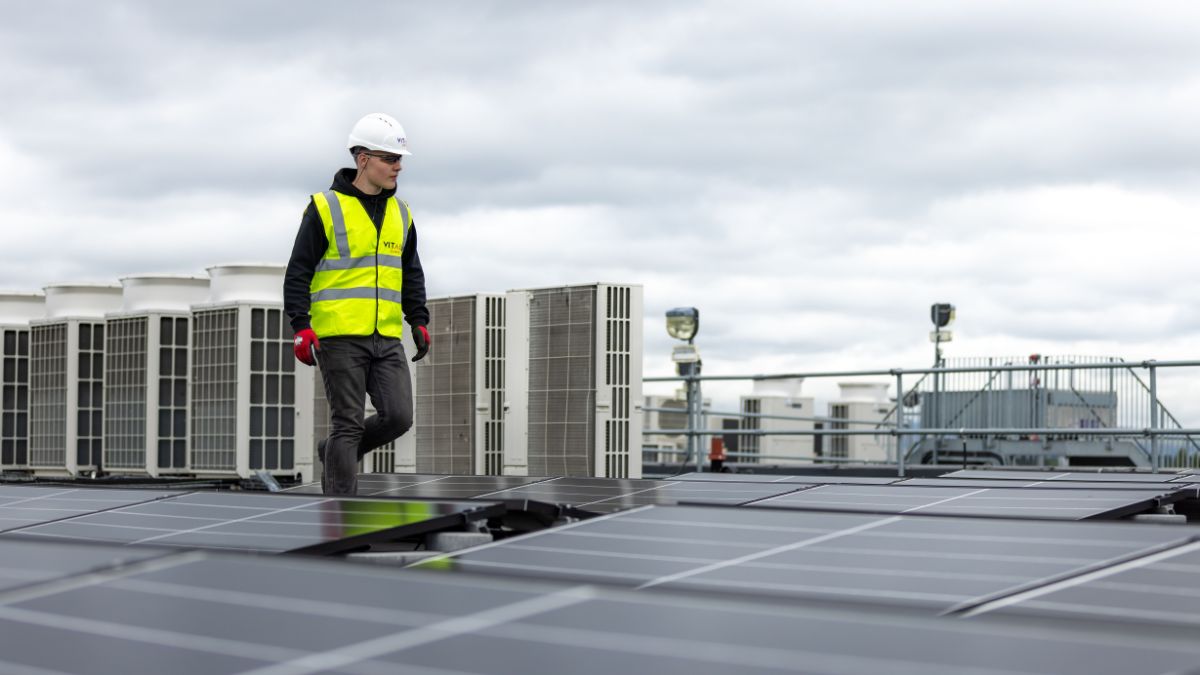
Image credit: ThisIsEngineering/Pexels

Data center energy use could become cheaper and more efficient if AI facilities shift electricity consumption to off-peak hours, according to a new MIT study that highlights both economic and environmental trade-offs.

As artificial intelligence fuels a rapid expansion of data centres around the world, concerns are growing over how much electricity these facilities will consume—and whether power grids can keep up.

A new study by researchers at the Massachusetts Institute of Technology (MIT) suggests there may be a way to ease the pressure. Rather than consuming electricity around the clock at fixed rates, data centres could shift a significant portion of their energy use to off-peak hours, lowering electricity costs while making better use of existing grid capacity.

The findings, published in the journal iScience, indicate that if data centres adopt more flexible electricity consumption patterns, average power system costs could fall by as much as 5 per cent in Texas, 4 per cent in the Mid-Atlantic region and 2 per cent across western U.S. states.

Data Center Energy Use: Flexible Data Centers Could Reduce Energy Costs

The researchers modelled how expanding data centres would affect electricity grids in three regions that are expected to host about 82 per cent of U.S. data centres by 2030: Texas, the Mid-Atlantic and the Western Interconnect, which covers 11 western states.

Their simulations found that shifting at least one-fifth of a data centre’s electricity use away from peak-demand periods could reduce overall system costs. In some cases, as much as half of a facility’s energy demand would need to be moved to quieter periods of the day.

“The key with data centers is: How can we add them to the network without adding a lot to our peak usage?” said Christopher Knittel, economist at the MIT Sloan School of Management and co-author of the study, in a media statement.

“One way for data centers to do that — to add to average usage but not the peak usage — is if they provide some grid flexibility during those high-cost periods. And that’s what we’ve been interested in understanding.”

The researchers note that most data centres already have some operational flexibility because they typically run below full capacity. Instead of carrying out energy-intensive computing tasks during periods of peak electricity demand, many could shift those operations to midday, when solar power generation is often highest and overall demand is lower.

AI Growth Is Putting Pressure on Power Grids

The rapid expansion of AI has dramatically increased demand for computing infrastructure, raising questions about whether electricity grids can support hundreds of new data centres without driving up costs or emissions.

The study suggests that adding more data centres does not automatically translate into higher electricity prices. Because much of the cost of running a power grid comes from fixed infrastructure such as transmission lines, increasing electricity use can spread those costs across a larger customer base—provided peak demand does not rise at the same pace.

“It’s really just math,” Knittel said.

“There are two dimensions that data centers have to make decisions about. One is how much of their load in any one time period is flexible. And two, how many hours, plus or minus, can they move that computation?”

Flexible Data Centers May Have Different Climate Impacts

The environmental picture is more complex.

The researchers found that the projected growth in data centres by 2030 could significantly increase carbon dioxide emissions if electricity demand is met through fossil fuels. Compared with a scenario without new data centres, emissions could rise by 58 per cent in Texas, 20 per cent in the Mid-Atlantic region and 24 per cent in the western United States.

However, the impact varies depending on how regional electricity systems generate power.

In Texas, where wind energy accounts for a large share of electricity generation, shifting data-centre operations to times when renewable energy is abundant could reduce carbon emissions by as much as 40 per cent.

In contrast, the Mid-Atlantic region presents a different picture. There, flexible electricity use could unintentionally keep coal-fired power plants operating for longer periods.

“When data centers provide some flexibility in that latter scenario, the data centers actually move hours to when sun and wind energy production is slowing, and that allows a coal plant to stay on,” Knittel observed. “So it doesn’t necessarily attract more renewable investment. It attracts more coal investment.”

Policy Could Shape the Future of AI Infrastructure

The researchers argue that flexibility alone is unlikely to become common unless governments and grid operators create incentives for companies.

“That’s why we have policy,” Knittel said.

One option would be to allow data centres that agree to flexible electricity use to connect to the grid sooner.

“One big concern about these data centers now is how long it takes for them to connect to the grid,” Knittel said. “One way to provide flexibility now is what’s called ‘connect and manage,’ which is, connecting you faster to the grid if you agree to provide flexibility. Tech firms would take that deal. They would rather connect a year earlier, and throttle down computation a few hours a day, than to have to wait. We do this with power plants too.”

He added that industry-wide rules would help address competitive concerns.

“Tech companies say they won’t provide flexibility alone. But if everyone in the industry has to, it’s okay.”

Balancing AI Growth With Sustainable Energy

As governments and technology companies race to build the computing infrastructure needed for the AI era, the study suggests that when data centres consume electricity may prove to be as important as how much they consume.

The researchers conclude that smarter scheduling of electricity demand, combined with supportive public policy, could lower power system costs while reducing pressure on electricity grids. At the same time, the study highlights that the environmental benefits of flexible energy use will depend on how individual regions generate electricity, reinforcing the need for location-specific energy planning.

EP Staff is the editorial team at EdPublica, an independent media organisation focused on science, education, environment and public policy. The team produces evidence-based news, features, explainers and analysis on issues that shape society and everyday life.

Sustainability

India Captures 5.7% of Global Greenfield Investment, Outpacing China

India accounted for 5.7% of global greenfield investment between 2020 and 2025, more than double China’s share. UNCTAD data highlight the concentration of investment in AI infrastructure, semiconductors and energy-transition technologies.
Published

on

Greenfield investment: Solar Farm and Global Greenfield Investment
Energy-transition technologies accounted for 7.8% of global greenfield investment between 2020 and 2025, according to UNCTAD data. Representational image. Image credit: Charl Durand/ Pexels

India accounted for 5.7% of global greenfield investment between 2020 and 2025, more than twice China’s 2.8% share, even as investment in strategically important industries remained concentrated in Europe and North America. The figures highlight India’s position as a major destination for new investment while exposing the wider challenge facing developing economies seeking a larger role in emerging technology and energy supply chains.

The findings, reported in the United Nations Conference on Trade and Development (UNCTAD)’s latest investment analysis, come amid a shift in global capital towards artificial intelligence (AI) infrastructure, semiconductors and energy-transition technologies. These sectors accounted for 44% of global greenfield investment in 2025, compared with 16% in 2020. UNCTAD’s July 2026 analysis identifies the shift as a significant change in the direction of international investment.

India Leads Among the Listed Asian Economies

India accounted for the largest share of global greenfield investment among the Asian economies listed in the report, followed by Malaysia at 4%, Indonesia at 3.8% and China at 2.8%.

Greenfield investment involves establishing new operations in another country, such as a factory, data centre or manufacturing facility. Unlike an acquisition, which transfers ownership of an existing business, a greenfield project can create new productive capacity, although its effects on jobs, domestic suppliers and technology transfer depend on how the project is developed.

India’s 5.7% share is therefore a measure of its participation in new investment projects, rather than a direct measure of jobs created, technology acquired or investment actually realised. Announced project values and completed investments can differ.

AI Infrastructure Attracts the Largest Share

The changing composition of investment is as significant as its geographical distribution. According to the figures cited in the report, global greenfield investment totalled $845.7 billion over 2020–2025. AI infrastructure and related technologies attracted the largest share, at 12.4%, followed by the semiconductor value chain at 8.1% and energy-transition technologies and services at 7.8%.

The shift reflects the capital requirements of the digital economy, from data centres and computing infrastructure to the chips that power AI systems. Energy-transition technologies represent another strategically important area as economies invest in technologies and services associated with changing energy systems.

These industries can shape future manufacturing capacity, technology development and supply-chain relationships. Attracting investment into them can offer host countries opportunities to build industrial capabilities, but the benefits depend on whether domestic businesses, workers and research institutions become part of the value chain.

Europe and North America Retain Their Advantage

Despite the growing participation of Asian economies, strategic investment remains concentrated in a limited number of regions. Europe accounted for 28.4% of strategic investment during 2020–2025, while North America captured another 28%, according to the reported figures. Developing Asia accounted for 26.5% among developing economies, with China, India, Indonesia, Malaysia and Singapore identified as leading destinations for new investment.

The distribution points to an important distinction: a country can attract a substantial share of new investment without having equal access to the industries commanding the greatest strategic importance. Strategic projects often require substantial capital, reliable energy and digital infrastructure, specialised skills and established supplier networks. Economies with these capabilities can offer investors advantages that are difficult for less industrialised countries to replicate quickly.

For developing countries, the challenge is not simply to attract foreign capital, but to secure investment in activities that strengthen domestic productive capacity and connect local businesses to international supply chains.

Industrial Policy Shapes Investment Competition

India’s record of industrial policymaking provides another part of the picture. The report’s figures show that India implemented 1,416 industrial policies between 2008 and 2021, compared with 4,201 in China and 4,025 in the United States. The figures place India among the countries that have used industrial policy extensively over the period.

Industrial policies can include incentives, subsidies, domestic manufacturing programmes and measures intended to develop particular industries. Governments use them to influence where companies invest, which technologies are developed and how domestic producers participate in global markets.

However, the number of policies alone does not establish their effectiveness. Their impact depends on implementation, the industries targeted, the resources committed and whether the measures lead to lasting improvements in productivity, technological capability and employment.

Wider Challenge for the Global South

UNCTAD’s central concern is that the shift towards strategic industries could deepen existing investment inequalities. Its July 2026 analysis found that low-income and lower-middle-income economies attracted only about 10% of global greenfield investment in strategic sectors between 2020 and 2025, compared with more than 20% in other sectors. The gap suggests that the industries attracting increasing amounts of capital are not necessarily opening opportunities evenly across the developing world.

For India, the 5.7% share offers evidence of its place in the global investment landscape. The next question is how effectively the country can translate new projects into stronger domestic supply chains, skilled employment and technological capacity, particularly in sectors such as semiconductors, AI infrastructure and energy-transition technologies.

For other developing economies, the concentration of investment presents a more fundamental concern: without the infrastructure, financing and skills required to compete, they risk remaining on the margins of industries that will shape future production and trade.

The distribution of greenfield investment will therefore matter beyond headline investment shares. It will help determine which economies build the productive capabilities needed to participate in the next phase of industrial development.

Continue Reading

Sustainability

The Climate Problem Hiding in Your Kitchen Bin

Food waste sent to landfills can generate methane as it decomposes without oxygen, adding to greenhouse gas emissions and the climate crisis.
Published

on

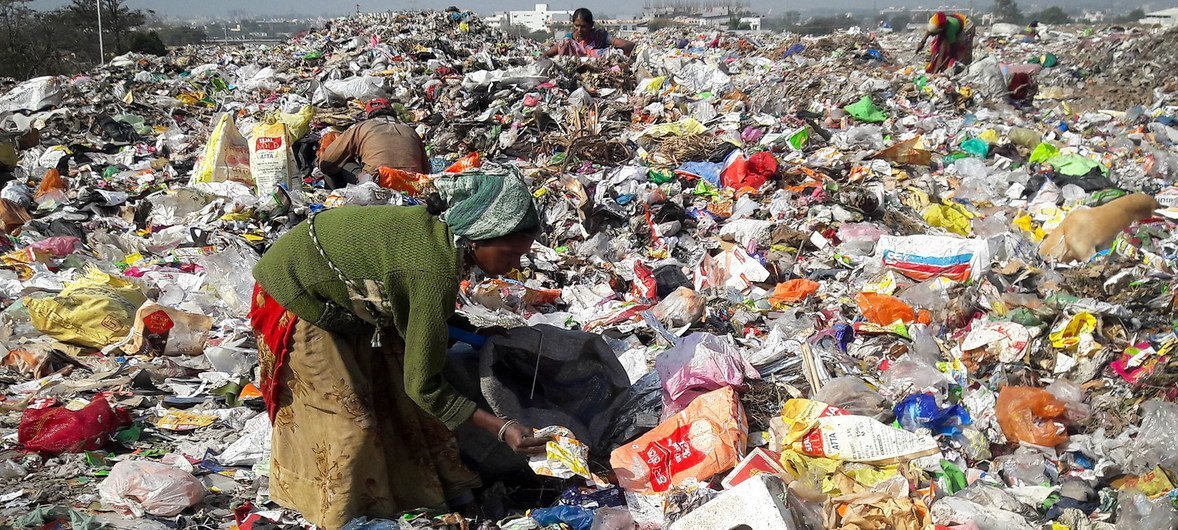
Waste pickers sorting through a large landfill filled with discarded plastic and other waste.
Waste pickers sort through discarded materials at a landfill. Food waste buried in landfills can release methane as it decomposes in oxygen-deprived conditions.Image Credit:UNDP

Every day, more than one billion meals go uneaten around the world. What appears to be a problem of excess food, poor planning or household waste is also becoming a climate problem, as discarded food can generate methane when it decomposes in landfills.

Global food waste reached an estimated 1.05 billion tonnes in 2022, accounting for nearly one-fifth of all food available to consumers at the retail, food service and household levels, according to the United Nations Environment Programme (UNEP) Food Waste Index Report 2024.

Households accounted for about 60 per cent of this waste, highlighting how everyday food consumption is closely connected to the global climate challenge.

How wasted food becomes a climate problem

Food waste becomes particularly problematic when it is sent to landfills. Buried beneath layers of other waste, organic matter decomposes in oxygen-poor conditions. Microorganisms then break it down and release methane.

Methane is a far more powerful heat-trapping gas than carbon dioxide over shorter periods. The UN estimates that methane traps about 86 times more heat than carbon dioxide over a 20-year period.

Landfills are therefore an important source of human-caused methane emissions. In the United States, municipal solid waste landfills are the third-largest source of human-related methane emissions.

The scale of food waste also means that the climate impact begins long before food reaches a landfill. Food that is never eaten still requires land, water, energy and other resources to produce, process, transport and store.

The Food and Agriculture Organization (FAO) estimates that around 1.4 billion hectares of agricultural land ,roughly 28 per cent of the world’s agricultural land is used to produce food that is ultimately lost or wasted.

Food waste can also contribute indirectly to deforestation because agricultural expansion remains a major driver of forest loss. Wasting food therefore means wasting the land and natural resources used to produce it.

Cutting waste could deliver faster climate benefits

The climate implications are significant, but methane’s relatively short atmospheric lifetime also presents an opportunity.

Unlike carbon dioxide, which can remain in the atmosphere for centuries, methane breaks down much faster. Cutting methane emissions can therefore produce climate benefits within decades.

“At a time when the world is searching for practical ways to slow warming quickly, tackling food waste may be one of the most immediate and cost-effective climate solutions available,” said Martin Krause, Director of the Climate Change Division at UNEP.

The Food Waste Breakthrough initiative aims to halve food waste by 2030 and could reduce methane emissions by up to 7 per cent.
food waste
landfill
climate crisis

Food waste represents a major environmental threat .Image credit: Unsplash/Simon Peel

Several countries are already attempting to reduce waste before it reaches landfills. Brazil has introduced national plans focused on reducing food and organic waste, while UNEP is working with authorities, schools, communities and food businesses in Rio de Janeiro to reduce food waste.

In Kenya, a UNEP-supported initiative is recovering surplus food from across the agricultural value chain and redirecting it to early childhood education centres in underserved communities.

What happens to unavoidable food scraps?

Preventing food waste is the most effective way to avoid methane emissions. But food scraps that cannot be prevented can also be managed differently.

When organic waste is separated from other rubbish and composted in oxygen-rich conditions, it does not produce methane in the same way as food buried in an anaerobic landfill environment.

This approach is being promoted in several African countries, where organic material makes up more than half of municipal solid waste. Eleven governments, with support from the UNEP-convened Climate and Clean Air Coalition, have committed to incorporating waste pickers into formal waste-management systems and training them to sort and compost organic waste.

Another emerging approach uses black soldier flies. Their larvae consume organic waste, allowing food scraps to be converted into useful biomass. The approach is already being used in waste-management systems in countries including Uganda and Malawi.

A climate solution hiding in the bin

Global efforts to tackle food waste have gained momentum, but progress remains insufficient. The world is still far from meeting the Sustainable Development Goal of halving per-capita food waste by 2030.

More than 60 countries have also pledged, through the Declaration on Reducing Methane from Organic Waste, to cut waste-sector methane emissions by 30 to 35 per cent below 2020 levels by 2030.

For consumers, the climate connection can begin with something as simple as buying only what is needed, storing food properly and using leftovers.

“Every meal rescued, shared or never wasted is food put to better use. It is also methane avoided,” Krause said.

The message is straightforward: reducing food waste is not only about saving food. It is also about reducing the methane released when that food becomes rubbish and slowing warming in the process.

Continue Reading

Earth

Hunter Valley Coal Mine Gets Approval to Run to 2045. What Does It Mean for Australia’s Climate Transition?

Australia’s Hunter Valley coal mine has been approved to operate until 2045, raising questions about how the extension fits into the country’s transition towards lower emissions and its net-zero target.
Published

on

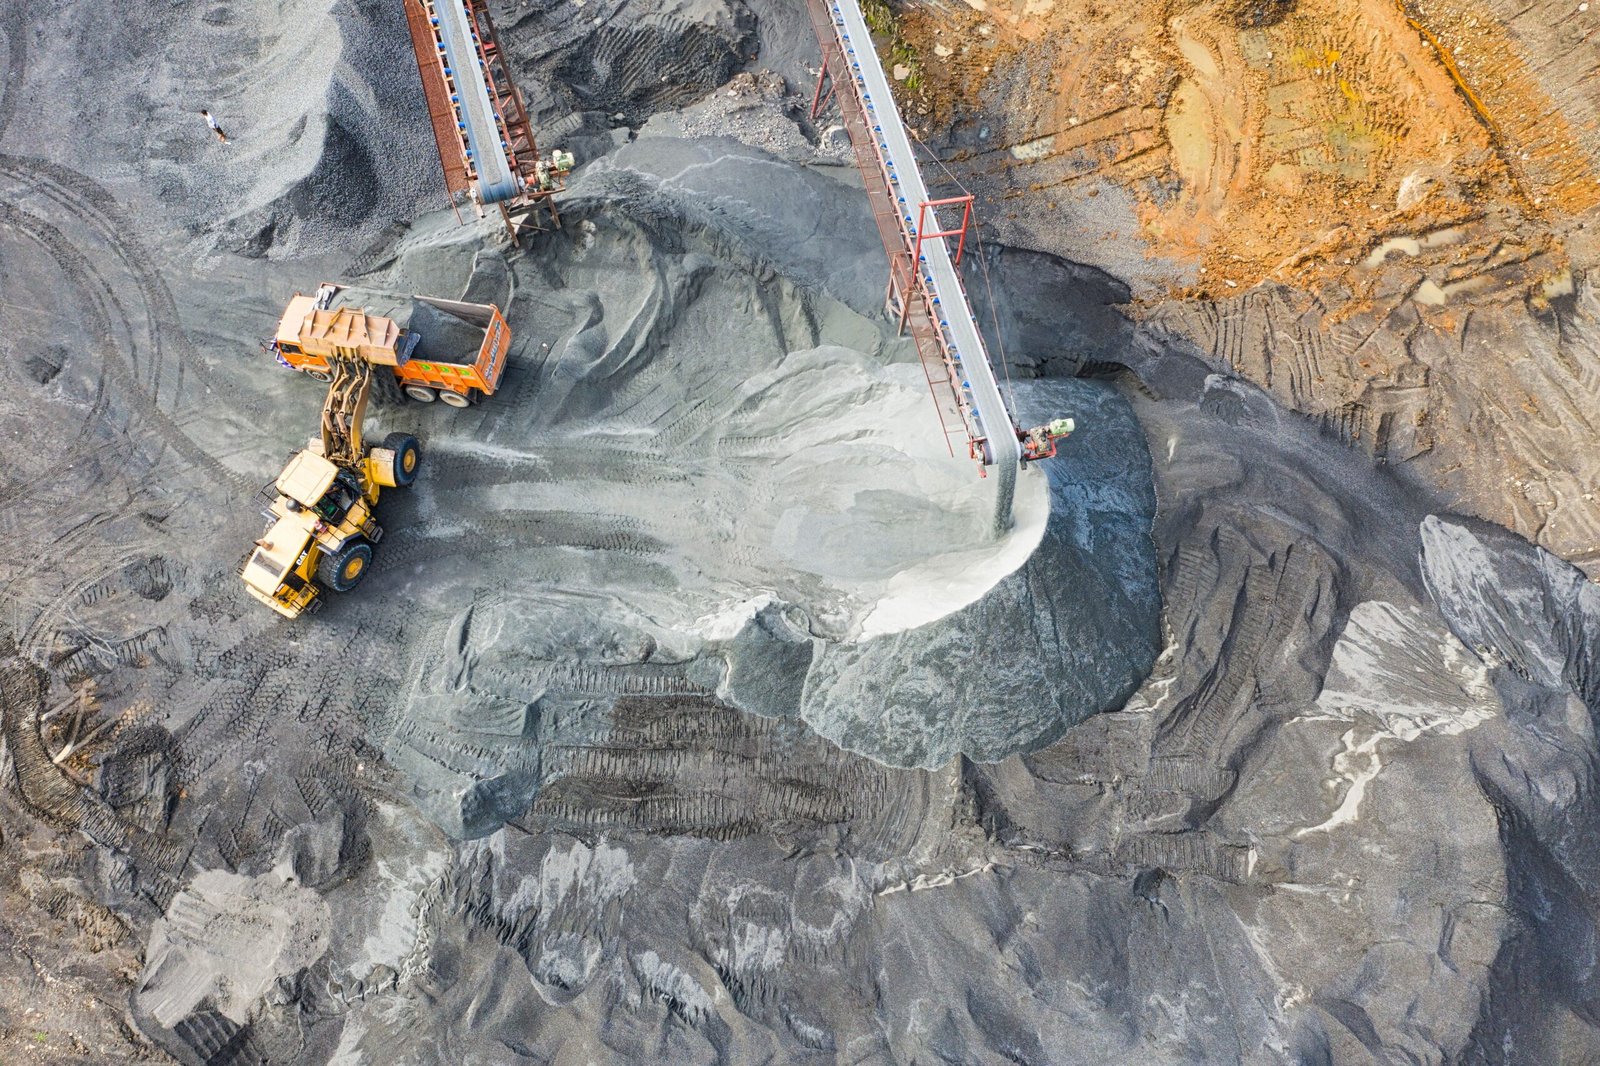
Open-pit coal mine with heavy machinery, conveyor belts and piles of extracted coal.
Heavy machinery and conveyor belts operate at an open-pit coal mine. Representational image. Image credit: Pexels

Australia’s transition away from fossil fuels faces a new test after New South Wales approved the continuation of the Hunter Valley Operations (HVO) coal mine until 2045.

The NSW Independent Planning Commission (IPC) on September 30 approved the continuation of HVO North until the end of 2045 and HVO South until the end of 2042. The project would allow an estimated 429 million tonnes of coal to be extracted from the Hunter Valley near Singleton.

The decision is significant not only because of the scale of the mine, but because it extends a major coal operation into the period in which Australia is committed to sharply reducing its greenhouse-gas emissions.

Australia’s current climate commitments include cutting national emissions by 43 per cent from 2005 levels by 2030 and by 62–70 per cent by 2035, with net-zero emissions targeted for 2050.

The latest government inventory estimates Australia’s emissions at 452.4 million tonnes of carbon dioxide equivalent in the year to June 2026, a preliminary 1.8 per cent decline from the previous year. Emissions in the year to March 2026 were 25 per cent below 2005 levels.

Against that backdrop, the IPC acknowledged that the HVO project would have a substantial climate footprint. Its statement of reasons estimates that the project could result in about 809 million tonnes of greenhouse-gas emissions from local mining operations and the eventual combustion of exported coal overseas. The commission said those emissions would contribute to climate impacts in the Hunter, NSW and globally.

The 809-million-tonne figure needs an important qualification to note. it is a lifecycle-related estimate that includes overseas combustion emissions and should not be interpreted as emissions produced directly by the mine.
pexels braeson holland 3640662 9092830

Coal mine.Representational image.Image credit:Pexels

The economic case for the extension is substantial. HVO employs more than 1,500 people and engages more than 800 suppliers, according to evidence presented to the IPC. The NSW Government says the continuation could secure up to 1,500 ongoing jobs and create about 600 temporary positions through infrastructure upgrades, subject to federal approval.

The approval also comes with conditions intended to address the mine’s emissions and its eventual transition. HVO must prepare a Scope 3 Management Plan dealing with emissions associated with exported coal, maximise renewable electricity use at the mine and purchase additional carbon offsets. It must also prepare a comprehensive closure plan within 12 months, in consultation with local councils and communities, outlining how the mine will transition towards closure while supporting workers and the local economy.

The NSW Government argues that the decision can support regional employment while maintaining the state’s broader emissions-reduction pathway. It says the approved proposal has 43 per cent lower Scope 1 emissions than the company’s 2022 application. NSW’s 2026–50 coal policy also allows extensions of existing mines while ruling out applications for new greenfield coal mines.

At the national level, the federal Safeguard Mechanism is intended to reduce emissions from Australia’s largest industrial facilities. The government says the mechanism is designed to put covered facilities on a trajectory consistent with the country’s 2030 target and net-zero goal.

That creates the central question around HVO’s extension. How does Australia manages the economic and employment role of existing coal regions while reducing emissions over the same period.

The NSW approval does not settle that question. The project still requires approval from the Australian Government under the Environment Protection and Biodiversity Conservation Act.

For the Hunter Valley, the decision provides a longer operating horizon for an established coal industry. For Australia’s climate transition, it brings the challenge of managing an economy in which existing fossil-fuel assets continue operating while national policy seeks progressively sustainable energy and lower emissions.

Continue Reading

Trending