Climate
Japan’s US LNG Trade Leaves Asia With Emissions Equal to 17 Coal Plants
Japan US LNG trade generated lifecycle emissions equal to about 17 coal plants in a year, according to a new analysis, raising concerns about Asia’s growing dependence on imported gas.







Climate
KSBB Workshop Examines Biodiversity, Climate and Environmental Reporting
The Kerala State Biodiversity Board’s three-day media capacity strengthening workshop brought journalists and biodiversity experts together to deepen understanding of Kerala’s rich ecosystems, conservation challenges and the role of informed environmental reporting.
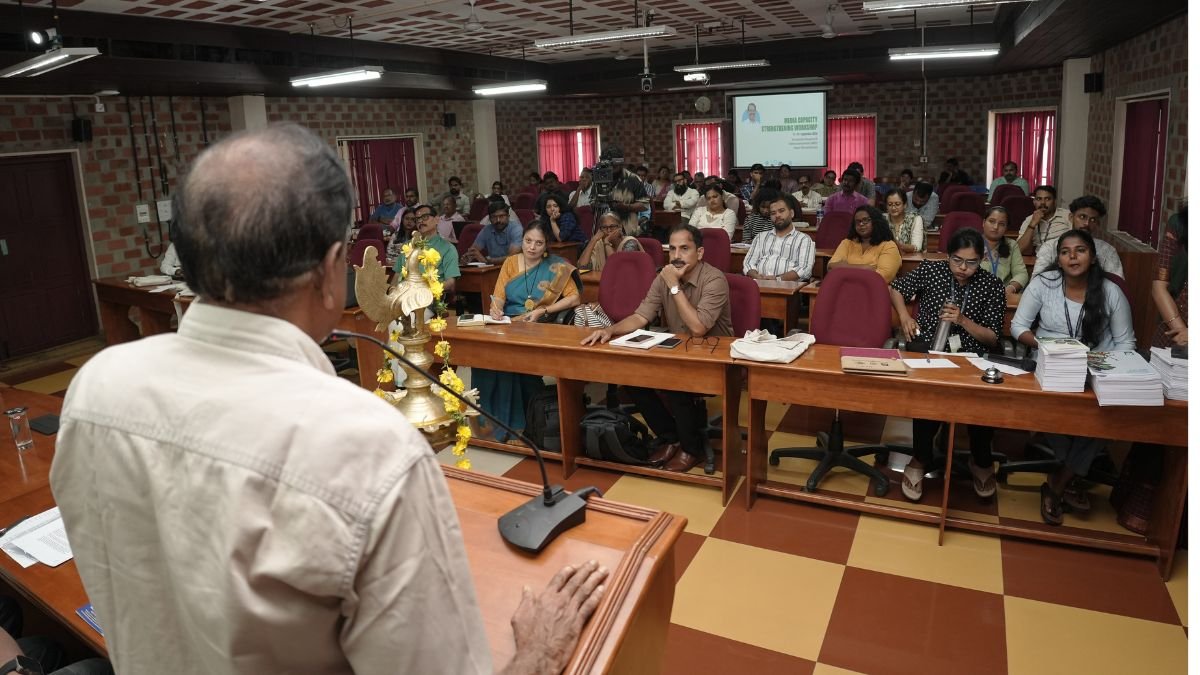
From shrinking paddy fields and an eroding coastline to rising human-wildlife conflict and the spread of invasive species, biodiversity loss in Kerala is increasingly showing up in the places and problems that shape everyday life. Yet much of this remains reported as separate environmental issues.
A three-day workshop by the Kerala State Biodiversity Board (KSBB) sought to bring these connections into sharper focus, bringing journalists together with scientists, biodiversity experts, policymakers and community practitioners to explore how climate and biodiversity stories can be reported with greater scientific depth and local context.
The Media Capacity Strengthening Workshop on Biodiversity Conservation and Climate Adaptation, held from September 17 to 19 at the State Agriculture Management and Extension Training Institute (SAMETI), Anayara, Thiruvananthapuram was organised by KSBB in association with the National Biodiversity Authority (NBA). It was aimed primarily at mid-career journalists covering environment, climate, science, development, agriculture, forests, wildlife and communities. Kerala Environment Minister Sunny Joseph attended the inaugural session, along with KSBB leadership, representatives and other invited guests.
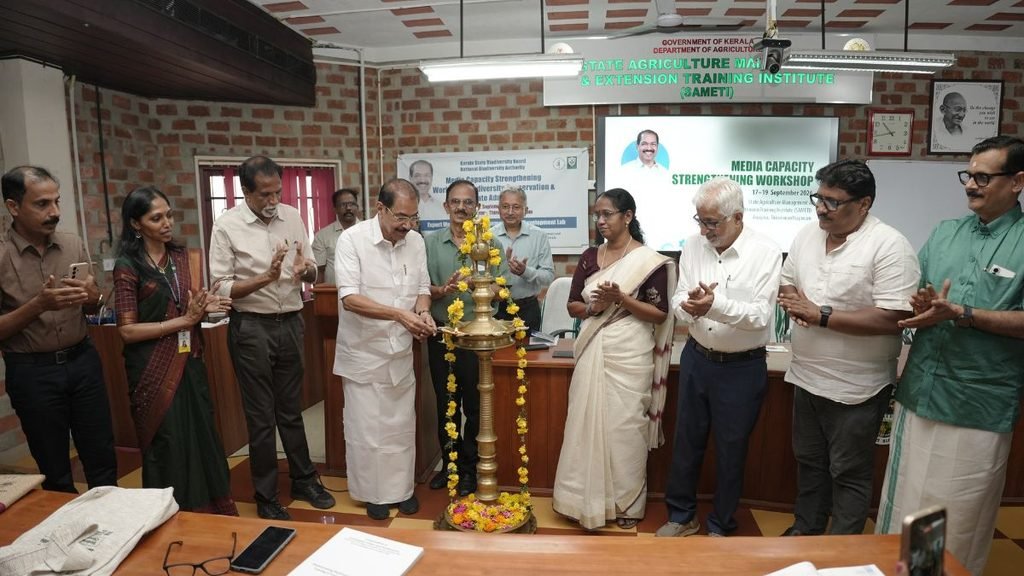
The programme focused on six themes: climate resilience and carbon neutrality, agrobiodiversity and food security, marine and coastal ecosystems, urban biodiversity and heat stress, human-wildlife conflict, and invasive alien species. Field engagements were also included to connect scientific and policy discussions with local ecosystems and communities.
Biodiversity as a Climate Story
The workshop examined Kerala’s 98 Ecologically Sensitive Area villages covering 8,711.98 sq km, and the role of forests, wetlands and other ecosystems in reducing climate risks such as floods, landslides and erosion. These ecosystems also function as carbon sinks and support local livelihoods.
Human-wildlife conflict was another major focus. KSBB’s workshop material records 390 human deaths and more than 5,400 injuries from wildlife attacks between 2021 and 2025, with elephants accounting for 111 fatalities. More than ₹41 crore has been disbursed as compensation since 2021.
Agriculture was discussed through the lens of both biodiversity loss and food security. Paddy cultivation in Kerala has declined by more than 75% since the 1970s, from over eight lakh hectares to less than two lakh hectares. The loss of traditional crop varieties and increasing monocropping were discussed as concerns for long-term agricultural and climate resilience.
The marine and coastal sessions examined Kerala’s 600-km coastline, coastal erosion, declining fish catches, blue carbon and community-based fisheries governance. KSBB’s workshop material notes that nearly 45% of Kerala’s beaches have experienced erosion, while fish catch has declined by about 20% over the past decade.
Urban biodiversity was considered through the example of Thiruvananthapuram, where KSBB has developed a City Biodiversity Index based on the Singapore Index framework. The index maps urban trees, wetlands, ecological corridors and biodiversity parks to bring biodiversity considerations into urban planning.
The workshop also examined invasive species including Senna spectabilis, Mikania micrantha, Eichhornia crassipes and Tilapia, and the pressures they place on native biodiversity, agriculture, forests and aquatic ecosystems.
The Role of KSBB
The Kerala State Biodiversity Board is an autonomous body under the State Environment Department, headquartered in Thiruvananthapuram. It functions under the Biological Diversity Act, 2002, the Biological Diversity Rules, 2004 and the Kerala State Biological Diversity Rules, 2008. Its mandate includes conserving and protecting the state’s agro, plant and fish diversity.
The Board’s work includes Biodiversity Management Committees (BMCs), People’s Biodiversity Registers (PBRs), Biodiversity Heritage Sites, research and awareness programmes, and Access and Benefit Sharing (ABS). These mechanisms connect biodiversity documentation and conservation with local governments and communities.
The workshop was also aligned with the Kerala State Biodiversity Strategy and Action Plan (K-SBSAP) 2025–2035, which provides a framework for conserving, restoring and sustainably managing the state’s biological and cultural heritage.
By bringing journalists into conversations with scientists, officials and communities, the three-day programme sought to make biodiversity reporting less confined to technical conservation issues and more attentive to the questions that affect everyday life, from food and livelihoods to heat, floods, wildlife conflict and the resilience of Kerala’s ecosystems.
Climate
India tops the world for population exposed to climate-driven risky heat
Climate-driven heat exposed 117 million people in India to a month or more of risky heat between June and August 2026, Climate Central found.
Climate
August 2026 Was the Warmest Month on Record
August 2026 tied July 2023 as the warmest month ever recorded globally. Record ocean temperatures and strengthening El Niño conditions add another dimension to the climate signal, with implications for India’s already uneven monsoon.
August 2026 tied July 2023 as the warmest month ever recorded globally. But the significance of the latest record lies beyond the temperature figure itself. Heat was building across the oceans, western Europe endured its hottest summer on record, and in India, a strengthening El Niño was adding pressure to an already uneven monsoon.
The global average surface air temperature in August was 16.96°C, 0.85°C above the 1991–2020 average, making it the warmest August in the ERA5 record. Relative to the estimated 1850–1900 pre-industrial average, temperatures were 1.65°C higher. It was the first month to cross 1.5°C since November 2025.
A single month above 1.5°C does not mean the Paris Agreement’s long-term temperature threshold has been breached. That threshold is assessed over a much longer period. What the August figure does show is how far short-term temperatures can now move beyond the historical baseline.
The Oceans Are Sending Their Own Signal
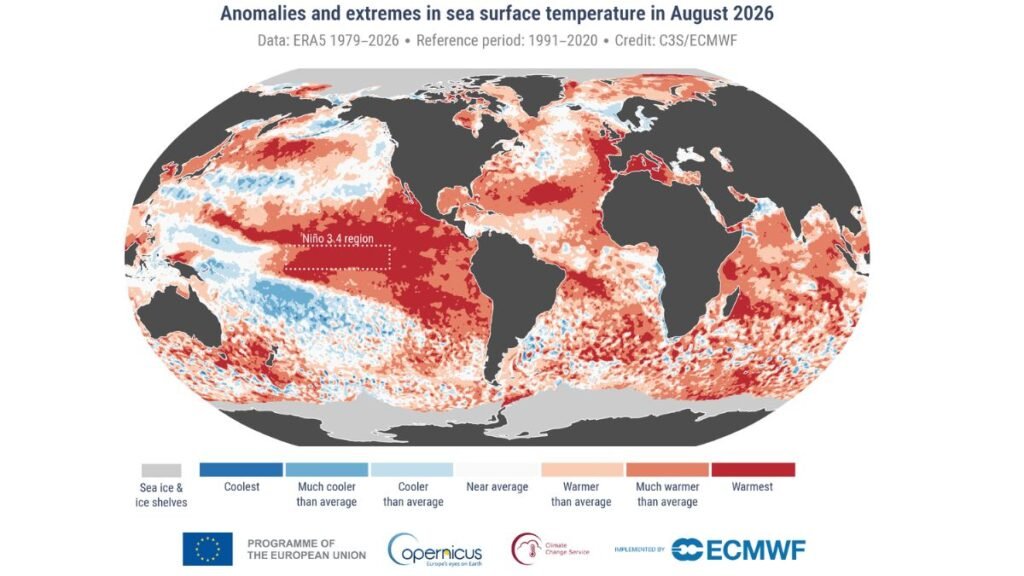
The heat was not confined to the atmosphere. Extra-polar oceans recorded their warmest August in the ERA5 dataset, with an average sea surface temperature of 21.07°C. That was also tied with March 2024 for the highest monthly average recorded for any month.
The tropical Pacific was particularly warm as El Niño conditions strengthened. Around Europe, Atlantic and western Mediterranean waters reached record August temperatures, alongside widespread strong or severe marine heatwaves.
The ocean matters here because its warmth can influence atmospheric circulation, rainfall and marine ecosystems. In 2026, its connection to India’s monsoon was particularly relevant.
India Was Watching the Pacific
For India, the global temperature record arrived against a difficult monsoon backdrop. The India Meteorological Department had forecast below-normal rainfall for the 2026 southwest monsoon. By August 2, cumulative rainfall was 12% below the long-period average, with 47% of districts facing deficient or large-deficient rainfall. IMD attributed part of the suppressed monsoon circulation to the development and strengthening of El Niño conditions in the equatorial Pacific.
The deficits were not uniform. By early August, Kerala and Mahe were 22% below normal, while 16 meteorological subdivisions had rainfall deficits ranging from 20% to 38%.
That does not mean August’s global heat record caused India’s rainfall deficit. The monsoon is shaped by several interacting climate systems, and El Niño is only one of them. But the concurrence is significant: while the tropical Pacific was registering exceptional warmth, India was dealing with a monsoon season that was already running below its seasonal benchmark.
Europe Shows the Cost of Persistent Heat
Western Europe had its warmest summer on record in 2026, surpassing the previous record set in 2003. Heatwaves arrived early and persisted through the season. Heat was accompanied by prolonged dryness. Severe drought conditions were reported in France, the UK, Hungary, Romania and Serbia, while exceptionally low river flows affected the Rhine, Danube, Southern Bug and Dnieper.
The connection is important: extreme heat does not operate in isolation. When high temperatures persist alongside rainfall deficits, their effects can accumulate across agriculture, water systems, ecosystems and wildfire risk.
The Record Is Becoming the Background
August’s warmth is more revealing when viewed alongside the other records surrounding it. The month saw exceptional ocean temperatures and low sea-ice levels, while June–August was jointly the warmest global summer on record, matching 2024.
The challenge in interpreting such records is to look beyond the headline number. A record month does not mean every region experienced record heat. It means the global climate system is operating from a warmer baseline, while regional weather continues to be shaped by monsoons, El Niño, ocean temperatures and other climate patterns. August 2026 was another record. Its importance may ultimately lie in how quickly records such as this stop looking extraordinary.


Earth is Heating Up: The Economic Cost of a Rising Sea

Digital Detox: Why Taking a Break From Screens Matters

When a Village Walks Together, Even Drought Is Defeated. How Halma Breathed Life Back into Kesarpura’s Pond

100% Access in China, 5% in South Sudan: The Global Electricity Gap

India to Push Indian Sign Language Into Everyday Life

From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story

Farmers Borrowed to Build ‘Diggis’. Two Years Later, They Are Still Waiting for the Subsidy

Aim for the Stars: Anjali Thomas’s Journey from a Small College in Kerala to the Frontiers of Medical Imaging

When the Himalayas Collapse Without Warning, What Counts as Preparedness?

Anxiety Freezes Career Decisions. Curiosity Unfreezes Them
-

 Math2 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
Climate2 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
Society3 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics4 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews3 days ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate4 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society3 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society3 months ago
From Bell Labs to the Classroom: A Second Career in Teaching