Space & Physics
How India’s Semiconductor Industry Rose From Ashes to Atoms
How India is rebuilding its semiconductor future—from a lost opportunity in the 1980s to a high-stakes push to master the science, scale, and systems that define the global chip industry.

India’s semiconductor ambition is not merely an industrial policy experiment—it is an attempt to rebuild a technological capability lost decades ago, and to do so in a world where chips have become instruments of economic power and geopolitical leverage. From the ashes of an early setback to a renewed push backed by billions in investment, the country is seeking to construct an ecosystem that spans physics, engineering, and global supply chains. The challenge is not simply to manufacture chips, but to master the science, scale, and systems that define the industry—an effort that will unfold not over years, but over generations.
From early setbacks to a renewed national push, India is attempting to build one of the world’s most complex industrial ecosystems – where physics, policy, and geopolitics converge.
In the early months of 1989, India’s most ambitious experiment in semiconductor manufacturing came to an abrupt halt. A fire tore through the country’s primary chip fabrication facility in Mohali, Punjab, crippling an ecosystem that had taken years to build and, more importantly, interrupting a trajectory that might have placed India far closer to the global frontier.
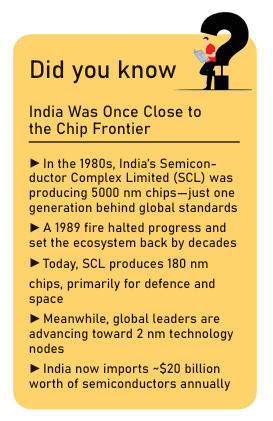
The Semiconductor Complex Limited (SCL), established in 1976, had begun producing chips in 1984—at 5000 nanometers, just one generation behind global standards. India was not leading the semiconductor race, but it was not far behind either—especially in an industry where catching up later becomes exponentially harder.
This was only 13 years after Intel introduced the world’s first microprocessor—and three years before Taiwan Semiconductor Manufacturing Company (TSMC) began production. The fire changed everything. Its cause was never officially determined. Investigators noted that it appeared to have started at multiple points—fuelling speculation of sabotage. What followed was not just physical damage, but institutional collapse.
India lost infrastructure.
India lost talent.
India lost time.
The disruption was not merely industrial. It was institutional. Engineers dispersed, expertise dissipated, and momentum stalled. By the time operations resumed years later, the global semiconductor landscape had already shifted irreversibly. Today, SCL—now a research-focused facility—produces legacy chips of around 180 nanometers, primarily for defence and space applications. Meanwhile, TSMC is manufacturing 3-nanometer chips and preparing for 2-nanometer production.
The gap is not incremental, it is generational. India imported semiconductor chips worth nearly $20 billion in 2024, with demand growing rapidly as electronics penetrate every aspect of life. And yet, semiconductors remain invisible—embedded in everything, owned by others. TSMC produces chips for global giants like Apple and Nvidia. SCL serves strategic domestic needs
More than three decades on, India is attempting to rebuild that lost trajectory.
But the context has changed. Semiconductors are no longer obscure components buried within devices. They are the foundation of artificial intelligence, telecommunications, defence systems, and economic competitiveness. They shape not just markets, but geopolitics.
India is not simply re-entering an industry it once attempted to build. It is stepping into one of the most complex and strategically contested systems in the modern world.
In March 2026, Prime Minister Narendra Modi inaugurated a INR 3,300 crore semiconductor facility in Gujarat, declaring India a “reliable global supplier” in an increasingly fragmented chip economy. Around the same time, Union Minister Ashwini Vaishnaw announced that multiple semiconductor plants are expected to come online over the next few years, with the first fabrication output targeted before the end of the decade. But behind the announcements lies a deeper reality. India is not building a factory. It is attempting to build one of the most complex scientific-industrial ecosystems ever created.
The Physics Beneath the Industry
To understand the scale of India’s ambition, it is necessary to understand what a semiconductor actually is—not as a product, but as a process. Modern chips are constructed at nanometre scales, where the behaviour of electrons begins to defy classical expectations. Transistors—billions of which are embedded within a single chip—operate by controlling the flow of these electrons through carefully engineered silicon structures. But as these structures shrink, the physics becomes increasingly unstable.
Electrons leak across barriers that were once reliable. Heat accumulates in ways that are difficult to dissipate. Materials behave unpredictably under extreme miniaturisation. What appears as incremental progress in computing power is, in reality, a constant negotiation with the limits of matter.
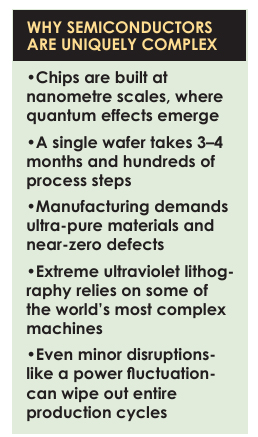
“A single wafer can take three to four months to manufacture, and there are hundreds of layers that have to be deposited,” notes Neelkanth Mishra, an expert on India’s semiconductor policy and Chief Economist at Axis Bank.
Each of these layers involves a sequence of deposition, etching, doping, and cleaning processes, repeated dozens of times with near-perfect precision. The tolerances are so tight that even microscopic contaminants can render entire batches unusable.
“The chemicals used in wafer cleaning are extraordinarily high purity, and even small impurities can affect yields,” Mishra adds. The process is not only delicate but energy-intensive. As IIT Bombay’s Udayan Ganguly explains, a single thermal step in fabrication can raise the temperature of a silicon wafer from ambient levels to over 1,000 degrees Celsius within seconds, requiring enormous power and precise control.
What emerges from this process is not simply a manufactured object, but a highly controlled physical system—engineered at scales where conventional intuition no longer applies.
A System Defined by Control
If the science of semiconductors is unforgiving, the global ecosystem built around it is equally restrictive.
“From design software to lithography to testing equipment, 90% of the industry is controlled by just two or three companies in each segment,” Mishra observes.
This concentration reflects decades of accumulated expertise, capital investment, and intellectual property. In some areas, such as extreme ultraviolet lithography—the process required to produce the most advanced chips—the dependence is even more pronounced.
“If you want to do extreme ultraviolet lithography, there is only one company in the world that can do it.” Such chokepoints have transformed semiconductors into strategic assets. Access to technology is no longer determined solely by markets, but increasingly by geopolitical alignment and national priorities.
For countries seeking to build domestic capabilities, this creates a paradox: the need to integrate into a global system while simultaneously reducing dependence on it.
India’s Semiconductor Industry: Policy Meets Scale
India’s renewed push into semiconductors is structured around this tension.
The India Semiconductor Mission, launched in 2022 with a substantial fiscal outlay, represents one of the most ambitious industrial policy initiatives in the country’s recent history. Since then, the government has approved ten semiconductor projects with investments exceeding ₹1.6 lakh crore across six states, covering fabrication, packaging, and specialised semiconductor technologies.
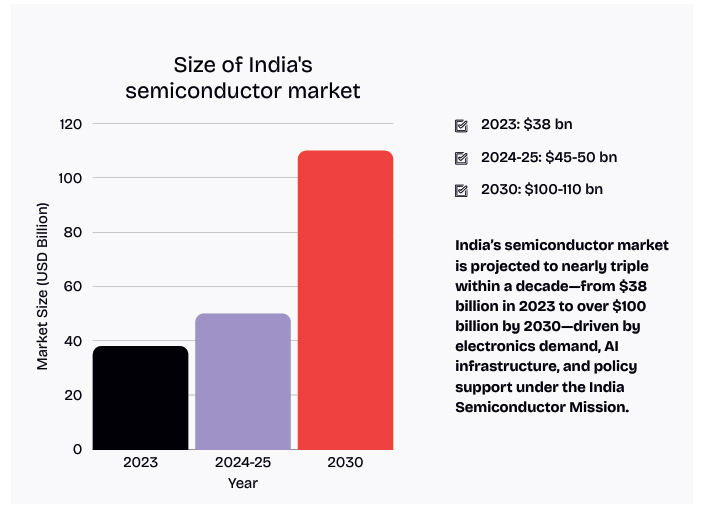
This is not an isolated effort. It is an attempt to build multiple layers of the value chain simultaneously. Early investments have focused on assembly, testing, and packaging facilities—segments that are less capital-intensive and can be scaled relatively quickly. Projects such as the Micron packaging facility in Gujarat, along with other recently approved units, are expected to serve as entry points for building industrial capability.
At the same time, larger and more complex initiatives—such as the proposed fabrication facility in Dholera—are intended to anchor the ecosystem over the longer term.
The second phase of the mission signals a shift in emphasis. Beyond manufacturing, the focus is expanding to include materials, equipment, and intellectual property—areas that are critical for long-term self-reliance.
Prime Minister Narendra Modi has framed semiconductors as central to India’s technological future, calling for the country to become a “reliable global supplier.” Union Minister Ashwini Vaishnaw has indicated that multiple plants are expected to become operational within this decade.
India’s Semiconductor Industry and The Design Advantage
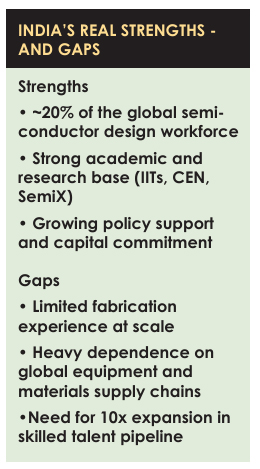
Despite its limited manufacturing footprint, India occupies a significant position in the global semiconductor landscape through design.
Nearly one-fifth of the world’s semiconductor design engineers are based in the country. Global firms rely on Indian teams to develop chips used in everything from consumer electronics to advanced computing systems. Nearly 20% of the global semiconductor design workforce is based in India. Companies such as Intel, Qualcomm, Nvidia, AMD, and Broadcom rely on Indian engineers for chip design.
“In a ten-dollar chip, five to six dollars of value is captured by the designer,” Mishra points out. This concentration of talent provides India with a strategic advantage, particularly in a world where intellectual property increasingly determines value. India has mastered design. What it has not yet built is manufacturing scale. However, this strength has historically been tied to global companies. The challenge now is to translate it into domestic capability—developing Indian firms that can own and commercialise their designs.
The Ecosystem Question
The central challenge for India lies not in any single segment of the semiconductor value chain, but in the integration of all its components.
“You cannot just build wafer fabs. You need everything—from capital equipment to chemicals—to make the ecosystem viable,” Mishra says.
A semiconductor industry requires:
- Reliable energy and water infrastructure
- Access to specialised materials and gases
- Advanced manufacturing equipment
- A continuous pipeline of skilled talent
It also requires coordination across institutions.
“The ecosystem is a triple helix—academia, industry, and government,” says Swaroop Ganguly of IIT Bombay. “Without tight collaboration, it cannot work.”
This interdependence makes semiconductors fundamentally different from most other industries. Progress in one area depends on parallel advances in others.
Institutions That Sustained the Science
Even during the decades when India lacked large-scale manufacturing, certain institutions preserved and advanced semiconductor research.
At IIT Bombay, work in microelectronics dates back to the 1970s, when the institute began building capabilities in semiconductor devices and integrated circuits. Over time, this evolved into more sophisticated infrastructure, including cleanroom facilities and collaborative programmes with organisations such as ISRO.
The establishment of the Centre of Excellence in Nanoelectronics (CEN) in the early 2000s further strengthened this foundation, enabling advanced research in semiconductor devices and fabrication techniques. By the late 2010s, India had emerged as a significant contributor to global semiconductor research, with IIT Bombay playing a leading role in experimental nanoelectronics.
In 2023, these efforts were consolidated under SemiX, a dedicated centre aimed at integrating research, talent development, and industry collaboration.
The Economics of Dependence
Semiconductors underpin virtually every modern activity, yet their economic footprint often goes unnoticed. “Every time you go to a doctor, drive a car, or watch a movie—you are effectively paying a semiconductor fee,” says Udayan Ganguly.
The observation is less rhetorical than it appears. As digital systems expand, the cost of semiconductors becomes embedded in everything from healthcare to transportation.
“If India does not control semiconductors to some extent, we are basically fighting a losing battle.”
This framing shifts the conversation from industrial policy to economic sovereignty. Control over semiconductors is not merely about manufacturing capacity; it is about retaining value within the economy.
Innovation as a Continuous Process
One of the defining characteristics of the semiconductor industry is its pace of change. “Semiconductors are not a bandwagon you jump onto—it’s a treadmill,” Ganguly notes. “If you stop running, you fall off.” Technological progress is relentless. Every generation of chips introduces new architectures, materials, and manufacturing techniques. Companies that fail to keep up quickly lose relevance.
“You cannot just build a plant and expect to coast,” Udayan Ganguly adds.
For India, this implies that building initial capacity is only the first step. Sustained investment in research and development will be essential to remain competitive.
Scaling Talent and Capability
India’s talent base is often cited as its greatest advantage, but scaling that advantage presents its own challenges. “We have the core capability,” says Udayan Ganguly. “But to meet demand, we need to scale talent by at least ten times.” This expansion cannot rely solely on elite institutions. It requires a broader transformation of engineering education, incorporating interdisciplinary training across physics, chemistry, materials science, and mechanical engineering. “Semiconductors are not just electronics,” Swaroop Ganguly emphasises. “They require multiple disciplines working together.”
The Long Horizon
Semiconductor ecosystems are not built quickly. The experience of other countries underscores this timeline. Taiwan, South Korea, and China invested consistently over decades before achieving their current positions.
“The Chinese started investing in the late 1990s and are still building capabilities—this is at least a 15–20 year journey,” Mishra notes.
For India, the challenge is not only to start, but to sustain momentum across political and economic cycles.
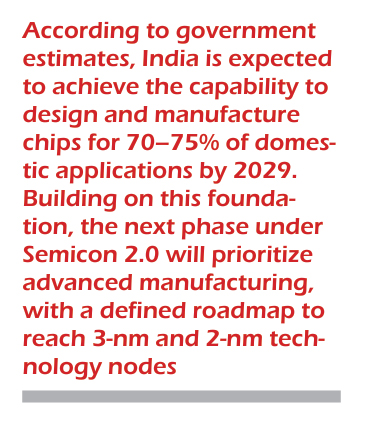
According to government estimates, India is expected to achieve the capability to design and manufacture chips for 70–75% of domestic applications by 2029. Building on this foundation, the next phase under Semicon 2.0 will prioritize advanced manufacturing, with a defined roadmap to reach 3-nm and 2-nm technology nodes. By 2035, India aims to establish itself as one of the world’s leading semiconductor nations.
India’s semiconductor industry ambitions are rooted as much in history as in future aspirations. The loss of early momentum in the late twentieth century delayed its entry into an industry that rewards continuity and scale. Today, the country is attempting to rebuild that trajectory under far more complex conditions. The progress made so far—policy frameworks, investment commitments, institutional capacity—suggests that the foundation is being laid. But the real test lies ahead.
Semiconductors are not merely manufactured. They are engineered—through sustained effort, coordinated systems, and long-term commitment.
From the ashes of past setbacks to the atomic precision of modern chipmaking, India’s semiconductor journey has begun again. Whether it can be sustained will determine not just the future of an industry, but the contours of technological power in the decades to come.


Space & Physics
World Space Week 2026: How the Rocket Revolution Is Changing Space
World Space Week 2026 explores the Rocket Revolution, from reusable launchers and private space companies to the growing role of satellites.

Space & Physics
A Dead Star Feeds Off Planet Formed From Its Ashes
It adds to a known coterie of planets now found orbiting dead stars, astronomers are busy studying to spot signs of life.

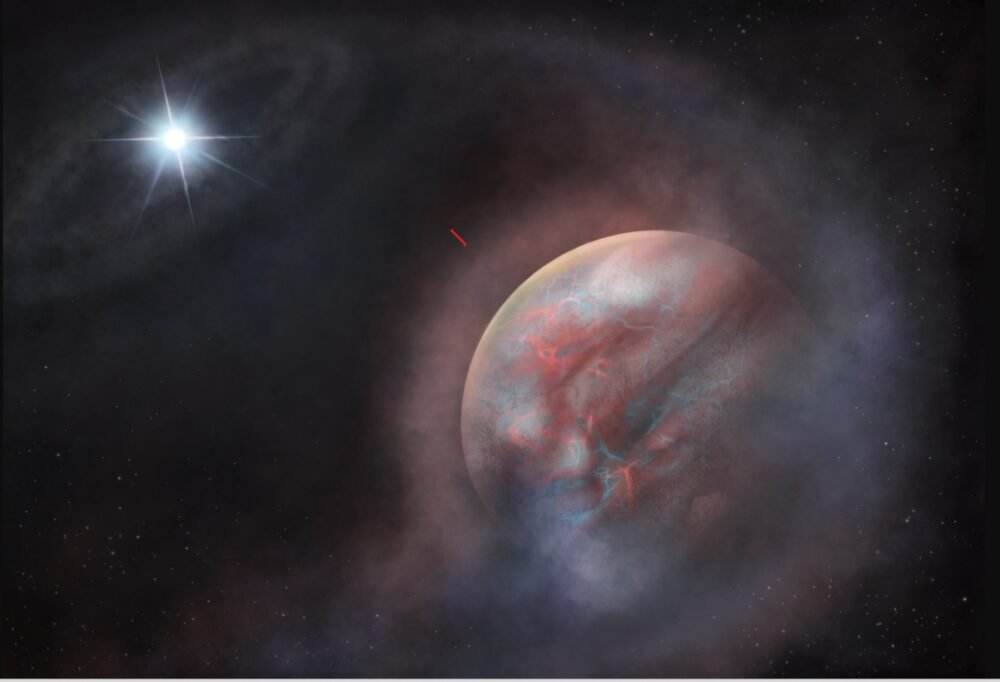
A planet orbiting once every 4 days around a white dwarf star HS 0209+0832 – about 270 light years in the direction of the constellation Pisces – is steadily losing its atmosphere to its host star. While many stars in solar systems beyond our own often feed on their planets, this particular star feeds on its own ashes.
The gaseous planet HS 0209+0832 b was discovered in 2024, when the Transiting Exoplanet Survey Satellite, a NASA space telescope, found it orbiting the white dwarf star over the course of four days. The new study followed through with detailed observations from TESS data, NASA’s space-based Far Ultraviolet Spectroscopic Explorer, in addition to the ESO’s mountain-based Very Large Telescope, to study the star’s atmosphere and in turn inferring some chemistry occurring in the planet.
In a study published in the journal Nature Astronomy on Monday and funded by NASA, European Research Council, Fundación Occident and the Instituto de Astrofísica de Canarias, an international team of astronomers have reported imprints of niobium, a heavy element, in the atmosphere of a white dwarf star.
Astronomers predict the transiting young planet around the dead star is supplying that niobium back to its host. The sighting is evidence of a “second generation” planet, one of many candidates identified over several years, manifesting in a myriad different ways from spent gas ejected in the wake of stellar deaths.
It adds to a known coterie of planets now found orbiting dead stars, astronomers are busy studying to spot signs of life.
What are white dwarf stars?
White dwarves are an exotic stars, and are all that’s left off giant stars shedding their large gaseous skin in violent deaths. Our sun is destined one day to transform into a white dwarf, but only after swelling in size some five billion years from now to become a red giant when it will eclipse past the earth’s orbit. It would take several million years after that for the red giant sun to shed its gaseous exterior to become a white dwarf.
Planets if any, found orbiting these dead stars may have likely migrated from the new solar system’s outer reaches. All that’s left off the progenitor star’s past are imprints of light metals and other elements on the white dwarf’s atmosphere. Such planets have previously been spotted orbiting pulsars, a kind of neutron star, back in 1992. In fact, its discovery had marked the first ever detection of any planet orbiting a star beyond our sun.
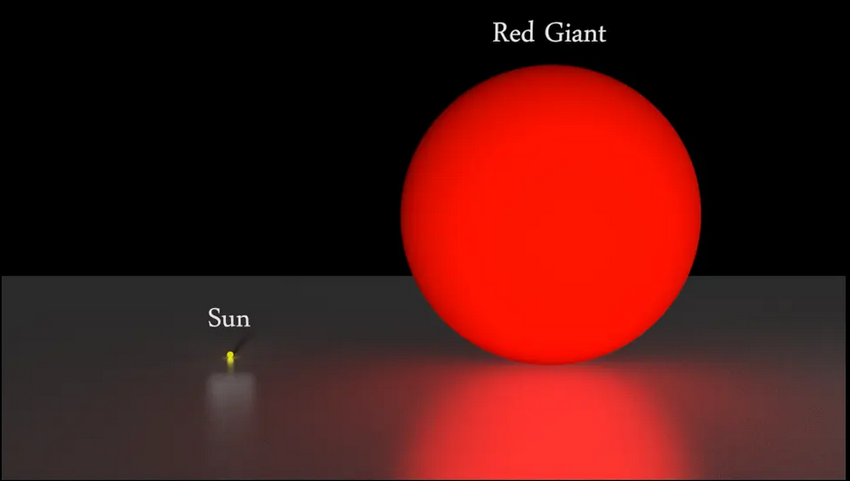
In five billion years, our sun will evolve to become a red giant star. Credit: Svitlana Leonidivna Malchenko
Sighting niobium
Elements such as niobium don’t typically form in the core of stars like our sun. Chemical production usually limits to elements lighter than or until iron, with its 26 protons and 30 neutrons. Beyond that, slamming an extra proton or neutron will cause those to split, leaving iron to be the last element to be directly forged.
Niobium, with 41 protons and 52 neutrons, is thought to be born after absorbing slow passing neutrons when the red giant star dies to form a white dwarf star. This niobium hitches a ride along with rest of the contents of the red giant star, farther into the outer reaches of the system after the formation of the white dwarf.
These contents could create a new disc of circumstellar material with dust and gas that could condense one day to form new planets. The “second generation” planet found orbiting the white dwarf star from the new study, could have been born this way.
Alternatively, it may have been a planet in the outskirts like Neptune, migrating inwards, and enriching itself with niobium-rich star material.
Either way, the planet got too close to its host star, which is irradiating its newfound niobium-rich atmosphere, stripping it away and devouring it.
While it’s likely not a candidate planet for life as we know it to be found, it’s discovery can help ascertain how such worlds are formed in the aftermath of a star’s various phases of evolution.
Space & Physics
Artemis Accords Reach 76 Countries: What It Means for India
The Artemis Accords now have 76 signatories. With NASA inviting ISRO to its Moon Base programme, India’s role in lunar exploration is expanding.
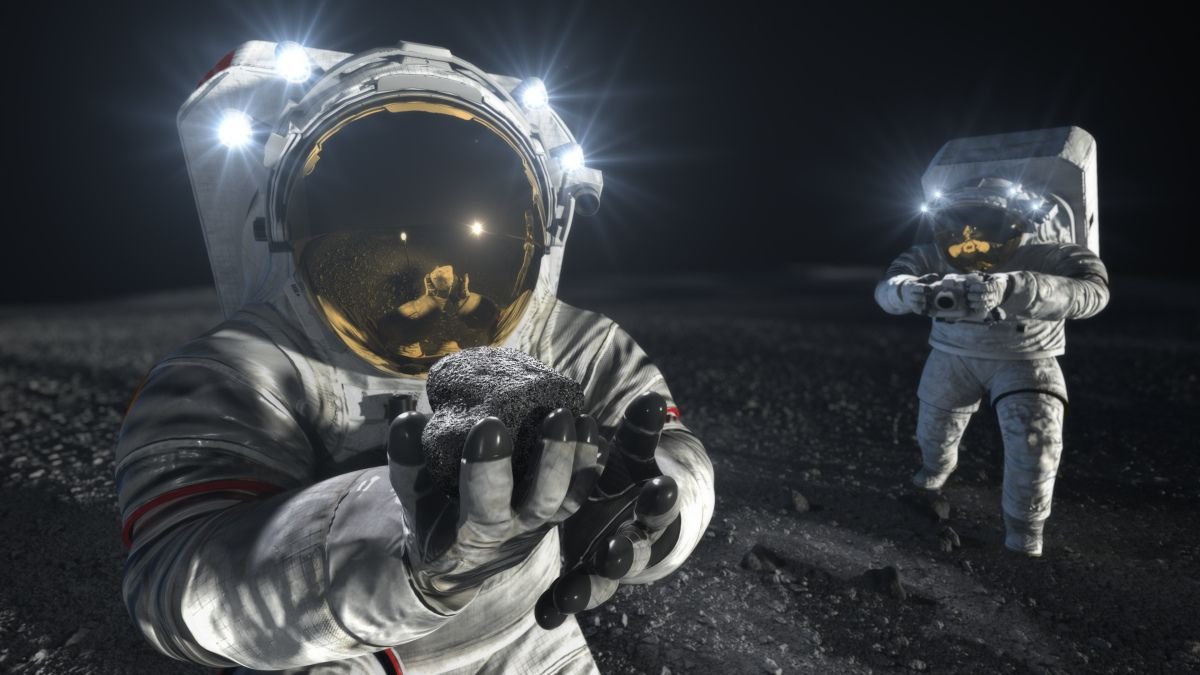
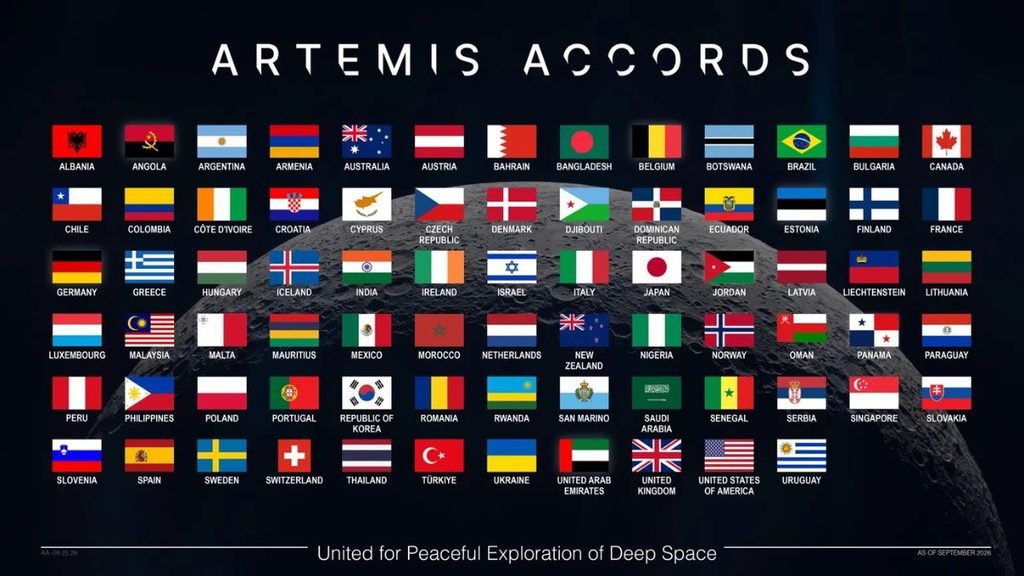
The Artemis Accords now have 76 signatories, expanding the international framework around the next phase of lunar exploration. For India, the milestone comes weeks after NASA invited the Indian Space Research Organisation (ISRO) to participate in its planned Moon Base programme.
Albania, Croatia, Côte d’Ivoire and San Marino joined the Accords in September, taking participation to 76 countries. NASA says nearly 40% of the world’s nations are now part of the framework, which sets principles for peaceful, transparent and responsible exploration of the Moon, Mars and beyond.
India became the 27th signatory in June 2023. At the India-US Civil Space Joint Working Group meeting in Bengaluru in August, NASA invited ISRO to participate in its Moon Base programme. The two countries also agreed to advance discussions on open scientific-data sharing under the Accords.
India’s Moon Base opportunity
The invitation does not specify what India will contribute. NASA has said every Artemis Accords signatory can participate through scientific payloads, technology demonstrations, CubeSats and other capabilities. Any specific Indian contribution would require further agreements.
India, however, is developing its own increasingly ambitious lunar programme. ISRO’s Chandrayaan-4 is planned as a lunar sample-return mission, designed to collect samples from the Moon’s polar region and bring them back to Earth. Chandrayaan-5/LUPEX, being developed with Japan’s JAXA, will study lunar polar volatiles in situ.
These missions could give India experience and scientific capabilities relevant to a future international lunar infrastructure.
ISRO Shaping the Data Conversation
Scientific data could be another area of Indian participation. In May 2026, ISRO led an initial Artemis Accords discussion on advancing open-data practices. NASA subsequently held two workshops focused on making lunar scientific data more accessible, interoperable and reproducible across countries.
That is significant as more lunar missions target the same regions. Shared standards could allow researchers to combine observations from different spacecraft instead of treating each mission’s data separately.
Moon – Space Coperation
India-US space cooperation is also expanding into human spaceflight. ISRO’s 2025–26 annual report records that Indian astronaut Shubhanshu Shukla travelled to the International Space Station in June 2025 as part of the Axiom-4 mission and conducted seven microgravity experiments. ISRO also held discussions with NASA on potential cooperation related to Gaganyaan.
The Artemis relationship therefore sits alongside an existing programme of India-US cooperation, including the NASA-ISRO Synthetic Aperture Radar (NISAR) mission.
What Changes for India?
The significance of the 76-country milestone lies in the network developing around it. The Artemis Accords cover scientific-data sharing, interoperability, non-interference between missions, emergency assistance and protection of historically significant lunar sites. NASA says signatories are now working through technical meetings and workshops to put these principles into practice.
For India, that creates several possible avenues: contributing technology or science to NASA’s Moon Base effort, sharing lunar data, and working with a growing group of countries on standards for increasingly crowded lunar operations. What India’s specific contribution to the Moon Base remains undecided. But with Chandrayaan-4, LUPEX and its human-spaceflight programme advancing alongside deeper NASA cooperation, India is entering the next phase of lunar exploration with its own capabilities already taking shape.


WHO Urges Lifestyle-first Approach as 170 Million Children and Adolescents Live with Obesity

Centre Asks States to Ensure Hospitals Display Service Charges

Automated Homoeopathic Dispensing System Receives Indian Patent

After a Scorching Summer, Delhi’s Children Are Slow to Return Outdoors

Ashtalakshmi Darshan: Why India Is Bringing Students to the Northeast

From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story

Knowing When to Think for Ourselves: AI, Intuition and the Education of Discernment

Aim for the Stars: Anjali Thomas’s Journey from a Small College in Kerala to the Frontiers of Medical Imaging

Two Chemists Win Nobel Prize for Solving a Century-Old Puzzle: Why Life Picks One Hand Over the Other

India’s AI Moment Rests on More Than Code
-

 Math3 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
EP Deep Dive: Data & Solutions3 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
EP Deep Dive: Data & Solutions3 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics5 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews3 weeks ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate4 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society3 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society4 months ago
From Bell Labs to the Classroom: A Second Career in Teaching