Sustainability
India’s EV Manufacturing Push Gains Pace, but Import Dependence Remains a Key Hurdle
India’s EV manufacturing localization is accelerating, but reliance on imported semiconductors and rare-earth materials remains a key challenge.

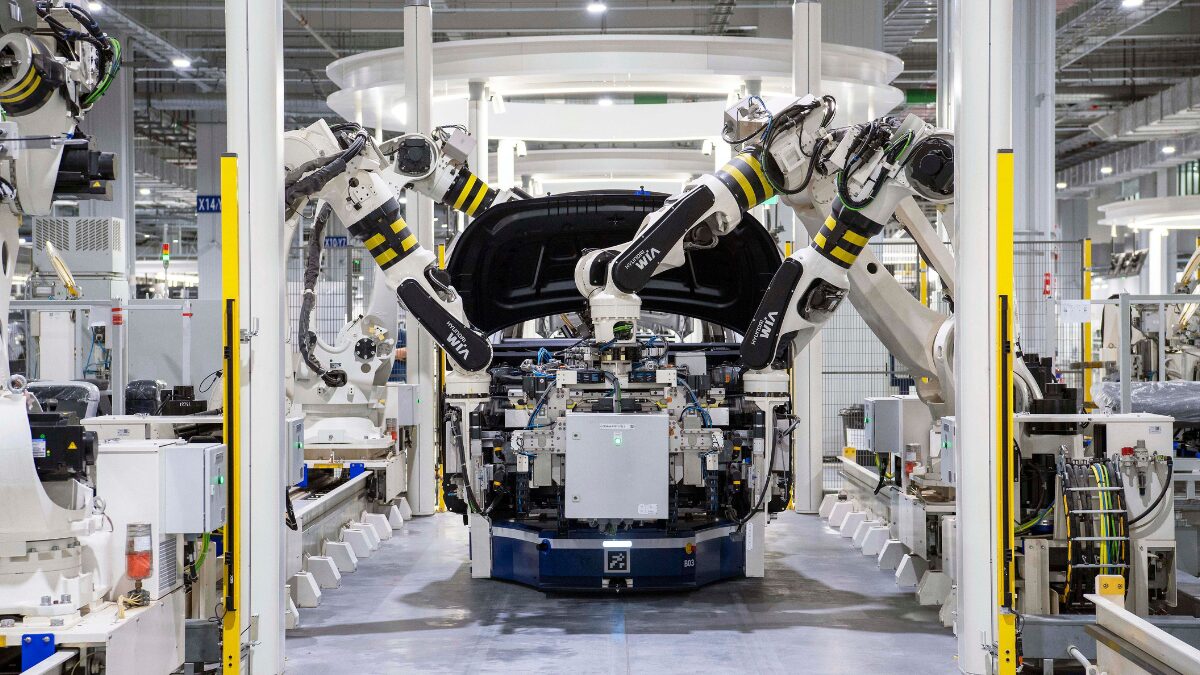
India’s electric vehicle (EV) manufacturing sector is steadily advancing towards localization, with several high-value components expected to be produced almost entirely within the country by 2030. A new report by the Institute for Energy Economics and Financial Analysis (IEEFA) and JMK Research & Analytics notes that the industry is moving beyond basic assembly into more complex manufacturing.
Systems such as motors, power electronics, thermal management units, and charging infrastructure are emerging as key opportunities for domestic production, signaling a structural shift in the EV ecosystem.
Rapid Growth Fuels Domestic Manufacturing
The push for localisation is being driven by strong market growth. Annual EV sales in India have increased nearly 14-fold since 2020, creating significant demand across the value chain. If planned capacities are successfully implemented, several non-battery components could achieve 90–100% localisation by the end of the decade.
Government initiatives have supported this momentum. Around 60% of recent manufacturing announcements come from companies approved under the Production-Linked Incentive (PLI) scheme for automobiles and auto components. However, progress remains uneven, with less than 10% of the ₹25,938 crore allocation disbursed as of early 2026.
Import Dependence Limits Value Creation
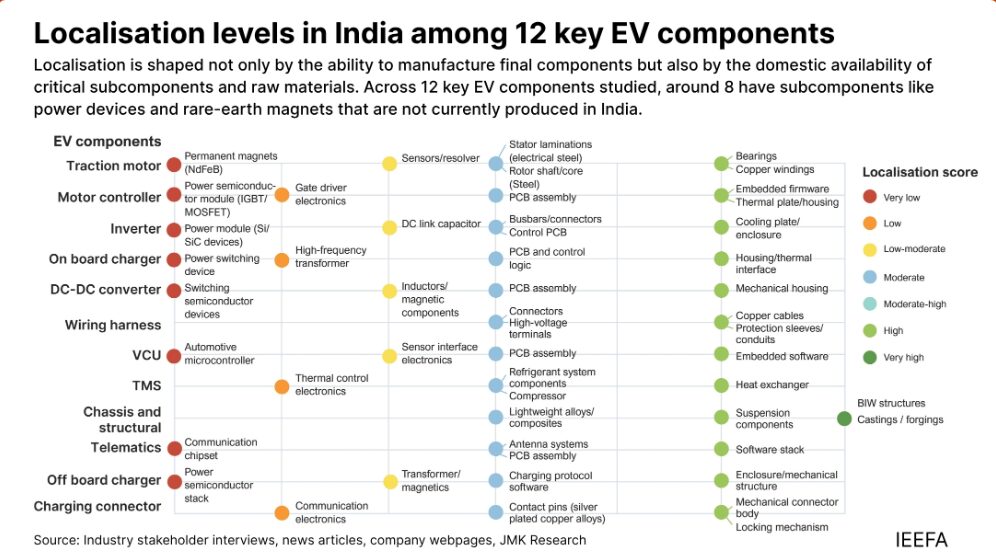
Despite these gains, India’s EV sector continues to rely heavily on imported subcomponents. Semiconductors and rare-earth magnets remain critical inputs for motors, power electronics, and control systems, yet their supply is concentrated in regions such as China and Taiwan.
This dependence limits the extent of value creation within the country, even as assembly and component manufacturing expand domestically.
Supply Chain Gaps Persist
The report identifies semiconductors and rare-earth materials as major bottlenecks in achieving deeper localisation. Without strengthening upstream capabilities, India risks remaining dependent on imports for critical technologies.
“A number of factors could influence future localisation outcomes, including access to critical materials, cost competitiveness, supplier scale, and domestic technology capabilities,” said Charith Konda, Energy Specialist at IEEFA and co-author of the report.
To address these challenges, the report calls for targeted policy and industry interventions. These include accelerating semiconductor and magnet supply chains, promoting component standardisation, encouraging startup participation, and increasing investment in research and development. While industry sentiment remains optimistic, the next phase of India’s EV journey will depend on its ability to move up the value chain and build a more self-reliant clean mobility ecosystem.





Sustainability
CNG, Hybrids and EVs Overtake Petrol in India’s Passenger Vehicle Market
India’s passenger-vehicle market is moving beyond petrol, with CNG, hybrids and EVs together accounting for 41.95% of August sales. The shift shows how cost, convenience and vehicle use are reshaping consumer choices.
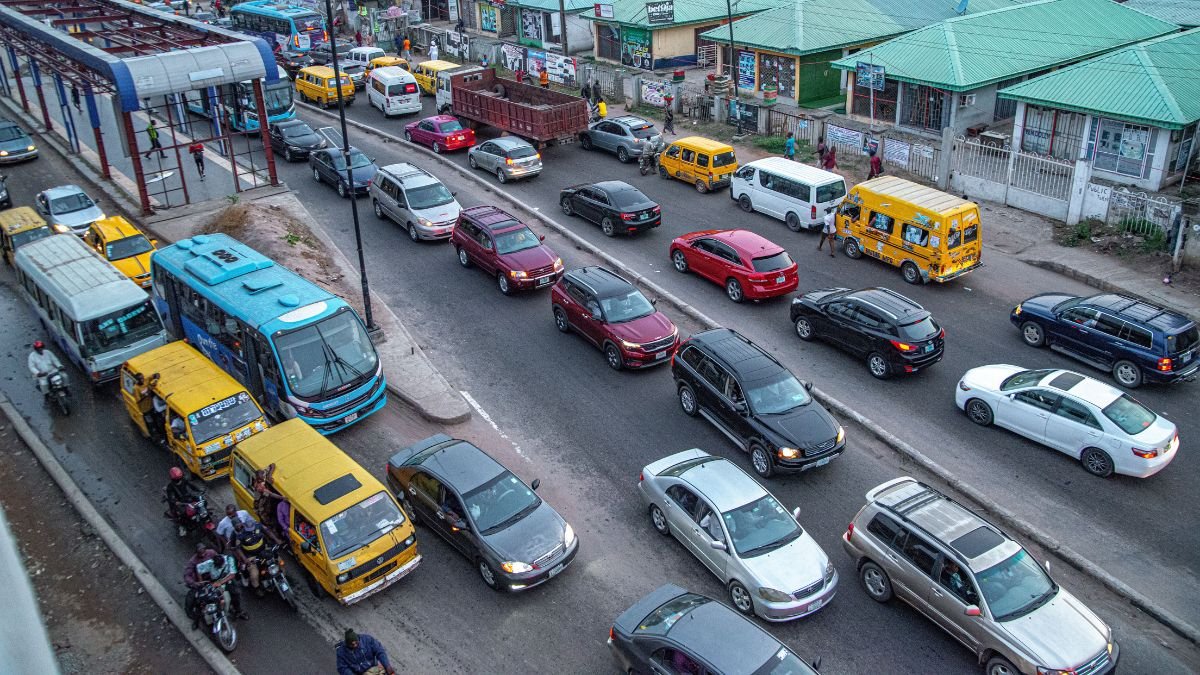
India’s car vehicle market has crossed a significant threshold. In August, CNG, hybrid and electric vehicles together accounted for 41.95% of passenger-vehicle retail sales, narrowly overtaking petrol at 40.85%. For years, petrol has been the default choice for Indian car buyers. But now, data shows CNG accounted for 25.28% of passenger-vehicle sales, hybrids for 9.04% and electric vehicles for 7.63%. Together, they made up 41.95%, compared with petrol’s 40.85%.
The gap is only 1.1 percentage points. But the direction of the change is more significant than the margin. Just a year earlier, petrol had an advantage of nearly 11 percentage points over the combined alternative-fuel category. The data, released by the Federation of Automobile Dealers Associations (FADA), comes against the backdrop of a rapidly expanding passenger-vehicle market. Retail sales reached 4,02,398 units in August, up 16.14% from August 2025 and the first time monthly August sales crossed four lakh.
CNG Still Does Most of the Work
The numbers also show that India’s transition away from conventional petrol is not being driven by electric cars alone.
CNG remains by far the largest alternative, accounting for more than a quarter of passenger-vehicle retail sales. Its appeal is relatively straightforward: lower running costs without the range and charging concerns associated with battery-electric vehicles.
Hybrids occupy a different space. They allow buyers to reduce fuel consumption while retaining the convenience of a conventional refuelling network. Their 9.04% share indicates that consumers are increasingly willing to pay for fuel efficiency without making the complete switch to an electric vehicle. EVs accounted for 7.63% of passenger-vehicle retail sales. That remains a minority share, but the broader picture becomes more striking when other vehicle categories are considered.
Two-wheelers are Moving Faster
Electric two-wheelers crossed a new threshold in August. Of the 17,14,610 two-wheelers retailed during the month, 10.68% were electric. It was the first time their share crossed 10% in a non-festival month, compared with 7.66% in August 2025. Overall two-wheeler retail sales grew 19.69% year on year, although they fell 5.70% from July.
The three-wheeler market is even further along. Electric models accounted for 65.30% of three-wheeler retail sales in August. That contrast is important. India’s vehicle transition is not happening at one uniform speed. Where vehicles are driven intensively and operating costs have a direct effect on earnings — particularly in commercial and three-wheeler applications — electric powertrains are already gaining much stronger market share.
Commercial vehicles are moving more gradually. Electric models accounted for 5.18% of commercial-vehicle retail sales in August, up from 2.06% a year earlier. Total commercial-vehicle sales reached 90,769 units, a 14.45% year-on-year increase.
A Record Market, But not Without Warning Signs
Across all categories, Indian automobile dealers retailed 24,23,201 vehicles in August, up 17.51% from a year earlier. Two-wheelers, passenger vehicles, commercial vehicles, tractors and three-wheelers each recorded their highest-ever August retail volumes, according to FADA. But the month-on-month picture was weaker. Total retail sales were 6.48% below July, when the industry had recorded a record month.
The decline does not necessarily signal a reversal in demand. FADA attributed part of it to the seasonal monsoon lull and the timing of the festival calendar, with Ganesh Chaturthi and some Onam-related buying shifting into September. The passenger-vehicle market also faces a less visible problem: stock.
Dealer inventory increased to around 38–40 days, compared with FADA’s recommended 21 days. More than half of passenger-vehicle dealers reported higher inventory than in July. That leaves manufacturers and dealers heading into the festive season with strong demand expectations but also a substantial amount of stock to manage.
The E20 question
The fuel transition is also unfolding amid India’s move towards higher ethanol blending in petrol. FADA says dealers are reporting some consumer hesitation around the E20 transition, petrol containing up to 20% ethanol, with running costs and fuel economy among the concerns cited.
That should not be read as proof that E20 is driving the entire shift. The rise of alternative powertrains has several overlapping explanations: greater model availability, lower running costs, improving EV technology and a wider consumer choice than existed a few years ago. But the timing is notable. Buyers who are uncertain about the long-term economics of petrol vehicles now have more alternatives to choose from.
What the August numbers really show
The headline figure is not that petrol cars have suddenly become unpopular. Petrol remains the largest single fuel category in India’s passenger-vehicle market. The more important change is that there is no longer one dominant alternative to petrol. CNG, hybrids and EVs are each attracting different kinds of buyers and together they have become a larger force than petrol.
The shift is even clearer in other segments. Electric vehicles already dominate three-wheelers and have crossed 10% of two-wheeler retail sales. India’s automobile transition, therefore, is unlikely to follow a simple path from petrol to electric cars. It is becoming a more complicated mix of CNG, hybrid, battery-electric and conventional vehicles, shaped by price, running costs, infrastructure and how each vehicle is used.
August’s numbers offer the clearest sign yet that this transition has moved from being a niche trend to a mainstream consumer choice. For the first time, India’s car buyers collectively chose alternatives to petrol more often than petrol itself.
Climate
The Giant Steel Gates Guarding the Netherlands from the Sea
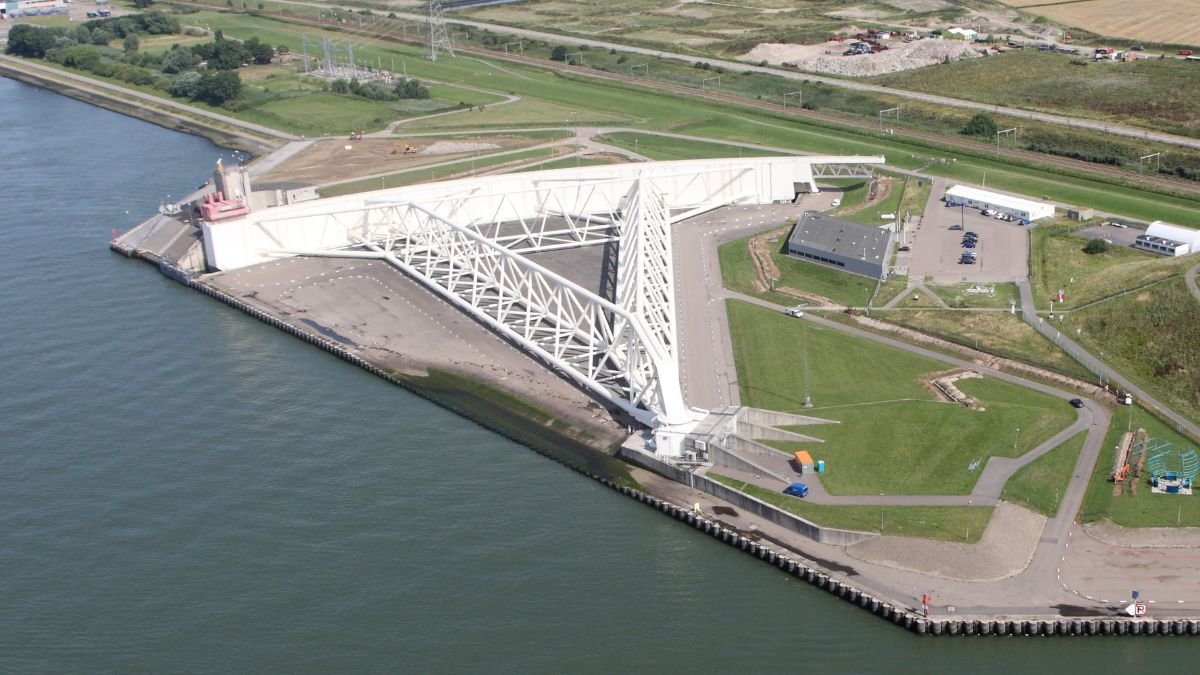
The Maeslantkering is the Netherlands’ giant movable flood barrier, protecting Rotterdam and South Holland while keeping one of Europe’s busiest ports open.

Sustainability
Solar Power Is Bringing More Electricity to Indian Farms. But What About the Water Beneath Them?
India’s solarisation drive is giving farmers more reliable and affordable electricity for irrigation. But as solar pumps expand, a new concern is emerging: could easier access to power accelerate groundwater extraction in regions where aquifers are already under stress? Evidence from Rajasthan and Gujarat suggests the answer depends on how solar irrigation is designed and managed.
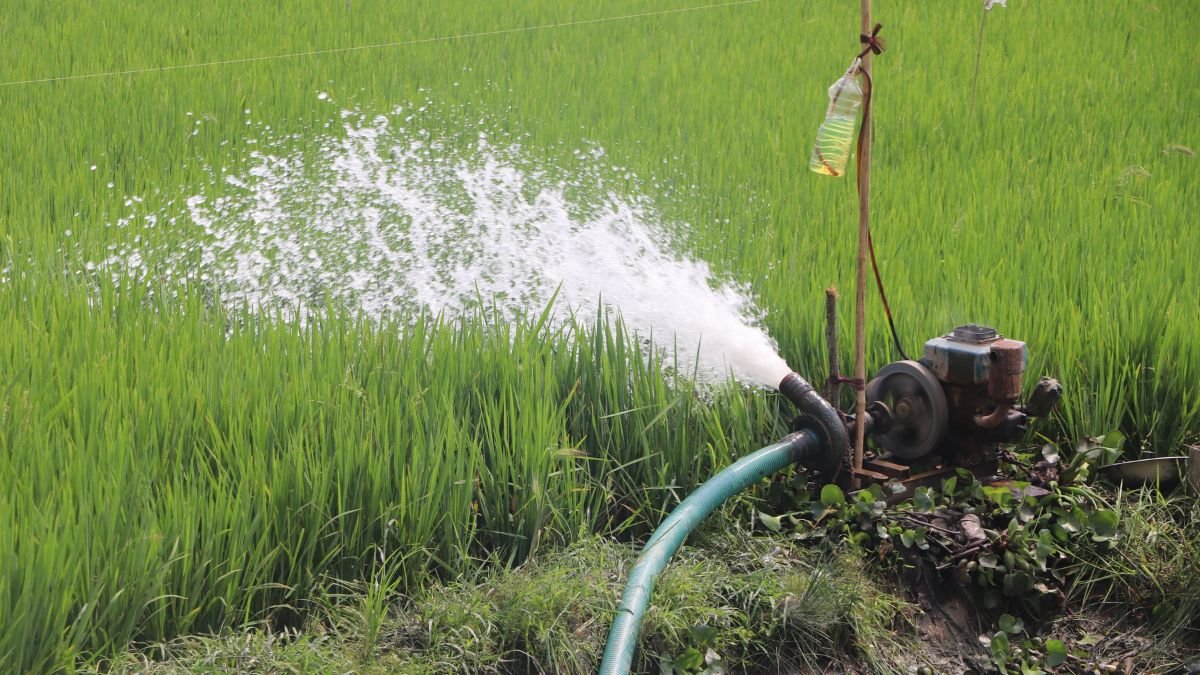
For years, electricity has been one of the biggest uncertainties in Indian farming. Farmers dependent on groundwater have often had to work around limited power supply, run diesel pumps or wait for electricity to arrive at odd hours. Solarisation is changing that equation. Through the Centre’s PM-KUSUM scheme, agricultural pumps are being converted to solar power and entire agricultural feeders are being solarised. The aim is to provide farmers with more reliable daytime electricity, reduce diesel use and lower the cost of agricultural power.
The change is significant. By 2025-26, around 25 lakh agricultural pumps had been installed or solarised under PM-KUSUM, while the programme had added 7.67 GW of solar capacity during the year. For a farmer, a solar pump can mean fewer hours spent waiting for electricity and greater control over irrigation. But there is a complication. Much of India’s irrigation already depends on groundwater. If solar power makes pumping cheaper and more reliable, farmers may have fewer reasons to stop pumping.
That creates a difficult question for India’s clean-energy transition: Can giving farmers more electricity to pump water also accelerate the depletion of the water they depend on? The answer is not a simple yes. Evidence from different parts of India shows that solarization can increase ground water extraction in some circumstances, while well-designed systems can also encourage farmers to use less water.
The difference lies in the incentives.
When the Energy Constraint Disappears
India has an enormous agricultural groundwater economy. About two-thirds of the country’s irrigation depends on groundwater, while India has an estimated 23 million agricultural pumps. Around three-quarters of these pumps are electric, according to recent research on solar irrigation.
For decades, electricity availability and the cost of pumping have acted as constraints on groundwater extraction. Solar pumps can weaken those constraints. Once the initial investment is made, the cost of running a solar pump is considerably lower than continuously buying diesel. In areas where electricity is subsidised, solarisation can similarly reduce the financial cost associated with irrigation.
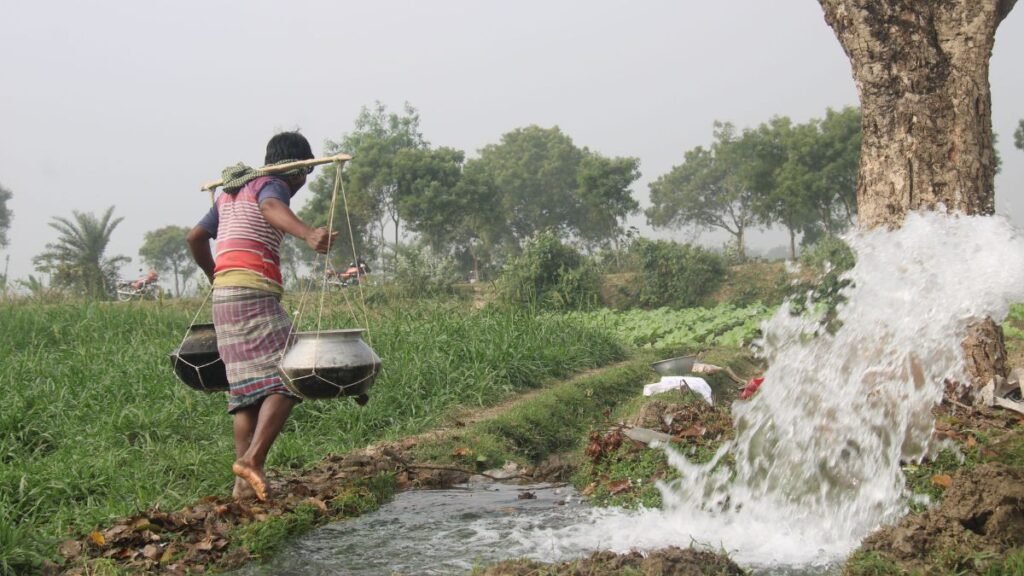
That can be good news for farmers. It can also encourage them to irrigate more land, grow additional crops or pump water for longer periods. Research from Rajasthan provides some evidence of this effect.
A study of 414 farmers across six districts found that solar-pump adoption increased groundwater consumption by 16–39% in Jaipur and Sikar. At the same time, farmers benefited from lower energy costs and higher farm incomes. The finding is important because it shows that groundwater depletion does not necessarily result from farmers making an environmentally harmful choice. They may simply be responding to a new economic reality. If irrigation becomes cheaper, using more water can make financial sense.
The Groundwater Problem is Already Severe
Solarisation is also arriving at a time when several parts of India are already extracting groundwater faster than their aquifers can sustainably provide it. The 2025 national groundwater assessment estimated India’s annual extractable groundwater resource at 407.75 billion cubic metres. Annual extraction stood at 247.22 billion cubic metres, putting the country’s overall stage of groundwater extraction at 60.63%.
But the national average hides the severity of the problem in several states. In 2025, the stage of groundwater extraction was estimated at: Punjab: (156%), Rajasthan: (147%), Haryana: (137%), Tamil Nadu: (74%), Uttar Pradesh: (70%), Karnataka: (66%) A figure above 100% indicates that annual groundwater extraction exceeds the state’s annual extractable groundwater resource.
At the national level, 730 of 6,762 groundwater assessment units were classified as over-exploited in 2025. This is why the location of a solar pump matters. A pump installed in an area with a healthy aquifer is not equivalent to one installed in a region where groundwater levels are already falling.
Rajasthan Offers a Warning
Rajasthan illustrates the tension particularly clearly. The state had a groundwater extraction stage of 147% in 2025. At the same time, it has become one of India’s major beneficiaries of solar irrigation programmes.
But it would be misleading to directly attribute Rajasthan’s groundwater crisis to solar pumps. Groundwater depletion in the state has deeper roots: intensive agriculture, rainfall variability, water-intensive cropping and decades of groundwater dependence all play a role. The significance of solarisation is different.
It can potentially remove one of the constraints on further extraction. The Rajasthan study found that solar-pump adopters increased groundwater consumption in some districts while also seeing substantial economic gains. In districts that had previously relied heavily on diesel, diesel consumption fell sharply after solar-pump adoption.
This is the paradox at the heart of the solar irrigation story. The technology can simultaneously make farming more sustainable in energy terms and less sustainable in water terms.
Gujarat Shows How Outcome can be Different
There is another side to the story. Research from Gujarat has found that solarisation does not necessarily lead to more groundwater extraction. A 2026 study examined grid-connected solar irrigation pumps in Anand and Botad, two areas with different aquifer conditions. In Anand, farmers using solar pumps actually used 556–608 mm less irrigation water than the comparison group across the two years studied. The reason is crucial. Farmers with grid-connected solar pumps could sell surplus electricity to the grid.
That creates a different economic calculation. Instead of using every available unit of electricity to pump water, a farmer has a financial incentive to conserve electricity—and therefore potentially water—and sell the surplus.
The same study found no significant difference in irrigation water use between solar and non-solar farmers in hard-rock Botad, where water availability itself was a stronger constraint. The lesson is not that solar pumps are either good or bad for groundwater. It is that the policy surrounding the pump determines much of the outcome.
The Missing Link: Energy Policy and Water Policy
India has already acknowledged the groundwater risks associated with solar irrigation. PM-KUSUM guidelines restrict the installation of new standalone solar pumps in groundwater-depleted areas identified as dark zones. In such areas, solarisation of existing electric pumps is subject to conditions including the adoption of micro-irrigation.
But the scale of India’s solarisation means that groundwater considerations cannot remain a safeguard attached to individual schemes. They need to become part of the planning process itself. That means asking three questions before expanding solar irrigation in a region:
How much solar capacity is being installed? How much groundwater is available? How much additional water could that energy make it possible to extract? Those questions are particularly important in states such as Punjab, Rajasthan and Haryana, where groundwater extraction is already above the annual extractable resource.
Solarisation could also be used to change farmers’ incentives rather than simply increase their pumping capacity. Electricity buyback, efficient irrigation, crop diversification and groundwater monitoring could make conserving water financially attractive.
The Transition Below the Ground
India needs more clean electricity in rural areas. Solar power can reduce diesel dependence, improve the reliability of agricultural power and give farmers greater control over irrigation. Those are real gains. But electricity and water are not separate systems on a farm.
The same solar panel that produces clean energy can power a pump drawing hundreds of litres of groundwater from an aquifer. Whether that becomes a problem depends on how much water is available, what crops are being grown, how efficiently water is used and what incentives farmers face.
The evidence from Rajasthan suggests that cheap solar pumping can increase groundwater use. The evidence from Gujarat suggests that a different policy design can encourage farmers to conserve water instead. So the question for India’s solarisation drive is no longer simply how many pumps can be solarised.
It is whether the country can make sure that the electricity transition above the ground does not quietly deepen the water crisis below it. India may have solved part of its rural power problem. The next challenge is making sure the solution does not come at the cost of its aquifers.


As AI Workers Warn of Risks, Researchers Seek Better Guardrails

India’s Data Centre Boom Is Bigger Than It Looks

Under Lalbagh: How a Botanical Garden Forced Bengaluru to Rethink Its Tunnel Road

August 2026 Was the Warmest Month on Record

Europe’s Cities Are Adapting to Climate Change Yet Is It Reaching Residents?

Farmers Borrowed to Build ‘Diggis’. Two Years Later, They Are Still Waiting for the Subsidy

Our Algorithm Knows What We Want Before We Do. That is the Problem.

The new skill revolution

Sophie Adenot Makes History as First Frenchwoman to Walk in Space

When Decarbonisation Becomes the Real Conversation at Tiruppur’s Knit Show
-

 Math2 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
Climate2 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
Society2 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics4 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Climate3 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society2 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society3 months ago
From Bell Labs to the Classroom: A Second Career in Teaching
-
Space & Physics3 months ago
Engineers Develop Dual-Mode Propulsion System for Next-Generation Small Satellites