Climate
Are India’s FTAs Becoming Climate Policy by Default? The CBAM Challenge
The climate impact of FTAs is reshaping India’s trade strategy as EU carbon rules like CBAM alter market access and industrial competitiveness.








Climate
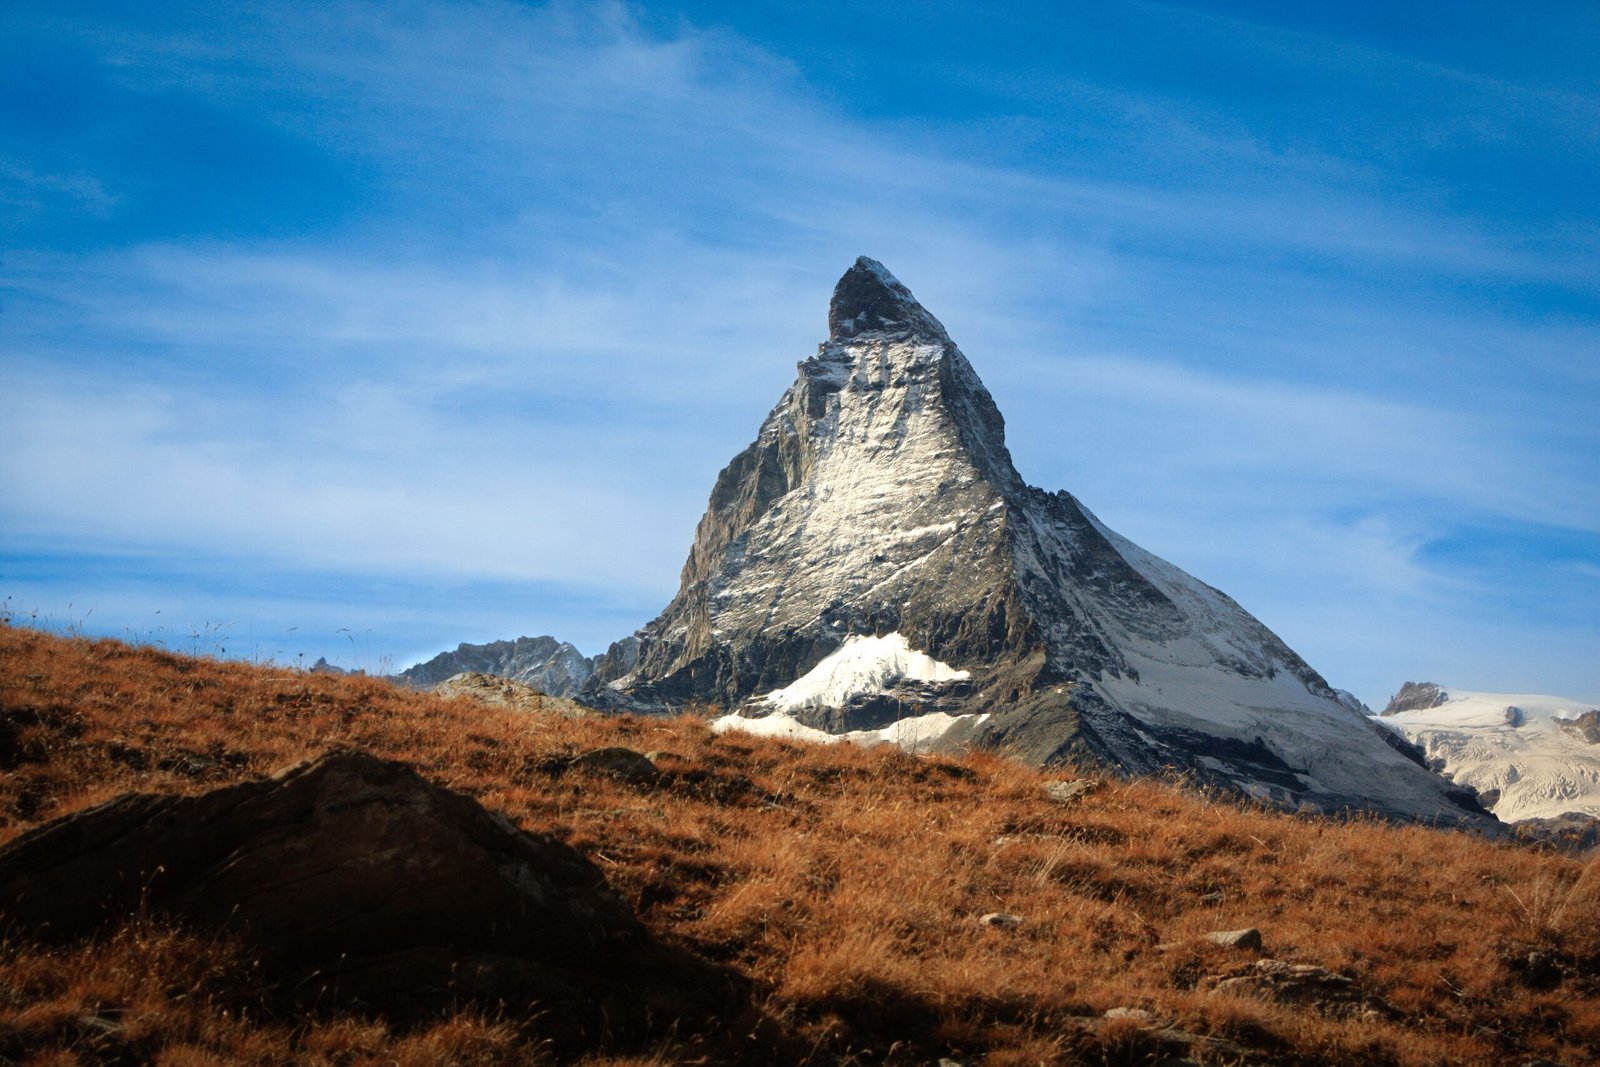
Icnoic Matterhorn Almost Snow-Free as Record Heat Accelerates Swiss Glacier Loss
The Matterhorn is almost snow-free after an exceptionally hot, dry summer, as Switzerland’s glaciers record another year of severe ice loss.
Climate
Climate Change Is Already on Your Dinner Table. Here Is How It Got There
Climate change is already affecting what food costs. From heatwaves and droughts to weaker crop yields, extreme weather is disrupting food markets and making staples such as potatoes, tomatoes and other vegetables more price-sensitive.

From heatwaves in the field to prices in the market, extreme weather is changing what food costs. Perishable foods such as vegetables are especially exposed, and India’s coming potato season is one to watch.
What does climate change have to do with the tomatoes in your salad or the potatoes on your plate? More than it may seem.
Climate change is not only about rising temperatures or intense rainfall. Its effects also move through farms and food markets and, eventually, into our kitchens. Heatwaves, droughts and uneven weather are disrupting the food system. People already stretched by work and the cost of living then find that food has become dearer still.
The result is a climate story that is easy to overlook because it shows up in an ordinary place: the dinner table.
A growing body of research is beginning to map the journey from climate shock to food price. A September 2026 analysis by Zero Carbon Analytics found that extreme climate events are raising agricultural risks, disrupting food systems and pushing up food prices. It also highlights the vulnerability of perishable, nutrient-dense foods, naming tomatoes in the Mediterranean among the affected commodities.
That matters because the climate-food connection is not simply about whether there will be enough calories on the planet. It is also about what those calories cost and what people can afford to eat.
The problem starts in the field
A 2021 study in the Journal of Environmental Economics and Management examined global yields of major calorie crops, using gridded agricultural data and climate-model projections. The researchers found that, without adaptation beyond what farmers have historically managed, climate change could cut global crop yields by 3–12 per cent by the middle of the century and by 11–25 per cent by the end of it, under a vigorous warming scenario. They also found that farmers’ historical adaptation has only slightly softened the effects of weather shocks across broad regions.
That does not mean every crop, country or farm will see the same decline. Impacts vary with crop type, location, irrigation and local conditions. But the research points to a larger problem: agriculture cannot be separated from a changing climate. The study covers staple calorie crops rather than vegetables, and the humble potato offers a closer example.
Why potatoes are vulnerable
Potatoes may look ordinary, but growing them depends on a narrow combination of temperature and water. The Intergovernmental Panel on Climate Change (IPCC) cites modelling that projects global potato-yield reductions of 2–6 per cent by 2055, though the impact varies considerably between regions. In some marginal growing areas the projected fall in tuber dry weight is much larger, while some high-yielding environments could see gains.
The same assessment cites modelling in which potato yields fall by about 4.6 per cent for every 1°C rise in temperature, and by about 2 per cent for every 10 per cent fall in rainfall at non-irrigated sites.
For India, this makes the coming potato season worth watching.
A 2025 study in Environmental Research Letters found that potato prices in India rose by about 81 per cent between April and June 2024, compared with the same period a year earlier, after an unusually severe heatwave in May. Onion prices rose by 89 per cent over the same period.
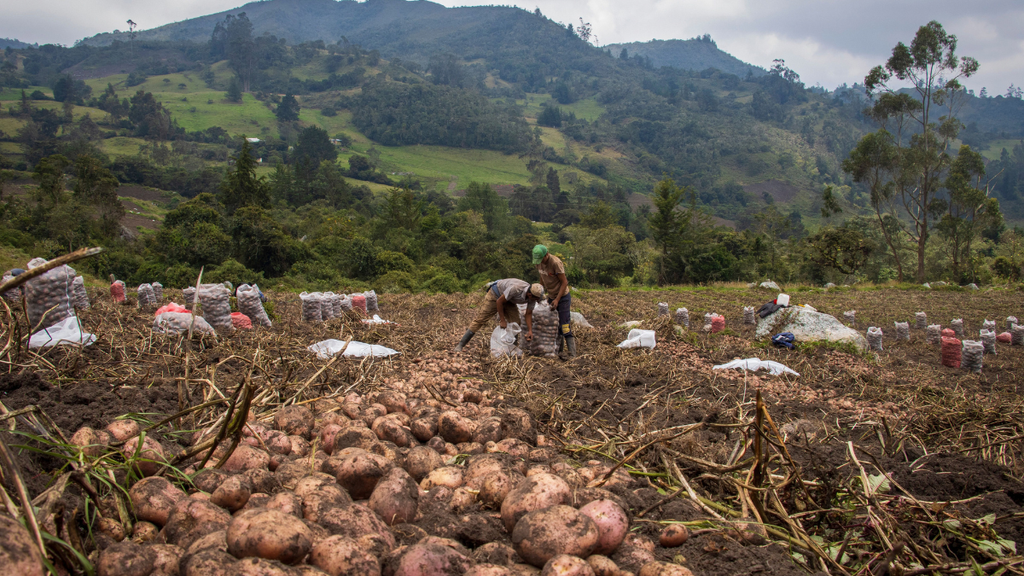
Farmers harvesting potatoes.Image credit:Pexels
This year’s southwest monsoon has been weak. India had received about 86 per cent of its normal rainfall by 29 August, according to India Meteorological Department data, and Bihar, an important potato-producing state, was running about 40 per cent below normal at the end of the month.
Analysts caution, however, that this does not amount to a confirmed national loss in potato production. The main risk is what the shortfall leaves behind: lower soil moisture, weaker groundwater recharge and higher irrigation needs before the winter crop is planted.
Nor have the shops felt it yet. Official consumer-price data for August 2026 show potato prices 13.14 per cent lower than a year earlier and tomato prices 31.09 per cent lower, although onions were 48.27 per cent dearer.
That distinction matters. Climate science can identify elevated risks; it does not mean every weather event automatically produces a specific crop loss or price rise.
How climate shocks reach the market
Tomatoes illustrate another part of the problem. Fresh vegetables are particularly exposed to climate shocks because they are perishable and have limited storage windows.
Zero Carbon Analytics counts tomatoes among the foods whose prices have been affected by recent climate extremes, and points to wider evidence that extreme weather can produce sharp price movements in nutrient-dense foods.
The Environmental Research Letters study also examined reported food-price spikes associated with extreme heat, drought and heavy rainfall. The examples are striking. South Korean cabbage was 70 per cent dearer in September 2024 than a year earlier. Vegetable prices in China rose 30 per cent between June and August 2024. In the United States, extreme heat and drought in California and Arizona contributed to an 80 per cent year-on-year rise in vegetable producer prices by November 2022.
In southern Europe, drought was associated with a 50 per cent year-on-year rise in olive-oil prices by January 2024. Global cocoa prices rose by almost 300 per cent by April 2024 compared with a year earlier, after a heatwave in Ghana and Côte d’Ivoire.
These figures should not be read as saying that climate change alone caused every increase. The researchers note that demand, transport disruptions, speculation and other socioeconomic factors can also shape the final price. But their analysis shows how extreme climate conditions can trigger food-price shocks.
From the farm to inflation
The consequences do not necessarily stop at the market. Research by economists at the European Central Bank and the Potsdam Institute for Climate Impact Research, published in Communications Earth & Environment in 2024, examined how global warming and extreme heat can feed into inflation. Under projected 2035 conditions, the study estimates that annual food inflation could rise by 0.92–3.23 percentage points a year on average globally, depending on emissions scenarios, climate models and empirical specifications.
The researchers also estimate that Europe’s extreme summer heat of 2022 raised food inflation by 0.43–0.93 percentage points, and that warming projected for 2035 would amplify the effect of similar extremes by 30–50 per cent.
When food prices rise, people on lower incomes have less room to absorb the increase. The Environmental Research Letters study notes that households may respond by spending more of their income on food, buying less food or switching to cheaper and often less nutritious options.
What ends up on the plate?
The World Food Programme (WFP) estimated on 5 August that the 2026–27 El Niño could push at least 49 million more people into acute food insecurity by the end of 2027, across the 45 countries it assessed. Those are countries already considered food insecure and where El Niño is expected to have a significant effect. The number of acutely food-insecure people in them could rise from about 225 million to 274 million.
And as the climate warms, the concern is not simply whether a tomato or potato will disappear from the plate.
It is whether climate shocks will make food production more uncertain, prices more volatile and nutritious diets harder to afford.
Climate
India Records Driest Monsoon in 11 Years as Rainfall Deficit Hits 12.6%
India’s southwest monsoon ended 12.6% below normal, making 2026 the driest monsoon in 11 years, according to the IMD.
India has ended the 2026 southwest monsoon with its lowest seasonal rainfall, driest monsoon in 11 years, with the country receiving 759.4 mm between June and September against a long-period average of 868.6 mm. The 12.6% deficit makes this the weakest monsoon since 2015 and the fourth-lowest since 2001, according to the India Meteorological Department (IMD).
The national figure, however, masks a much more uneven rainfall season. While some parts of the country received close to normal rainfall, large parts of eastern, northeastern and southern India experienced significant shortages.
Rainfall Shortfall Concentrated in Regions
The East and Northeast region recorded rainfall at about 74% of its long-period average, while South Peninsular India received about 76% of its average rainfall. The East and Northeast had their lowest southwest monsoon rainfall since 1901, while South Peninsular India recorded its second-lowest monsoon rainfall since 2001.
Of India’s 36 meteorological subdivisions, 17 recorded deficient rainfall, covering around 42% of the country’s geographical area. Another 18 subdivisions recorded normal rainfall. At the district level, 282 districts, or around 38% of the country’s districts, ended the season with deficient rainfall.
The uneven distribution matters because a national rainfall average does not translate into the same water availability everywhere. A district that receives normal rainfall cannot compensate for prolonged deficits in another region where agriculture, reservoirs or groundwater depend heavily on the monsoon.
Driest Monsoon: June’s Deficit Set the Tone
The shortfall was particularly pronounced at the beginning of the season. June rainfall was 35.4% below normal, followed by a 16.3% deficit in August and a 7.6% deficit in September. July was the exception, recording around 1% above normal rainfall.
The season also saw unusually frequent low-pressure systems. Fourteen such systems formed during the monsoon, producing 77 low-pressure-system days compared with the normal 57. According to IMD Director General Mrutyunjay Mohapatra, these systems helped prevent the seasonal deficit from becoming larger.
This uneven pattern is important for agriculture. A season can produce a near-normal rainfall total while still leaving crops exposed if rain arrives too late, falls in short intense spells or remains absent during critical stages of crop growth.
What does it Mean for Agriculture?
The immediate concern now shifts from kharif crops to the water conditions entering the rabi season. Lower rainfall can reduce soil moisture and leave rain-fed farming regions more dependent on stored water or irrigation. The impact will vary by crop and region rather than follow the national rainfall deficit directly.
The IMD had warned ahead of the monsoon that below-normal rainfall could create challenges for agriculture, water availability and hydropower, while increasing pressure on drinking-water resources.
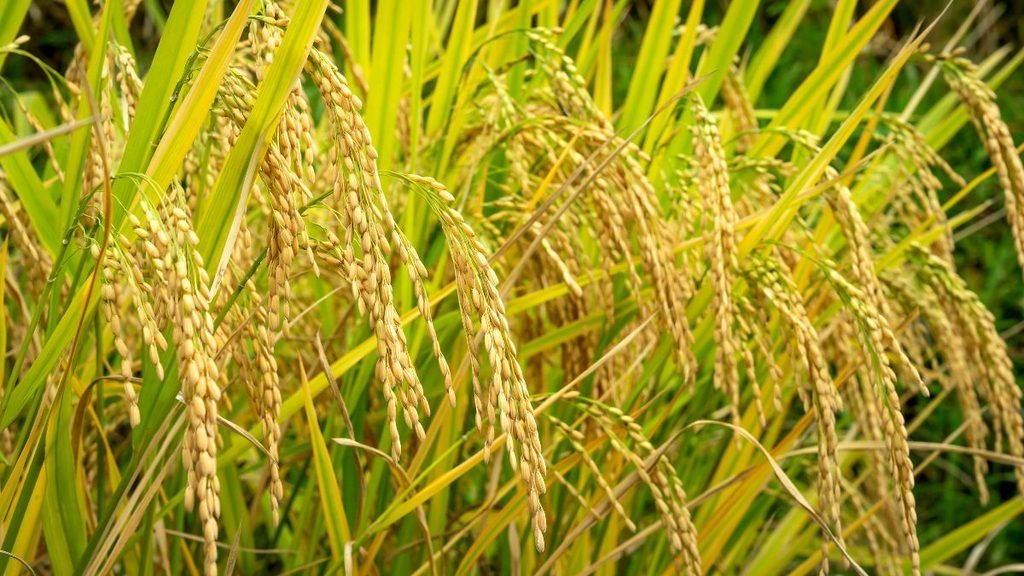
The agricultural impact is already visible in some indicators. Kharif sowing stood at 110.8 million hectares as of September 25, about 1.2% below the previous year, while rice acreage was down 3.6%. Pulses, meanwhile, recorded an increase in acreage. The next concern is therefore not simply how much rain India received, but how much usable water remains available for farms, households and other sectors through the coming months.
El Niño Added Pressure
The weak monsoon developed alongside El Niño conditions in the tropical Pacific. The IMD had anticipated this risk before the season, forecasting in May that 2026 monsoon rainfall could be around 90% of the long-period average, with a model error of ±4%. It also gave a 60% probability of rainfall being in the deficient category.
By the end of the season, the IMD said El Niño conditions had strengthened and contributed to the rainfall deficit. The weather system is expected to persist into the coming months, although its influence on rainfall varies across regions and seasons.
The relationship between El Niño and the Indian monsoon is not absolute. Government data notes that, since 1950, there have been 16 El Niño years, of which seven were associated with below-normal Indian monsoon rainfall. The strength and timing of El Niño also influence its effect. The monsoon has ended, but the water story has not
The IMD expects October rainfall to remain below normal nationally, adding another layer of uncertainty after an already deficient southwest monsoon.
For India, the significance of the 2026 monsoon will therefore extend beyond the final 12.6% deficit. The more important questions are regional: which reservoirs have been replenished, where groundwater has taken a hit, how rain-fed farmers are entering the rabi season and whether drinking-water systems have enough buffer for a potentially drier post-monsoon period. The season is a reminder that rainfall totals alone cannot describe India’s water security. What matters on the ground is where the rain fell, when it fell and how much of it could be stored and used after the clouds cleared.


Icnoic Matterhorn Almost Snow-Free as Record Heat Accelerates Swiss Glacier Loss

Who Cares for India’s Older People?

Climate Change Is Already on Your Dinner Table. Here Is How It Got There

India Records Driest Monsoon in 11 Years as Rainfall Deficit Hits 12.6%

Not Broken but Unheld: A New UN Report Asks Us to Tend the Forest, Not Only the Tree

From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story

Farmers Borrowed to Build ‘Diggis’. Two Years Later, They Are Still Waiting for the Subsidy

Aim for the Stars: Anjali Thomas’s Journey from a Small College in Kerala to the Frontiers of Medical Imaging

Anxiety Freezes Career Decisions. Curiosity Unfreezes Them

The Engineer of Tomorrow Is Already Here
-

 Math2 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
Climate2 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
Society3 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics4 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews1 week ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate4 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society3 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society4 months ago
From Bell Labs to the Classroom: A Second Career in Teaching