Society
The Dragon and the Elephant Dance for a Cleaner World
New reports from the IEA and Ember show that China and India are leading a global turning point — where renewables now outpace fossil fuels.

In late September, EdPublica reported an inspirational story from Perinjanam, a quiet coastal village in the South Indian state Kerala, where rooftops gleam with solar panels and homes have turned into micro power plants. It was a story of how ordinary citizens, through community effort and government support, took part in a just energy transition.
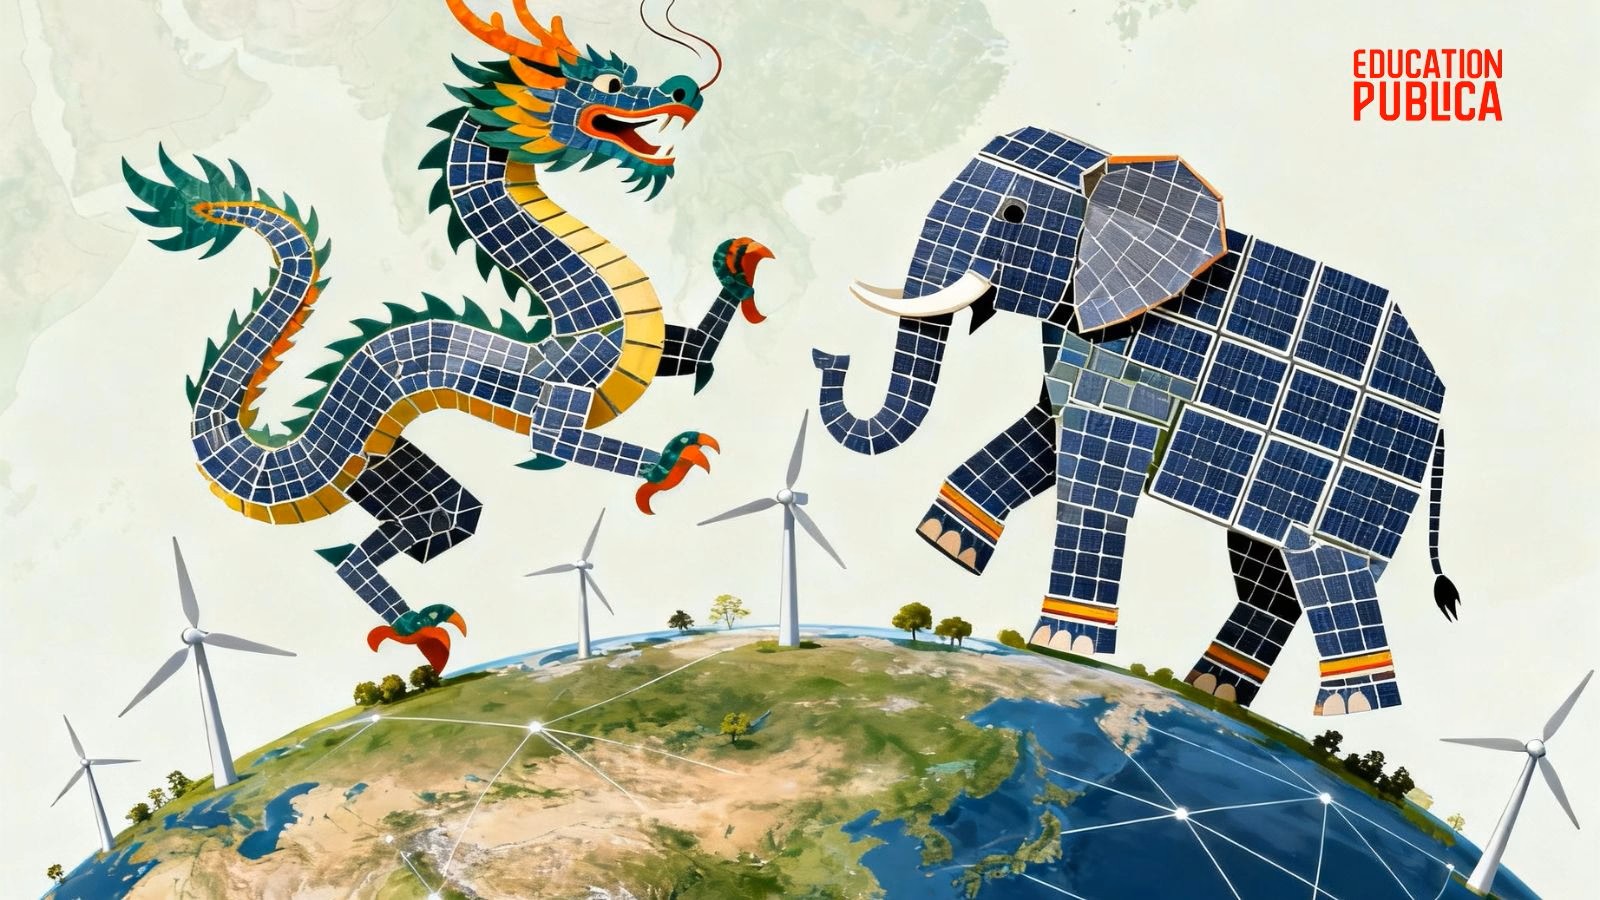
That local story, seemingly small, was in fact a mirror of a far bigger movement unfolding worldwide. Now, two major global reports–one from the International Energy Agency (IEA) and another from the independent think tank Ember–confirm that the world is entering a decisive new phase in its energy transformation. Together, their findings show that 2025 is shaping up to be the turning point year: the moment when renewables not only surpassed coal but began meeting all new global electricity demand. The year will likely be remembered as the moment when the global energy transition stopped being a promise and became a measurable reality — led by the two Asian giants, China and India.
The Global Picture: IEA’s Big Forecast
‘The IEA’s Renewables 2025’ report, released on October 7, paints an extraordinary picture of growth and possibility. Despite global headwinds — including high interest rates, supply chain bottlenecks, and policy shifts — renewable energy capacity is projected to more than double by 2030, adding 4,600 gigawatts (GW) of new renewable power.
To grasp that number: it’s equivalent to building the entire current electricity generation capacity of China, the European Union, and Japan combined.
At the centre of this boom is solar photovoltaic (PV) technology, which will account for around 80% of the total growth. The IEA calls solar “the backbone of the energy transition,” driven by falling costs, faster permitting processes, and widespread adoption across emerging economies. Wind, hydropower, bioenergy, and geothermal follow closely behind, expanding capacity even as global systems adapt to higher shares of variable power.
“The growth in global renewable capacity in the coming years will be dominated by solar PV – but with wind, hydropower, bioenergy and geothermal all contributing, too,” said Fatih Birol, Executive Director of the IEA. “As renewables’ role in electricity systems rises in many countries, policymakers need to play close attention to supply chain security and grid integration challenges.”
The IEA forecasts particularly rapid progress in emerging markets. India is set to become the second-largest renewables growth market in the world, after China, reaching its ambitious 2030 targets comfortably. The report highlights new policy instruments — such as auction programs and rooftop solar incentives — that are spurring confidence across Asia, the Middle East, and Africa.
In India, the expansion of corporate power purchase agreements, utility contracts, and merchant renewable plants is also driving a quiet revolution, accounting for nearly 30% of global renewable capacity expansion to 2030.
At the same time, challenges remain. The IEA points to a worrying concentration of solar PV manufacturing in China, where over 90% of supply chain capacity for key components like polysilicon and rare earth materials is expected to remain by 2030.
Grid integration is another bottleneck. As solar and wind grow, many countries are already facing curtailments — when renewable power cannot be fed into the grid due to overload or mismatch in demand. The IEA stresses the need for urgent investment in transmission infrastructure, storage technologies, and flexible generation to prevent this momentum from being wasted.
Evidence on the Ground
If the IEA’s report is a map of where we’re going, Ember’s Mid-Year Global Electricity Review 2025 shows where we are right now — and the signs are unmistakable.
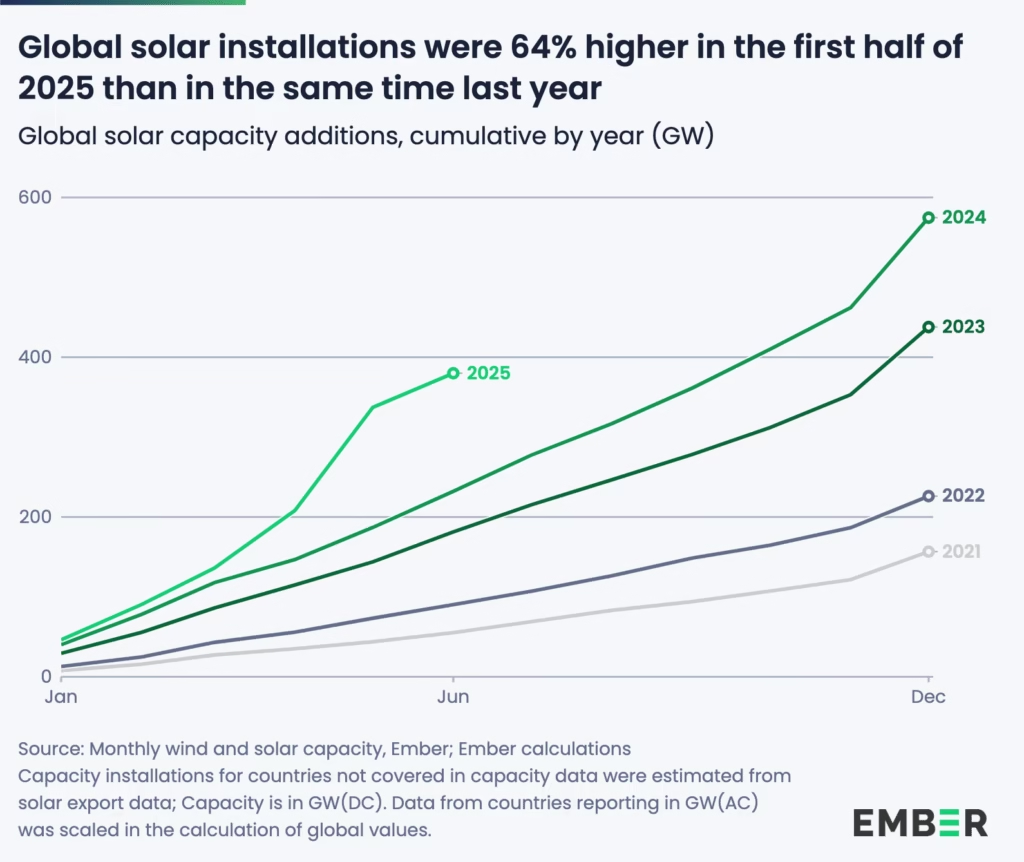
Ember’s data, covering the first half of 2025, reveals that solar and wind met all of the world’s rising electricity demand — and even caused a slight decline in fossil fuel generation. It’s a first in recorded history.
“We are seeing the first signs of a crucial turning point,” said Małgorzata Wiatros-Motyka, Senior Electricity Analyst at Ember. “Solar and wind are now growing fast enough to meet the world’s growing appetite for electricity. This marks the beginning of a shift where clean power is keeping pace with demand growth.”
Global electricity demand rose by 2.6% in early 2025, adding about 369 terawatt-hours (TWh) compared with the same period last year. Solar alone met 83% of that rise, thanks to record generation growth of 306 TWh, a year-on-year increase of 31%. Wind contributed another 97 TWh, leading to a net decline in both coal and gas generation.
Coal generation fell 0.6% (-31 TWh) and gas 0.2% (-6 TWh), marking a combined fossil decline of 0.3% (-27 TWh). As a result, global power sector emissions fell by 0.2%, even as demand continued to grow.
Most significantly, for the first time ever, renewables generated more power than coal. Renewables supplied 5,072 TWh, overtaking coal’s 4,896 TWh — a symbolic but historic milestone.
“Solar and wind are no longer marginal technologies — they are driving the global power system forward,” said Sonia Dunlop, CEO of the Global Solar Council. “The fact that renewables have overtaken coal for the first time marks a historic shift.”
China and India Lead the Way
The two reports together highlight that the epicenter of the clean energy shift is now in Asia.
According to Ember, China’s fossil generation fell by 2% (-58.7 TWh) in the first half of 2025, as clean power growth outpaced rising electricity demand. Solar generation jumped 43% (+168 TWh), and wind grew 16% (+79 TWh), together helping cut the country’s power sector emissions by 1.7% (-47 MtCO₂).
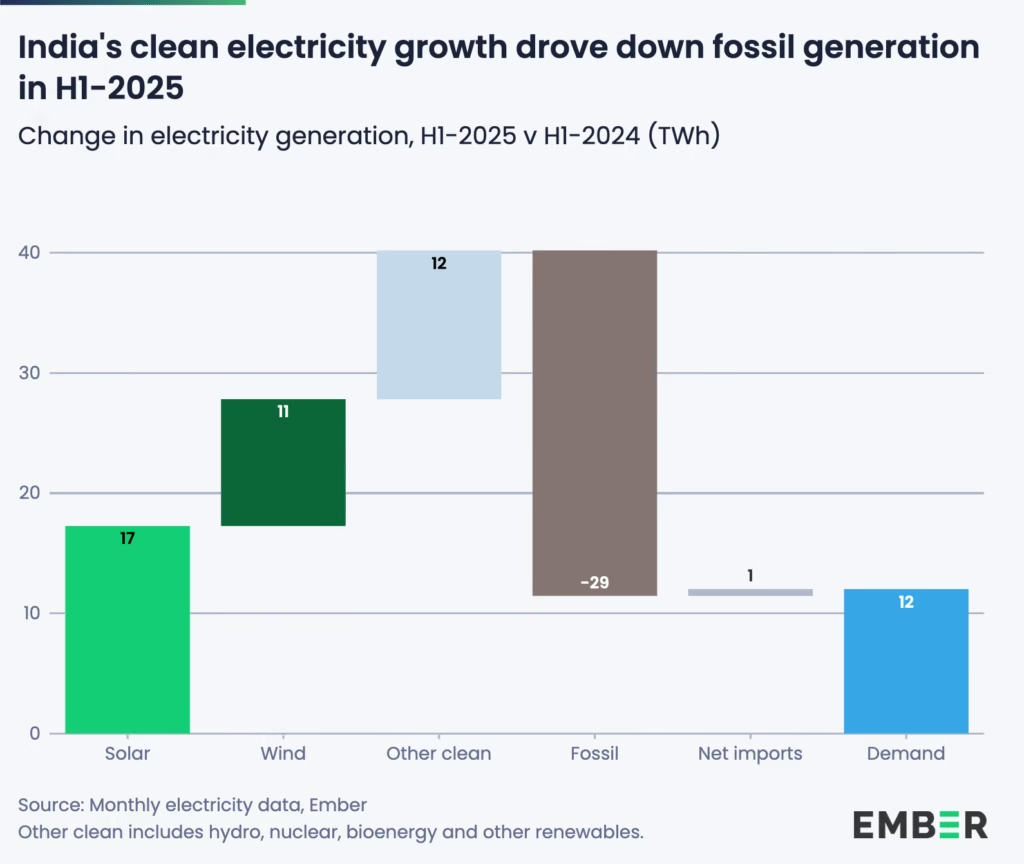
Meanwhile, India’s fossil fuel decline was even steeper in relative terms. Solar and wind generation grew at record pace — solar by 25% (+17 TWh) and wind by 29% (+11 TWh) — while electricity demand rose only 1.3%, far slower than in 2024. The result: coal use dropped 3.1% (-22 TWh) and gas by 34% (-7 TWh), leading to an estimated 3.6% fall in power sector emissions.
For both countries, these numbers align closely with the IEA’s projections. Together, China and India are now the primary engines of renewable capacity growth, demonstrating how large emerging economies can pivot toward clean energy while maintaining development momentum.
Setbacks Elsewhere
Yet progress is uneven. In the United States and European Union, fossil generation actually rose in early 2025.
In the U.S., a 3.6% rise in demand outpaced clean power additions, leading to a 17% increase in coal generation (+51 TWh), though gas use fell slightly. The EU also saw higher gas and coal use due to weaker wind and hydro output.
The IEA attributes part of this slowdown to policy uncertainty, especially in the U.S., where an early phase-out of federal tax incentives has reduced renewable growth expectations by almost 50% compared to last year’s forecast. Europe’s problem is different — a mature but strained grid facing seasonal fluctuations and low wind output.
These regional discrepancies underscore the IEA’s core message: achieving a clean power future isn’t just about building more solar farms, but about building smarter systems — integrated, flexible, and resilient.
Beyond Power
Both reports agree that while renewables are transforming electricity, their impact on transport and heating remains limited.
In transport, the IEA projects renewables’ share to rise modestly from 4% today to 6% in 2030, mostly through electric vehicles and biofuels. In heating, renewables are set to grow from 14% to 18% of global energy use over the same period.
These slower-moving sectors will define the next frontier of decarbonization — one where electrification, hydrogen, and new thermal storage technologies must play a greater role.
The Big Picture
Put together, the IEA’s forecasts and Ember’s real-world data signal that the clean energy transition has passed the point of no return.
Solar and wind are no longer simply catching up — they are now shaping global power dynamics. Their continued expansion is not only meeting new demand but beginning to displace fossil fuels outright.
“As costs of technologies continue to fall, now is the perfect moment to embrace the economic, social and health benefits that come with increased solar, wind and batteries,” said Ember’s Wiatros-Motyka.
Yet both agencies caution: to sustain this momentum, governments must expand grid capacity, diversify supply chains, and improve energy storage systems. Without these, the 2025 breakthrough could become a bottleneck.
A Symbol and a Signal
In a way, the world in 2025 looks a lot like Perinjanam did a few years ago — a place where optimism met obstacles, but the light won. What was once a village-scale transition is now a planetary transformation, proving that even small local models can foreshadow global change.
From Kerala’s rooftops to China’s vast solar parks, from India’s wind corridors to Africa’s mini-grids, the direction is unmistakable: the sun and wind are powering the next phase of human progress.
If 2024 was the year of warnings, 2025 is the year of evidence. The global energy system is finally tilting toward sustainability — not someday, but today.






Books
The Science of Selling: How Sudheer Babu Decodes Buyer Psychology in ‘The Revenue Multiplier’
A review of Sudheer Babu’s The Revenue Multiplier, exploring how behavioural science and buyer psychology can shape smarter, ethical sales.

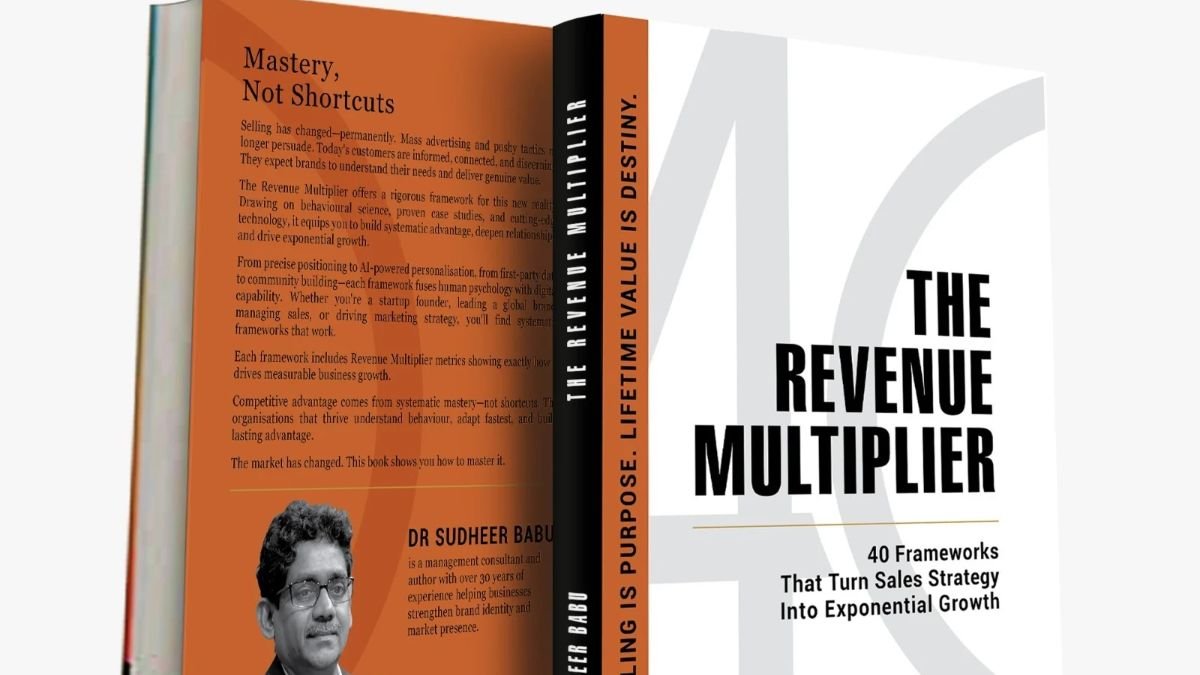
The Revenue Multiplier, by Dr. Sudheer Babu, is a book about why people buy and how a business can sell with that in mind. Its premise is that behavioural science should be the foundation of growth, not an afterthought. In each chapter, Babu starts with a psychological mechanism, explains how it shapes a buyer’s decision, and then turns that insight into a commercial action. He applies this method consistently, and that consistency is the book’s main strength.
The Revenue Multiplier: How Behavioural Science Shapes Sales
The book’s opening case shows the approach. Using BJ Fogg’s Behaviour Model, Babu explains that a behaviour occurs when motivation, ability and a prompt converge. In Babu’s telling, Maggi’s two-minute cooking time raised the ability to act enough to offset a family’s low motivation to abandon traditional food habits. The child’s hunger, he says, was the prompt. Babu then notes that the vegetables added to the packet let families see the snack as a proper meal. This is the compensatory principle at work: simplicity can outweigh reluctance.
Framing comes next. Babu draws on the framing effect, which shows that the way information is presented changes what people perceive and decide. He contrasts fear-based safety messages with affirmative ones, and he shows how a brand can shape the picture a buyer carries into a decision.
The chapter on the Reactance Trap shows the method most clearly. Drawing on Jack W. Brehm’s 1966 work, Babu argues that a buyer who feels pressured resists in order to protect their freedom to choose. His remedy is respectful: tell the customer plainly that the final decision is theirs. He also reminds readers that resistance can appear in different forms across cultures, as delayed decisions or silence, so the approach must be adapted to local norms.
The chapters on decision architecture build on this. Babu applies the primacy and recency effects to the order of presentations and uses anchoring, a finding documented by Amos Tversky and Daniel Kahneman, to show how the first price a buyer sees shapes every price that follows. His decoy example, which uses a plan priced close to a premium option but with fewer features, illustrates asymmetric dominance. These are familiar tools of behavioural economics. Babu presents them as design choices, not tricks.
Loss aversion and scarcity work on the same logic. A limited-time offer can work because the fear of losing an opportunity can outweigh the gain. The endowment effect explains why a virtual try-on or a personalised summary can raise the perceived value of a product before purchase.
The book also covers choice overload, in which more options make a decision harder. It treats positioning as a question of processing fluency: a brand that is easy to understand is easier to remember and trust. Babu’s baker who tries to sell everything, and so becomes known for nothing, makes the point well.
Influence principles from Robert Cialdini run through the sales chapters. A two-step lead funnel uses reciprocity, offering a small gift after a simple first response. Authority and liking explain why endorsements by admired figures carry weight, and social proof explains how that trust spreads through a network.
The book also leaves some questions for the reader. Behavioural effects such as choice overload, decoy pricing and scarcity do not work the same way in every market or with every kind of buyer, and a review of this length cannot test Babu’s commercial claims. His examples, Maggi included, are best read as a source of hypotheses to try with real customers rather than as guaranteed levers.
Babu is careful about how these tools should be used. The book calls his approach ‘smart design, not manipulation’, and it warns that artificial scarcity damages trust once it is exposed. Readers who want to understand buyers, rather than simply pressure them, will find it a clear, practical and humane guide.
The book is available in Kindle and print editions through Amazon. The print edition is also distributed internationally through IngramSpark and available from Kerala Bookstore.
Society
India’s Farm Subsidies Fail to Offset Price Pressures on Farmers, OECD Report Finds
India’s agricultural support system faces scrutiny after a new OECD report found that market regulations and trade restrictions continue to depress prices received by farmers, despite substantial government subsidies. The findings raise questions about the effectiveness of farm support policies, public investment and the sustainability of agricultural growth.

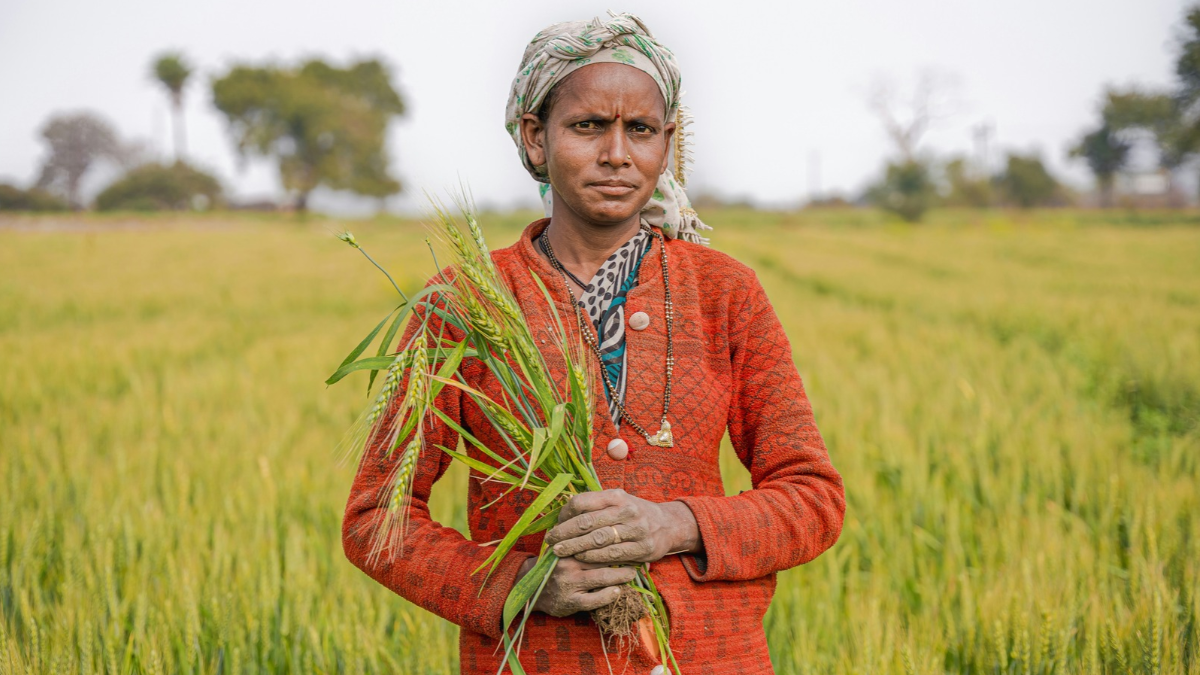
India’s agricultural support system presents a striking contradiction: the government spends substantial sums on subsidies and income-support programmes, yet its policies continue to impose an implicit financial burden on farmers. A new assessment by the Organisation for Economic Co-operation and Development (OECD) finds that India’s net support to agricultural producers remained negative during 2023–25, suggesting that budgetary payments did not compensate for the price-depressing effects of domestic marketing regulations and trade policies.
The Agricultural Policy Monitoring and Evaluation 2026, released on November 2, estimates India’s Producer Support Estimate (PSE) at an average of -9.2% of gross farm receipts during 2023–25. The negative figure indicates that agricultural policies, taken together, reduced the prices producers received compared with international reference prices, even after accounting for direct government support.
The finding draws attention to a structural problem in India’s agricultural policy: support delivered through subsidies can be undermined by policies that influence how crops are marketed, priced and traded.
The gap between subsidies and prices
The OECD’s PSE is not a measure of the amount of money farmers receive from the government. It estimates the annual value of transfers to agricultural producers arising from policy measures, including direct payments and the difference between domestic and international market prices.
In India’s case, the report identifies both positive and negative market price support. Commodities receiving positive support recorded an average of 3.5% of gross farm receipts, while those facing negative support experienced price effects of as much as -23.4% during 2023–25.
The report attributes the overall negative estimate to a combination of domestic marketing regulations and trade policy measures. Restrictions on the export of rice, wheat, sugar, onions and related products during the assessment period are among the measures identified. Such interventions are often introduced to contain domestic food prices and protect consumers from inflation. However, when they restrict access to higher-priced international markets, they can also limit the prices producers receive.
India gradually relaxed several restrictions during 2025, including measures affecting rice exports. Nevertheless, the OECD argues that unpredictable restrictions make agricultural markets less certain and can discourage farmers, traders and businesses from investing in production and supply chains.
This presents a difficult policy balance. Governments need to protect consumers from sudden food-price increases, particularly low-income households, but interventions that repeatedly change market conditions can undermine price incentives for producers.
Agriculture’s economic importance
The implications extend beyond farm incomes. According to the OECD, agriculture accounted for 16.3% of India’s GDP in 2024 but employed 42.4% of the workforce. The disparity points to a significant productivity gap between agriculture and the rest of the economy.
The report also notes that farm incomes have grown at less than one-third the rate of non-agricultural incomes in recent years. Although agricultural output has expanded, a large share of the workforce continues to depend on a sector that contributes a considerably smaller share of national economic output.
India’s agricultural output grew at an average annual rate of 3.9% between 2014 and 2023, exceeding the global average. Total factor productivity grew by 1.5% annually during the period, supported by technological progress, improved seeds and infrastructure, including irrigation and roads.
However, output growth alone does not guarantee that gains reach farmers. The prices received for produce, the cost of inputs, access to markets and the distribution of value along supply chains all influence farm incomes.
The OECD’s findings therefore raise a question about whether India’s existing support mechanisms are sufficiently addressing the conditions that determine what farmers earn.
Where does government support go?
The report does not suggest that India has withdrawn financial support from agriculture. Budgetary transfers to producers averaged 10.7% of gross farm receipts during 2023–25. Much of this support, however, was directed towards variable input subsidies, particularly fertilisers, electricity and irrigation water.
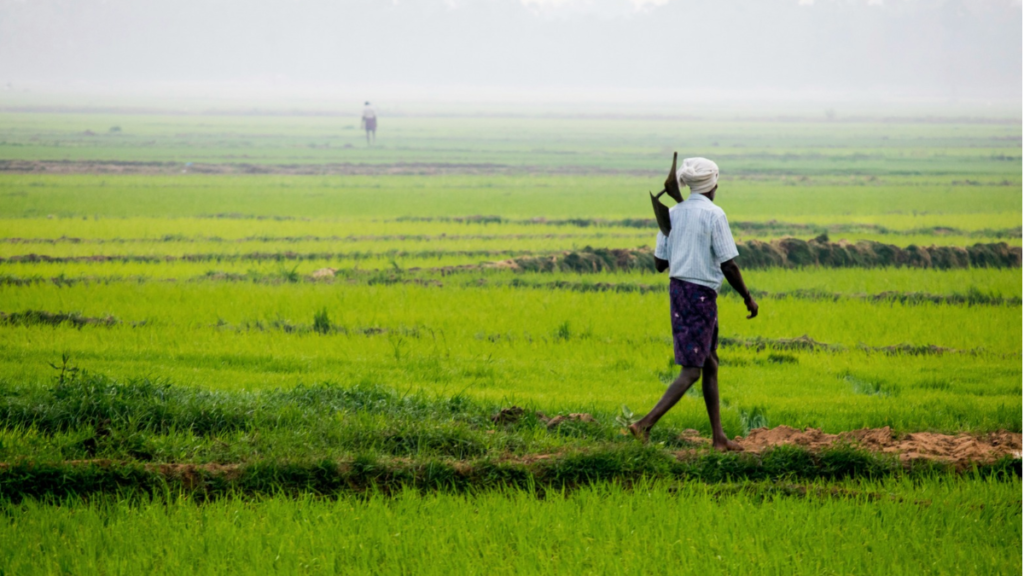
A farmer walking in a paddy field at early morning.Image credit:Pexels
These subsidies help farmers manage production costs and are politically significant, especially when input prices rise. The government continues to rely on them to maintain affordability and support agricultural production.
The scale of fertiliser assistance illustrates this dependence. On November 11, 2026, the Union Cabinet approved a nutrient-based subsidy allocation of ₹62,370 crore for phosphatic and potassic fertilisers for the October 2026–March 2027 winter cropping season. The allocation was approximately 64% higher than that for the previous winter season, reflecting pressures from international fertiliser prices and supply disruptions.
But input subsidies are not a substitute for investments that improve productivity over the long term. The OECD recommends gradually reducing inefficient fertiliser, electricity and irrigation-water subsidies and redirecting resources towards agricultural research, education, rural infrastructure, financial services, sustainable input use and climate resilience.
The distinction is important. Subsidising electricity or water consumption can provide immediate relief, but poorly designed subsidies may also encourage excessive use of resources. A transition towards more efficient support would need to protect small and vulnerable farmers while reducing incentives for wasteful consumption.
The environmental cost of agricultural growth
India’s productivity gains have also come with mounting pressure on natural resources. The OECD records an increase in the country’s nitrogen balance from 90.7 kg per hectare in 2000 to 133.4 kg per hectare in 2024. The phosphorus balance rose from 20.8 to 28.1 kg per hectare over the same period.
These indicators measure the difference between nutrients entering agricultural systems and those removed through harvested crops and other processes. Persistent surpluses can indicate inefficient fertiliser use and increase the risk of nutrient pollution in soil and water.
The report links rising fertiliser use and agricultural output to growing pressure on land and water resources. It argues that support policies should encourage more sustainable production rather than simply increase the volume of inputs used.
This is particularly relevant for India, where irrigation, fertiliser affordability and electricity subsidies are closely connected to agricultural production. Reforming these systems without adequate alternatives could increase costs for farmers. The challenge is therefore to improve efficiency without shifting the burden of transition onto those with the least capacity to absorb it.
Rethinking agricultural policy
The OECD recommends making agricultural trade more predictable by limiting ad hoc export restrictions and extending the Agricultural Export Policy framework to more products. It also calls for domestic marketing reforms that allow farmers and traders to respond more effectively to market demand.
Its broader recommendation is to shift public spending away from measures that distort production and trade towards investments in productivity, sustainability and resilience. Research, extension services, infrastructure and digital skills are identified as areas requiring greater attention.
The Economic Survey 2025–26 also identifies fragmented landholdings, limited access to irrigation and quality inputs, low mechanisation and insufficient investment as continuing constraints on Indian agriculture. It points to initiatives in agricultural extension, digital agriculture, farmer-producer organisations and market infrastructure as part of the policy response.
The OECD’s assessment should not be read as an argument against all subsidies or government intervention. Price stabilisation and food security remain important objectives in a country where millions of households depend on affordable food. But the report highlights the limitations of a system that supports farmers through input subsidies while simultaneously using market and trade controls that can depress the value of their produce.
The central policy question is no longer simply how much the government spends on agriculture, but whether that spending improves farmers’ capacity to earn, invest and adapt. For India, a more durable agricultural support system will require aligning price policy, market access, public investment and environmental sustainability rather than treating them as separate concerns.
Society
Intellectual disabilities linked to severe educational disadvantage in India, study finds
A new study published in Scientific Reports highlights significant educational disadvantages among people with intellectual and developmental disabilities and mental illness in India. Alongside school enrolment and infrastructure data, the findings underline persistent gaps in inclusive education, gender equality and access to learning support.
New Delhi: People with intellectual and developmental disabilities (IDD) in India face substantially greater educational disadvantages than those without disabilities, with gender and economic inequalities further widening the gap, according to a study published in Scientific Reports on October 15, 2026.
The research, analysed data from 402,994 adults using the 76th round of the National Sample Survey (NSS), conducted in 2018.
Researchers found that individuals with intellectual and developmental disabilities had a 71.3% predicted probability of receiving no formal education. The corresponding probability among people reporting mental illness was 48.3%.
The study also found that individuals with IDD had 28.9 times higher odds of receiving no formal education than those without disabilities. For individuals with mental illness, the odds were 3.3 times higher.
The findings highlight how disability-related barriers can translate into long-term educational exclusion, particularly when combined with poverty and gender discrimination.
Gender and economic inequalities compound exclusion
The researchers examined how educational disadvantages varied across gender and household economic groups.
Women with mental illness faced a particularly pronounced disadvantage. They were 18.7 percentage points more likely than men with mental illness to have received no formal education.
Economic circumstances also influenced educational outcomes. Among individuals with IDD, the predicted probability of receiving no formal education declined from approximately 79.9% in the poorest household group to 62.9% in the richest group.
For individuals with mental illness, the corresponding probability declined from approximately 59.9% to 33.5%.
However, economic advantage did not eliminate gender disparities. The researchers found that women with mental illness continued to experience educational disadvantages even in the wealthiest household category.
The study distinguishes between intellectual and developmental disabilities and mental illness, highlighting the importance of addressing their different educational and support requirements rather than treating them as a single category.
Enrolment figures reveal the scale of the challenge
The research findings gain significance when considered alongside India’s school-enrolment figures.
According to the Unified District Information System for Education Plus (UDISE+) data cited in a Lok Sabha response on March 30, 2026, approximately 1.91 million children with special needs were enrolled in government, government-aided and local-body schools during 2024–25.
The corresponding figure was approximately 1.93 million in 2023–24. Girls accounted for 827,521 of the enrolled children in 2024–25, representing approximately 43.4% of the total.
The figures indicate the scale of the population requiring inclusive educational support. However, enrolment alone does not establish whether children are receiving appropriate learning assistance, participating fully in classrooms or progressing through different levels of education.
Representational image.Image credit:Unsplash
Infrastructure and specialist support remain important components of inclusive schooling. The Ministry of Education’s Annual Report 2024–25 recorded that 11.34 lakh schools had ramps, 7.69 lakh had ramps with handrails and 5.06 lakh had children-with-special-needs-friendly toilets during 2023–24.
The government also reported 52,274 government, government-aided and local-body schools with special educators in 2024–25. These figures point to the need to assess not only school access but also the availability and distribution of trained personnel and accessible facilities.
Strengthening inclusive education
India’s Right of Children to Free and Compulsory Education Act, 2009, and the Rights of Persons with Disabilities Act, 2016, provide the legal framework for improving educational access for children with disabilities.
Under the Samagra Shiksha scheme, the government provides support through early identification, assessment, assistive devices, therapeutic interventions, transport allowances, resource support and individualised learning assistance.
The scheme also provides a stipend of Rs 200 per month for ten months to eligible girls with special needs to encourage school participation.
However, the research highlights the importance of addressing barriers that extend beyond school infrastructure and financial assistance. Teacher preparedness, social stigma, gender discrimination and inadequate access to specialised support can influence educational participation and attainment.
The researchers emphasise the need for gender-sensitive and income-sensitive interventions, including school-based mental-health support, community awareness programmes and stronger access to healthcare services.
The study also acknowledges limitations arising from its reliance on cross-sectional and self-reported data. Its findings establish associations rather than proving that disability alone causes educational exclusion. Moreover, because the analysis covers adults, it cannot directly measure the present-day enrolment or dropout rates of children with disabilities.
Nevertheless, the findings offer an important indication of how educational inequalities can persist into adulthood. They underline the need to strengthen inclusive education systems so that children with disabilities are not merely enrolled in schools but are also supported in completing their education and accessing further opportunities.

The Science of Selling: How Sudheer Babu Decodes Buyer Psychology in ‘The Revenue Multiplier’

What Declining Freshwater Storage Means For India?

Pune to Host India International Science Festival 2026, With Focus on Students, Startups and Public Engagement

What Can Himalayan Marmot Droppings Tell Us About Climate Change?

$71 Billion Carbon Market, but Only $1.6 Billion in Government Deals: COP31 Exposes Gap Between Carbon Credit Supply and Demand

Indian universities lead Asia in research output per faculty, but the country’s top six all slip in QS ranking

Why Delhi’s Geography Makes It Vulnerable to Severe Air Pollution

India’s Richest Agree on One Cause Above All Others: Education

Europe Braces for Extremes as Commission Unveils Climate Resilience Framework

NASA recruits new astronauts for future Moon Base and Mars missions
-

 Math4 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
EP Deep Dive: Data & Solutions4 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
EP Deep Dive: Data & Solutions5 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics6 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews2 months ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate & Environment6 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society4 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society5 months ago
From Bell Labs to the Classroom: A Second Career in Teaching