Society
How China Is Redrawing the Global Map of Critical Minerals
China’s $120bn critical minerals investment is reshaping global supply chains and strengthening its dominance in the clean energy economy.







Society
Who Cares for India’s Older People?
On International Day of Older Persons, a HelpAge India study highlights gaps in healthcare, income, family care and social support facing older people in India, including added risks from climate-related hazards.

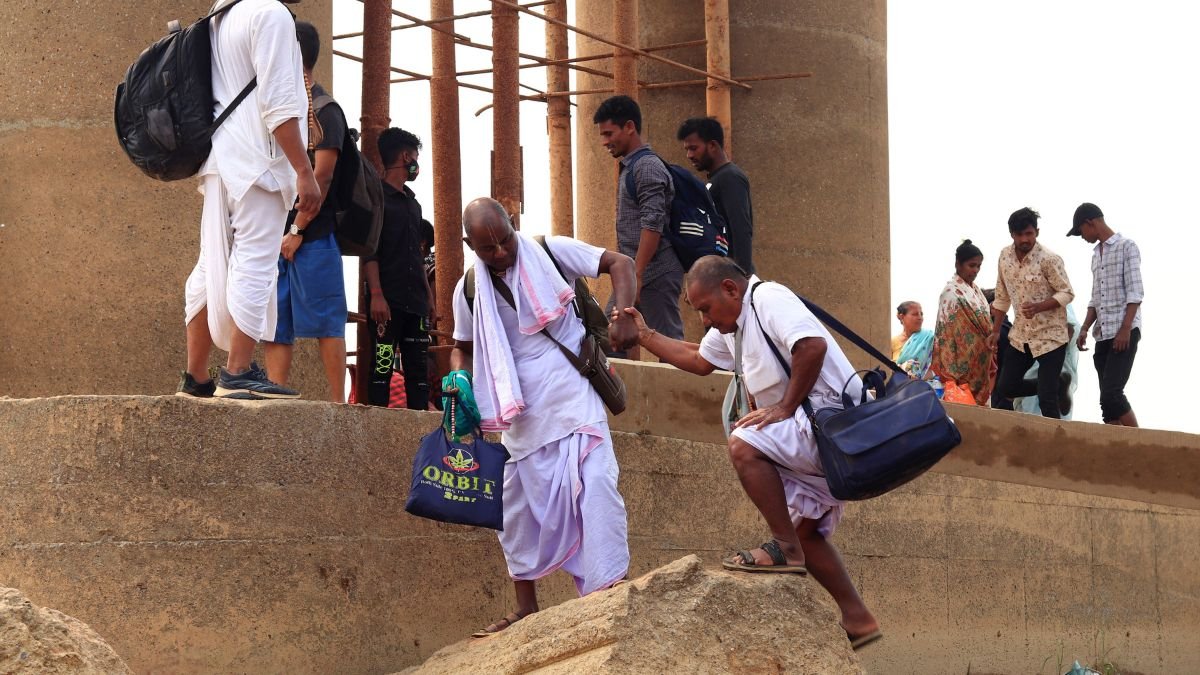
Growing older can change something as ordinary as getting medicines, visiting a doctor or managing a difficult day alone. For many older people, the question is not simply whether help exists, but whether someone is close enough and able to provide it when it is needed.
A recent HelpAge India study of 2,224 older people across 20 districts in 10 states offers a picture of the support systems on which they depend. It found that 94% of older people who needed care received it from family members. But that support is not equally available to everyone.
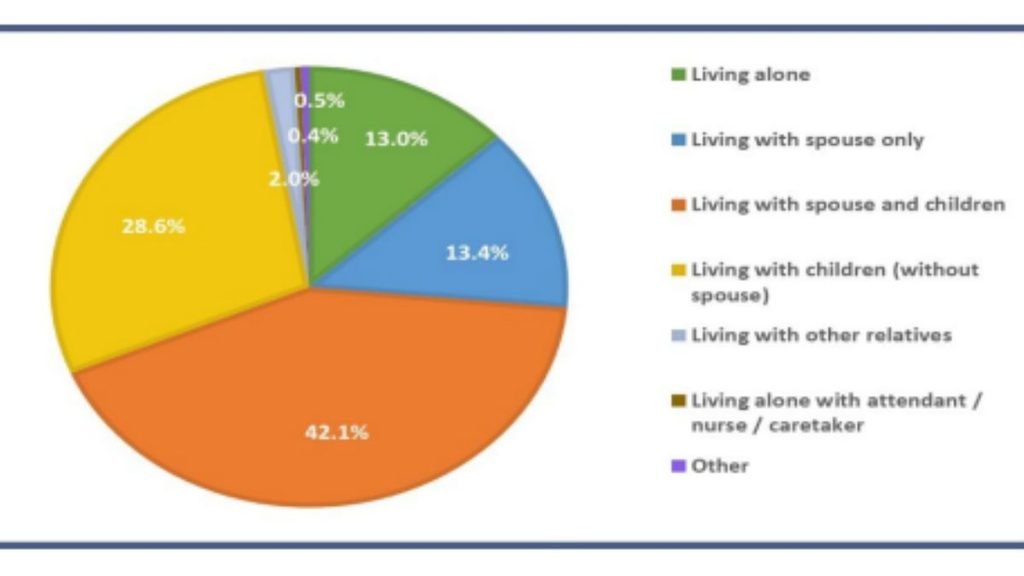
Thirteen percent of those surveyed lived alone, 33% were widows and 28% were aged 80 or above. Nearly half reported a long-term impairment, including mobility and vision difficulties. These circumstances matter because everyday care often depends on another person being physically present.
When Family is not Nearby
India’s older population continues to rely heavily on family for care. But migration for work is changing household arrangements. In the HelpAge study, 18% of households reported that a family member had migrated for work. Sons accounted for 76% of those migrants.
For older people living alone, neighbours often fill part of the gap. Thirty-eight percent depended on neighbours for care, while 20% relied on family members living elsewhere. Sixteen percent said they received no care.
Distance does not necessarily mean that families stop supporting older relatives. Financial assistance and regular communication can continue. But some needs cannot be met remotely: taking someone to a hospital, collecting medicines, helping them move around the house or responding when they suddenly fall ill. This distinction becomes particularly important during emergencies.
Health Harder to Manage
The study found that 52% of respondents could not afford medicines. Public facilities were an important source of healthcare, with 51% using primary health centres and 49% government hospitals.
Climate-related events exposed some of these existing difficulties further. Seventy-eight percent of those surveyed had experienced at least one such hazard in the previous three years, with heatwaves the most common.
Among those who experienced heatwaves, 74% said illness increased and 44% said existing health conditions worsened. One-third reported difficulty accessing healthcare. These figures are less about the hazard itself than about what happens when an older person already managing health problems has fewer options for care.
“Older persons are among those most at risk from rising climate shocks, particularly those living alone or with impairments, yet they remain largely invisible in climate response efforts,” says Rohit Prasad, CEO, HelpAge India. “Climate impacts extend beyond physical hazards, affecting health, income, housing, care and social wellbeing.”
Prasad says age-related physical, financial and social challenges can limit older people’s ability to prepare for, withstand and recover from climate events. He calls for ageing to be integrated into climate adaptation, climate financing, elder-centric disaster risk reduction and social protection policies.
Income Constraint
Healthcare is only one part of financial insecurity in later life. Pensions were the main source of income for 49% of respondents. Sixteen percent had neither work nor income, while others continued to work in agriculture, agricultural labour or other forms of employment.
The ability to pay for medicines, travel to healthcare facilities, household repairs or basic necessities depends heavily on this income. Work also changes with age. The HelpAge study found that the proportion reporting no work or income rose from 11% among those aged 60–69 to 21% among those aged 80 and above.
For people who have spent much of their lives in informal employment, growing older can therefore mean entering a period with limited savings, little employment protection and greater healthcare needs.
The Problem of Access
Government schemes can provide important support, but knowing about a benefit does not always mean being able to obtain it. The study found relatively high awareness of the Public Distribution System, pensions, subsidised healthcare and housing schemes. Yet access was more difficult for people with poor health, those severely affected by climate hazards, people without formal education and those from lower socioeconomic groups.
Respondents also reported delays, difficulties with digital access and a lack of assistance with applications. For an older person with limited mobility, poor eyesight or little experience with digital services, even a relatively straightforward application can become difficult without help.
Ageing Needs More Than Family Care
India’s ageing population is growing, while the family structures that have traditionally provided care are changing.
UNFPA estimates that the number of Indians aged 60 and above could approach 193 million by 2030. That growth will increase the need for healthcare, financial support and forms of care that do not depend entirely on whether an older person’s children live nearby.
The answer is not to replace family care, which remains central to the lives of many older people. It is to ensure that those who do not have family nearby, cannot afford private care or need support beyond what relatives can provide are not left without alternatives.
Ageing policy therefore needs to look beyond longevity. It has to account for who provides care, who pays for healthcare, how older people access public services and what happens when the person they depend on is no longer close by. For many older Indians, these are not future questions. They are questions of everyday life.
Health
Not Broken but Unheld: A New UN Report Asks Us to Tend the Forest, Not Only the Tree
A new UN report on youth mental health calls for an ecosystem approach linking well-being with education, work, housing, climate, technology and community.

Society
Digital Detox: Why Taking a Break From Screens Matters
A digital detox can help children and adults reduce screen dependence, reconnect with nature and relationships, and create space for reflection and creativity.



Icnoic Matterhorn Almost Snow-Free as Record Heat Accelerates Swiss Glacier Loss

Who Cares for India’s Older People?

Climate Change Is Already on Your Dinner Table. Here Is How It Got There

India Records Driest Monsoon in 11 Years as Rainfall Deficit Hits 12.6%

Not Broken but Unheld: A New UN Report Asks Us to Tend the Forest, Not Only the Tree

From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story

Farmers Borrowed to Build ‘Diggis’. Two Years Later, They Are Still Waiting for the Subsidy

Aim for the Stars: Anjali Thomas’s Journey from a Small College in Kerala to the Frontiers of Medical Imaging

Anxiety Freezes Career Decisions. Curiosity Unfreezes Them

The Engineer of Tomorrow Is Already Here
-

 Math2 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
Climate2 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
Society3 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics4 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews1 week ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate4 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society3 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society4 months ago
From Bell Labs to the Classroom: A Second Career in Teaching