Climate & Environment
Western Himalaya Heating Faster Than East, Study Finds; Snow Loss Could Surge
A new study finds the western Himalaya is warming faster than the central and eastern regions, with major losses in spring snow projected by 2100.

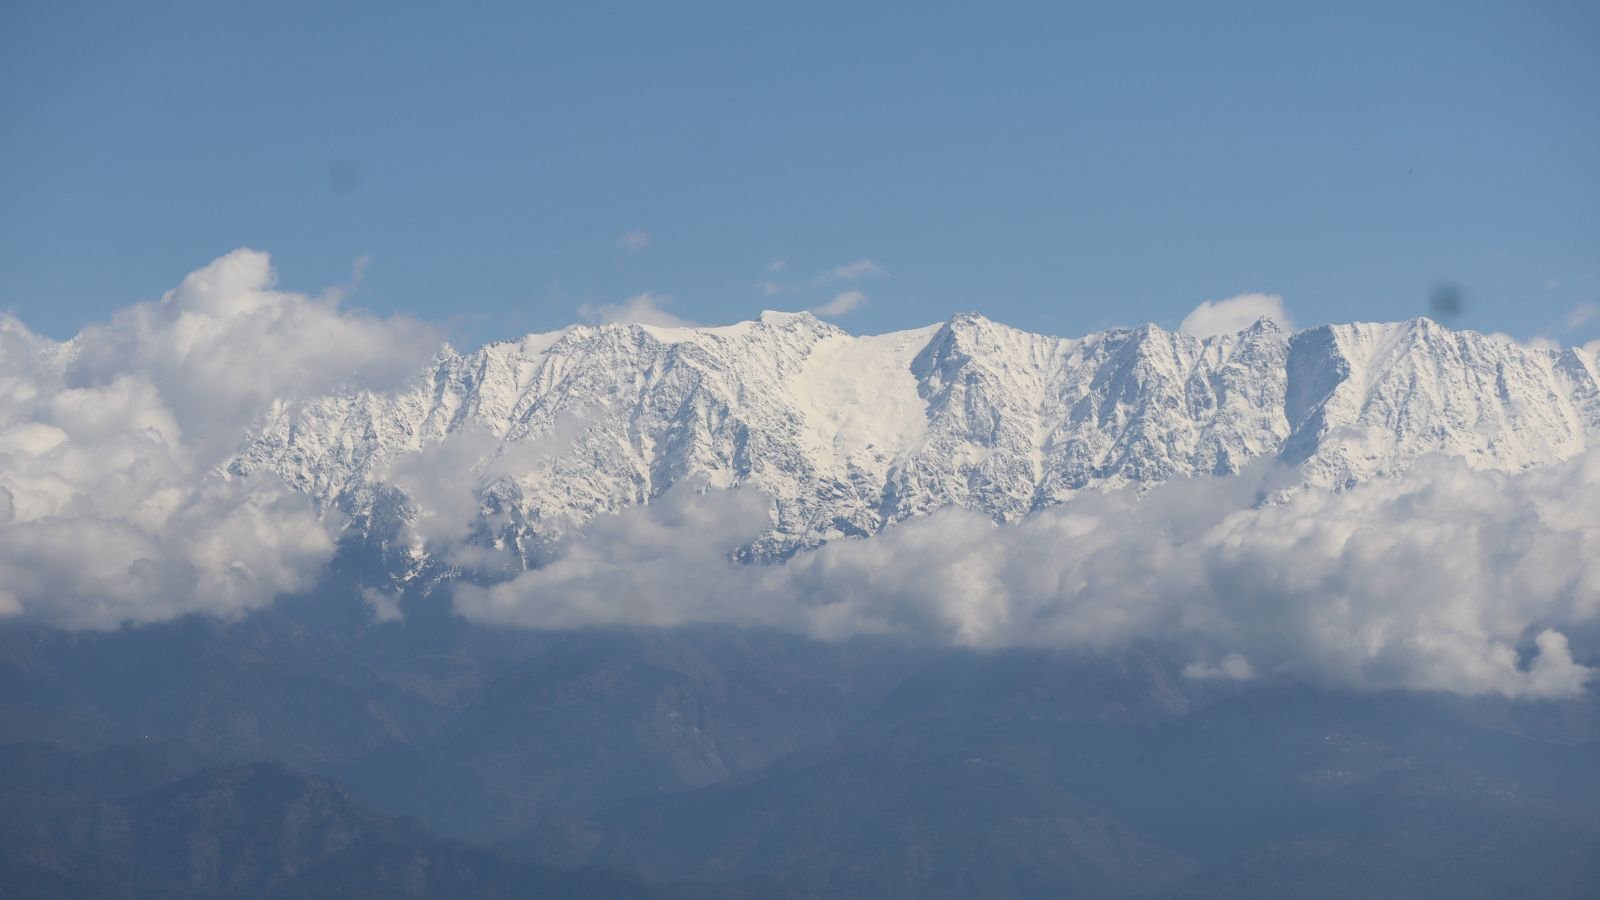
Western Himalaya warming is accelerating faster than in the central and eastern Himalayas, with the region projected to face the greatest snow loss by 2100, a new climate study finds.
A new study combining 120 years of observed temperature records (1901–2020) with eight global climate models finds that the western Himalaya (Ladakh, Jammu & Kashmir and Himachal Pradesh) is heating up more quickly than the central and eastern stretches of the range — a pattern that holds across every season and every emission scenario the researchers tested.
The imbalance shows up in multiple ways: winters are warming faster than springs, nights are warming faster than days, and by the end of the century, the western Himalaya stands to lose far more of its spring snow cover than the rest of the range, with the gap between low- and high-emission futures widening sharply the longer emissions stay high.
Western Himalaya warming is accelerating across seasons
A research study, Vulnerability of the Himalayan region under the climate change, published in the Journal of Earth System Science, led by the Department of Remote Sensing and Geoinformatics, Birla Institute of Technology (BIT), Mesra, Ranchi, with the Indian Institute of Tropical Meteorology (IITM), Pune, and Ashoka University, assessed how temperature and snow are changing across three sectors of the Indian Himalayan range, and how far that change could go by 2100.
The researchers drew on two sources of evidence: 120 years of recorded ground-station temperatures across the region, from 1901 to 2020, and eight global climate models that were first validated against that historical record and then projected forward to the year 2100 under five emissions scenarios, ranging from steep near-term cuts to continued high fossil-fuel use. Two seasons were examined: winter, when snow accumulates, and the pre-monsoon spring months, when it melts.
The range is split into three stretches, studied separately: the western Himalaya (Ladakh, Jammu & Kashmir, and Himachal Pradesh), the central Himalaya (largely Uttarakhand), and the eastern Himalaya (Sikkim, Arunachal Pradesh, and the wider North-East). Between them, they hold more than 15,000 glaciers and feed the Indus, Ganges and Brahmaputra, the rivers that roughly 1.5 billion people depend on.
The warming has already reached about 1°C, and it is not evenly spread
Compared with the first three decades of the 1900s, all three stretches of the range had already warmed by close to 1°C in winter by the two decades to 2014: 1.06°C in the western Himalaya, 0.96°C in the central Himalaya and 1.09°C in the east. Springs had warmed by 1.08°C in the west, and 0.83°C in the centre and east. The warming has not arrived at a steady pace. Warmer-than-normal years have become the rule rather than the exception across all three stretches over the past 20–30 years, most of the change has come recently, the study said.
“The Himalaya is often discussed as a single system, but our observations and models both say otherwise. The western Himalaya consistently emerges as the most sensitive stretch — it warms the most and loses the most snow under every pathway we tested. That has direct consequences for the states that sit in it,” said Protyusha Mukhopadhyay, lead author, Birla Institute of Technology (BIT), Mesra.
Under high emissions, western Himalayan winters may warm by more than 7°C
The models show the same west-to-east pattern throughout the century. If emissions stay high, winters by 2081–2100 would be 7.18°C warmer in the western Himalaya, 6.71°C warmer in the central Himalaya and 5.82°C warmer in the east, compared with the early 1900s. Springs warm in the same order: 6.91°C, 6.41°C and 5.16°C.
Himalayan Warming: Key Findings
- 1.06°C — winter warming in the western Himalaya already observed
- 7.18°C — projected winter warming in the western Himalaya by 2081–2100 under high emissions
- 95.9 kg/m² — projected western Himalayan spring snow loss under the highest-emission pathway
- 32 kg/m² — projected spring snow loss even under the lowest-emission pathway by the end of the century
- 1.23°C — rise in western Himalayan winter night-time temperatures
- 1.5 billion — approximate number of people dependent on rivers fed by the Himalayan region
“In the west and centre, winters are warming faster than springs. Less snow on the ground would mean a darker surface, which absorbs more heat, which melts more snow. It matters because winter is the season in which snow is supposed to build up; warmer winters mean less snow banked for the melt months that follow,” said Parthasarathi Mukhopadhyay, corresponding author, Ashoka University.
Nights are warming faster than days
One of the clearest signals in the observational record is that minimum (night-time) temperatures are rising faster than maximum (daytime) temperatures across the western and central Himalaya. In the western Himalaya, winter minimum temperatures rose 1.23°C against 0.87°C for day temperatures; in spring, 1.25°C against 0.91°C. In the central Himalaya the gap is wider still in winter (1.20°C against 0.72°C).
The eastern Himalaya is the exception, where winter maximum temperatures rose more (1.19°C) than minimum (0.99°C). Warmer nights matter because they shorten the hours in which snow and ice can refreeze. That speeds up melting, and changes when the meltwater reaches the rivers below.
“Rising night-time temperatures are the quieter half of this story, and arguably the more consequential one. When the cold nights that let snowpack recover start disappearing, you change the melt cycle itself rather than how much snow falls, but when the water arrives downstream,” said Dr Swagata Payra, co-author, BIT Mesra.
Spring is where the snow is being lost
Across all three stretches of the range, spring sees greater snow loss than winter, and the western Himalaya loses by far the most. The study measures this as the weight of snow sitting on each square metre of ground. Over the western Himalaya, spring snow falls away steadily even on the lowest-emission path: by 24.2 kg per square metre by 2040, 27.4 kg by 2060 and 32 kg by the end of the century. On the highest-emission path, that end-of-century loss reaches 95.9 kg per square metre, enough to point towards an almost complete loss of seasonal snow in some pockets of the region, the authors said.
The central Himalaya loses less, though still a substantial amount: between 17.0 and 34.9 kg per square metre by the end of the century, depending on the emissions path. The eastern Himalaya loses the least, between 5.5 and 11.1 kg. Winter follows the same pattern. Western Himalayan snow loss by the end of the century ranges from 9.5 kg per square metre on the lowest-emission path to 53.2 kg on the highest.
The gap between emission pathways
Western Himalayan winters end the century 2.55°C warmer if emissions fall sharply, or 7.18°C warmer if they do not (a gap of 4.6°C). By 2100, a high-emission trajectory would strip roughly three times more spring snow from the region than a low-emission one, and more than five times more winter snow. The eight models largely agree on the next two to three decades. They diverge much more towards 2100 because how much the region warms by then depends on choices that have not yet been made.
“The models agree on where we are headed over the next two to three decades. What remains open is the second half of the century, and that is determined by emissions rather than by anything intrinsic to the mountains. A low-emission pathway does not stop the warming, but it changes its magnitude by several degrees,” said Mukhopadhyay
The eastern Himalaya warms the least of the three and loses the least snow, and its outlook varies the least across the emission paths. However, the study notes that the east has become a hotspot for glacial lake outburst floods that are sudden, destructive floods released when a lake dammed by glacial debris gives way. “That risk is expected to spread westward in the future, driven by retreating glaciers and the new lakes they leave behind, not by temperature alone,” said Protyusha.
The authors call for region-specific climate services and adaptation policy; enhanced monitoring that combines in-situ networks, satellite products and sustained high-resolution modelling to track glacier and snow dynamics in near real time; strengthened early-warning systems; sustainable water management; community-level resilience programmes; and transboundary cooperation. How water actually moves through these high mountains is still poorly captured by models, and more measurement on the ground is needed before it can be said with confidence how much ice and snow melts each year, and how much of that reaches the rivers below, the authors said.






Climate & Environment
Global Climate Finance Hits Record $1.9 Trillion, but Vulnerable Nations Continue to Face Adaptation Funding Gap
Global climate finance reached a record $1.9 trillion in 2023–2024, but vulnerable developing countries continue to face an adaptation funding gap. As COP31 begins, questions remain over the delivery of the new $300 billion annual climate-finance target and equitable access to funding.

Global climate finance reached an unprecedented annual average of $1.9 trillion in 2023–2024, increasing by 32 per cent compared with the previous two-year period. However, despite the growth in investment, developing countries continue to face significant barriers in accessing the resources needed to adapt to climate change, according to assessments by the United Nations Framework Convention on Climate Change (UNFCCC) and the Organisation for Economic Co-operation and Development (OECD).
The findings come as countries meet for the 31st United Nations Climate Change Conference (COP31) in Antalya, Türkiye, from November 9 to 20. The conference takes place during the transition from the previous $100 billion annual climate-finance commitment to a new target of $300 billion by 2035.
Developed countries exceed $100 billion target, but questions remain
Developed countries had pledged to mobilise $100 billion annually by 2020 to support climate action in developing countries. The commitment was subsequently extended through 2025. According to the OECD’s 2026 assessment, developed countries provided and mobilised $132.8 billion in 2023 and $136.7 billion in 2024, exceeding the target for the third consecutive year.
However, the reported totals do not necessarily represent grants or money directly disbursed to developing countries. They include different forms of public finance, multilateral development bank contributions and private finance mobilised through public interventions.
Differences in accounting methods have also complicated assessments of whether countries are meeting their commitments. The UNFCCC’s 2026 assessment highlights variations in how countries report loans, grants, commitments and disbursements, making comparisons between datasets difficult.
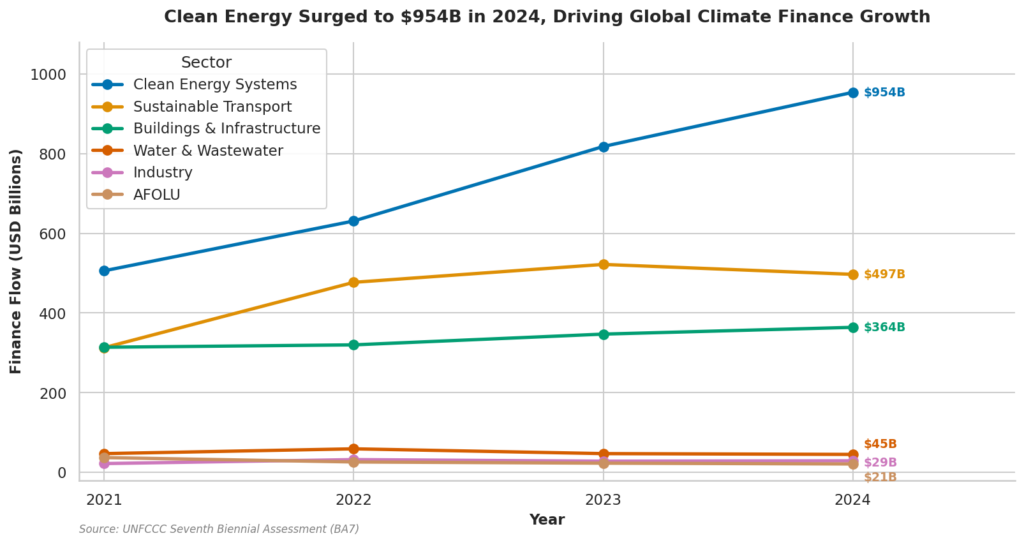
Total global climate finance reached an annual average of USD 1.9 trillion in 2023–2024.
The earlier target is now being replaced by the New Collective Quantified Goal (NCQG), adopted at COP29 in 2024. It calls for developed countries to take the lead in mobilising at least $300 billion annually for developing countries by 2035. The wider ambition is to scale up climate finance from all sources to at least $1.3 trillion annually by the same year.
Adaptation remains dependent on public finance
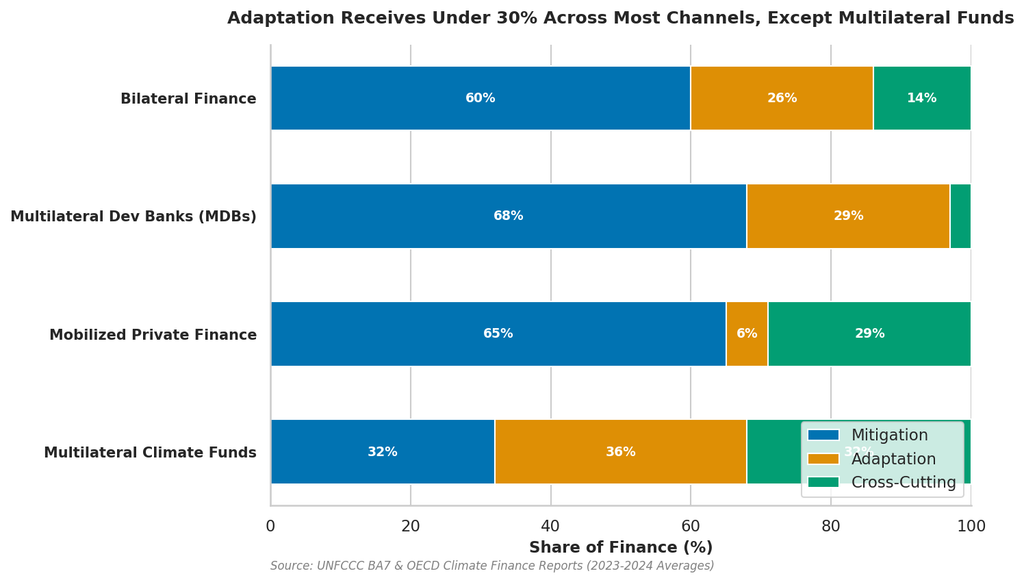
The expansion of climate finance has not translated into comparable support for adaptation. Investments in mitigation, including renewable energy and low-emission transport, have attracted substantial private capital. Adaptation projects such as flood protection, resilient agriculture, water management and coastal infrastructure, however, often generate fewer direct commercial returns.
The OECD reported that developed countries’ adaptation finance reached $33.6 billion in 2023 and $34.7 billion in 2024. Public finance accounted for more than 90 per cent of the tracked adaptation finance in both years, highlighting the continued dependence of adaptation initiatives on government and multilateral funding.
The broader financing gap is considerably larger. The United Nations Environment Programme’s Adaptation Gap Report 2026 estimates that developing countries will require approximately $305 billion annually by 2035 to meet their adaptation needs. This is substantially higher than the current international public adaptation finance flows.
LDCs and island nations receive a limited share
The financing imbalance is particularly significant for Least Developed Countries (LDCs) and Small Island Developing States (SIDS), which face high exposure to extreme weather, rising sea levels and other climate-related risks.
According to the OECD, LDCs received an annual average of $24.5 billion in climate finance in 2023–2024. SIDS received $3.8 billion in each of those years. The figures underline the limited scale of financial support reaching countries with substantial adaptation requirements.
A report published by the United Nations Capital Development Fund ahead of COP31 found that LDCs, which are home to almost 20 per cent of the global population, received only 1.9 per cent of global climate finance in 2024.
The terms on which finance is provided are also important. The UNFCCC’s assessment found that loans accounted for 91 per cent of multilateral development bank climate finance in its 2023–2024 channel-level breakdown. While loans can support large infrastructure projects, debt-based finance may place additional pressure on countries already facing economic constraints.
COP31 must move from targets to delivery
The latest figures reveal a gap between the scale of global climate investment and the resources reaching countries most vulnerable to climate impacts. Although the new $300 billion target represents an increase in the international climate-finance commitment, its effectiveness will depend on how much funding is accessible, predictable and directed towards adaptation.
For developing countries, particularly LDCs and SIDS, increasing the grant component, improving transparency in financial reporting and expanding concessional funding will be essential.
COP31 offers an opportunity to address these concerns as countries begin implementing the new climate-finance framework. The challenge is no longer only to mobilise larger sums, but to ensure that finance reaches communities facing the greatest climate risks.
Climate & Environment
India Ranks 28th in Global Climate Ranking, Down Five Places
ndia has dropped five places to 28th in the Climate Change Performance Index 2027. Despite reaching 50% non-fossil installed power capacity, coal supplied 71% of its electricity in 2025.

India has reached a major milestone in renewable energy capacity, with non-fossil fuel sources accounting for half of its installed electricity capacity in June 2025. Yet coal continued to generate 71% of the country’s electricity that year. This gap between capacity additions and the actual electricity mix is central to India’s performance in the Climate Change Performance Index (CCPI) 2027, where the country has slipped five places to 28th.
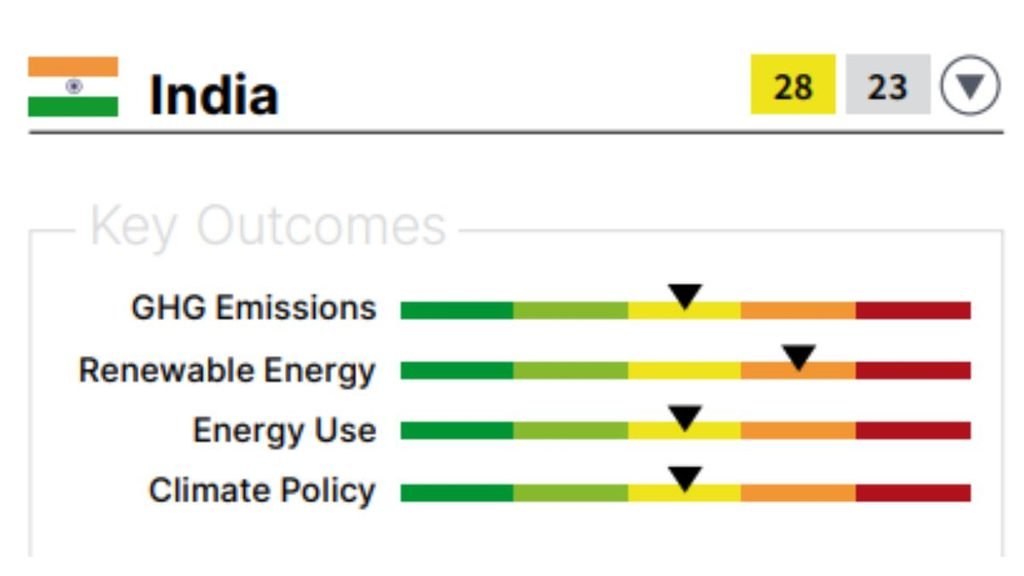
The index, published by Germanwatch and the NewClimate Institute, gives India an overall medium rating. Its assessment points to a mixed record: India has made substantial progress in expanding renewable energy and has performed relatively well on climate policy, but its energy use, emissions and renewable energy performance remain areas of concern.
India’s fall in the rankings should not be read as evidence that its renewable energy expansion has stalled. The country reached the 50% non-fossil capacity milestone five years ahead of its earlier 2030 target. However, installed capacity measures the potential to generate electricity, not how much power sources actually supply. The milestone also includes nuclear energy.
Data from Ember’s Global Electricity Review 2026 show that coal accounted for 71% of India’s electricity generation in 2025, against a global average of 33%. India’s coal generation did fall by 2.9% that year, while renewable generation rose sharply. But the continued dominance of coal in the electricity mix shows how much of the country’s power demand remains tied to fossil fuels.
Grid Constraints Slow the Transition
The challenge is becoming visible in the way India’s electricity grid handles solar power. An Ember analysis published in January 2026 estimated that the country curtailed 2.3 terawatt hours (TWh) of solar generation between late May and December 2025. Grid operators had to reduce solar output as an emergency measure to maintain grid security.
The problem is linked partly to the limited flexibility of conventional power plants. Solar generation rises during daylight hours, while electricity demand continues into the evening, when solar output falls. Coal-fired plants that remain online to meet demand can have limited room to reduce their output further. Without sufficient storage and other flexible sources of electricity, the grid cannot always accommodate the full amount of renewable power available.
This creates a practical constraint for India’s energy transition. Adding solar and wind capacity is essential, but the electricity system also needs stronger transmission networks, battery storage and power plants capable of adjusting output to changes in demand and renewable generation. Otherwise, more installed capacity will not translate into an equivalent reduction in coal-fired electricity.
The CCPI’s category rankings reflect the uneven progress. India ranks 13th in climate policy, but 31st in greenhouse gas emissions, 33rd in energy use and 40th in renewable energy. Its renewable energy category receives a low overall rating, despite a high trend indicator. This suggests that recent progress is significant, while the overall level of renewable energy deployment and its contribution to the energy system still have considerable room to improve.
India’s targets: Stronger Implementation
India’s updated climate commitments set out targets for 2035. These include reducing the emissions intensity of its gross domestic product by 47% from 2005 levels, raising the share of non-fossil sources to around 60% of cumulative installed electricity capacity, and creating a carbon sink of 3.5–4 billion tonnes of carbon dioxide equivalent through forest and tree cover.
The country has also begun implementing its Carbon Credit Trading Scheme, with emissions-intensity targets assigned to 490 industrial entities from January 2026. The effectiveness of the scheme will depend on the ambition of those targets, reliable monitoring and verification, and evidence that participating industries are actually reducing emissions.
The index also draws attention to gaps in energy efficiency. Building energy codes and appliance standards exist, but compliance remains uneven, particularly in informal markets. In transport, urban rail connectivity had expanded to 26 cities by August 2026. However, public transport improvements will also require affordable and reliable bus services, along with safer infrastructure for walking and cycling.
India’s dependence on imported fossil fuels adds an economic and energy-security dimension to the transition. Disruptions to shipping through the Strait of Hormuz have highlighted the risks faced by countries that rely on international supplies of oil and gas. Reducing fossil fuel consumption would help limit exposure to such external shocks, alongside its climate benefits.
Climate Change Performance Index: How India Compares With Other Major Economies
The CCPI leaves its first three positions vacant because no country meets the highest performance standards across all assessed categories. Denmark ranks highest at fourth place, followed by Lithuania and Luxembourg. Denmark has remained the best-performing country in the index for six consecutive years.
The contrast with the United Kingdom is also instructive. The UK, ranked seventh, is the only G20 economy to receive a high overall rating. Its electricity system became coal-free in 2025, according to Ember. Ten G20 members, meanwhile, received very low ratings in the CCPI, underscoring the difficulty major economies face in aligning their energy systems and climate commitments. India’s 28th position places it ahead of several developing economies, including Brazil at 21st, the Philippines at 16th and Nigeria at 17th. But its ranking also shows that early gains in clean-energy capacity do not, on their own, secure a stronger overall climate performance.
India has set a net-zero emissions target for 2070. The CCPI assessment points to the need for clearer, time-bound pathways for reducing the use of coal, oil and gas, with sector-specific milestones and plans to support workers and regions dependent on fossil fuel industries. The immediate test is visible in the electricity system: India must make its growing renewable capacity more usable, while reducing the share of power generated from coal. Until that happens, the country’s clean-energy expansion will continue to coexist with a power mix heavily dependent on fossil fuels.
Climate & Environment
Global fossil fuel emissions projected to fall in 2026, but India’s emissions to rise 4.4%
Global climate finance reached a record annual average of $1.9 trillion in 2023–2024, but developing countries continue to face significant barriers to accessing adaptation funding. As COP31 begins in Antalya, questions remain over the delivery of the new $300 billion annual climate-finance target and the support available to climate-vulnerable nations.
Global carbon dioxide emissions from fossil fuels are projected to decline marginally in 2026, even as India’s emissions are expected to increase by 4.4%, according to the latest Global Carbon Budget released by the Global Carbon Project on November 10. The findings highlight the uneven pace of the global energy transition, with expanding renewable energy capacity yet to deliver a sustained reduction in fossil fuel emissions.
The 2026 assessment estimates that global fossil fuel CO₂ emissions will reach 38.2 billion tonnes, representing a 0.4% decline compared with 2025. However, the projected reduction is partly attributed to lower oil consumption following the energy shock associated with the Iran conflict, rather than solely to structural changes in energy systems.
India’s fossil fuel emissions are projected to grow by 4.4% in 2026, exceeding the country’s average annual growth rate of 3.5% over the previous decade. India accounts for approximately 8% of global fossil fuel CO₂ emissions. The report notes that the projected increase partly reflects a rebound from relatively low emissions growth in 2025.
The contrasting trends in major economies underline the challenges of reducing emissions while meeting growing energy demand. China’s fossil fuel emissions are projected to decline by 0.9%, while those of the United States and the European Union are expected to fall by 1.3% and 1.5%, respectively.
Renewable energy offsets growing demand
The expansion of renewable energy and electric vehicles is increasingly limiting the growth of global emissions. According to the assessment, solar and wind power, alongside electric vehicles, are now offsetting approximately two-thirds of the additional emissions that would otherwise arise from increasing energy demand.
Emissions avoided through solar and wind power have increased substantially, from 0.28 billion tonnes in 2010 to an estimated 4.6 billion tonnes in 2026. The findings indicate that clean technologies are becoming increasingly important in meeting rising energy requirements without a corresponding increase in fossil fuel consumption.
However, the transition remains insufficient to achieve a sustained decline in global emissions. A research paper published alongside the carbon budget in Nature Climate Change, titled ‘A further acceleration of clean energy is needed for global CO₂ emissions to peak and decline‘, estimates that economic growth and changing energy consumption could add 2.59 billion tonnes of emissions between 2025 and 2028.
Solar power, wind power and electric vehicles could offset approximately 1.64 billion tonnes of this increase under current deployment trends. An accelerated deployment scenario could raise the avoided emissions to around 2 billion tonnes.
The researchers argue that renewable energy expansion must accelerate further to ensure that the growth in clean energy outpaces increasing global energy demand.
Land-use emissions add to the challenge
The projected decline in fossil fuel emissions does not translate into an overall reduction in carbon dioxide emissions. When emissions from land-use changes, including deforestation and forest degradation, are included, global CO₂ emissions are expected to reach 43.3 billion tonnes in 2026, compared with 42.8 billion tonnes in 2025.
View of Taipei’s skyline shrouded in smog.Image credit:Pexels
Emissions from land-use changes are projected to rise to 5.1 billion tonnes this year. The increase is associated with peatland fires and forest degradation in Southeast Asia, amid drier conditions linked to the developing El Niño.
The assessment also highlights the importance of natural carbon sinks. Land and ocean ecosystems absorbed approximately 49% of human-caused carbon emissions over the past decade. However, climate change is increasingly affecting their ability to absorb and store carbon.
Atmospheric CO₂ concentrations are projected to reach 427.7 parts per million in 2026, approximately 54% above pre-industrial levels.
Less than four years of the 1.5°C carbon budget remain
The report estimates that the remaining global carbon budget for limiting warming to 1.5°C is approximately 150 billion tonnes of CO₂. At current emission levels, this amount could be exhausted in less than four years.
The findings reinforce the urgency of accelerating the transition away from fossil fuels while protecting forests and other natural carbon sinks. Although renewable energy and electric mobility are increasingly limiting emissions growth, the researchers caution that their expansion has not yet reached the scale required to reverse the global emissions trajectory.
For India, the projected 4.4% increase highlights the challenge of aligning expanding energy requirements with climate commitments. The findings point to the need for faster renewable energy deployment, improvements in energy efficiency and stronger protection of natural ecosystems.
The 2026 Global Carbon Budget is the 21st annual assessment produced by an international research collaboration involving more than 140 scientists. It provides updated estimates of global carbon emissions, natural carbon sinks and the implications for meeting the goals of the Paris Agreement.
-

 Math4 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
EP Deep Dive: Data & Solutions4 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
EP Deep Dive: Data & Solutions4 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics6 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews2 months ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate & Environment5 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society4 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society5 months ago
From Bell Labs to the Classroom: A Second Career in Teaching