Sustainability
Solar Power Is Bringing More Electricity to Indian Farms. But What About the Water Beneath Them?
India’s solarisation drive is giving farmers more reliable and affordable electricity for irrigation. But as solar pumps expand, a new concern is emerging: could easier access to power accelerate groundwater extraction in regions where aquifers are already under stress? Evidence from Rajasthan and Gujarat suggests the answer depends on how solar irrigation is designed and managed.

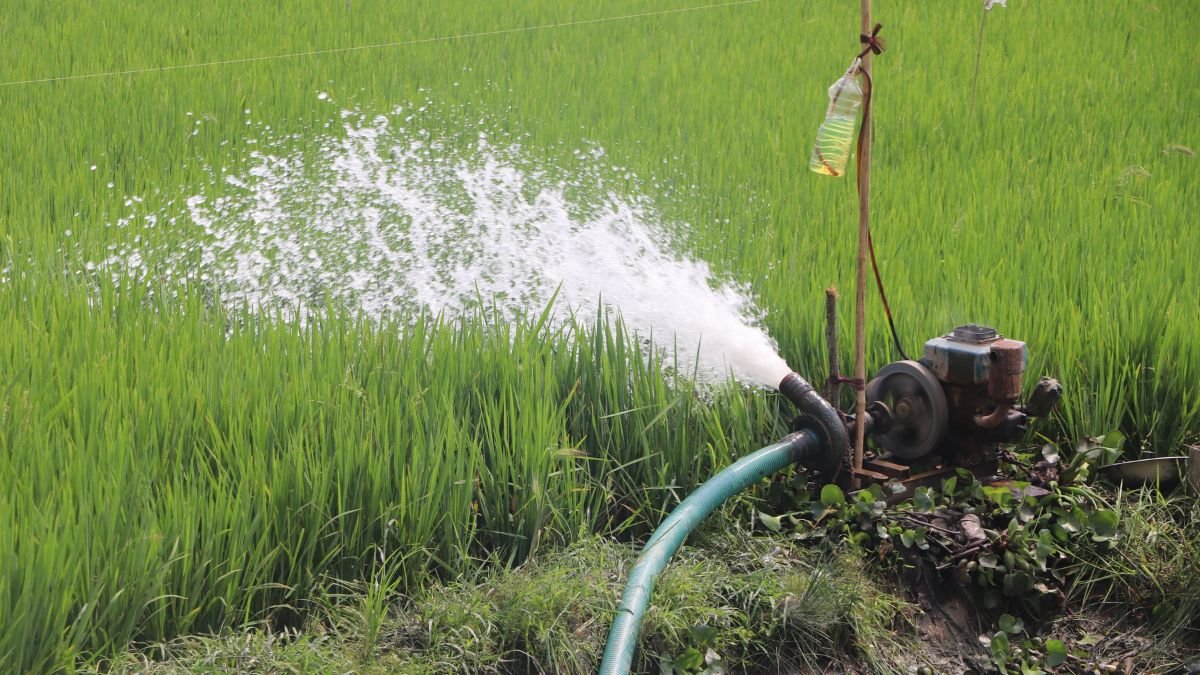
For years, electricity has been one of the biggest uncertainties in Indian farming. Farmers dependent on groundwater have often had to work around limited power supply, run diesel pumps or wait for electricity to arrive at odd hours. Solarisation is changing that equation. Through the Centre’s PM-KUSUM scheme, agricultural pumps are being converted to solar power and entire agricultural feeders are being solarised. The aim is to provide farmers with more reliable daytime electricity, reduce diesel use and lower the cost of agricultural power.
The change is significant. By 2025-26, around 25 lakh agricultural pumps had been installed or solarised under PM-KUSUM, while the programme had added 7.67 GW of solar capacity during the year. For a farmer, a solar pump can mean fewer hours spent waiting for electricity and greater control over irrigation. But there is a complication. Much of India’s irrigation already depends on groundwater. If solar power makes pumping cheaper and more reliable, farmers may have fewer reasons to stop pumping.
That creates a difficult question for India’s clean-energy transition: Can giving farmers more electricity to pump water also accelerate the depletion of the water they depend on? The answer is not a simple yes. Evidence from different parts of India shows that solarization can increase ground water extraction in some circumstances, while well-designed systems can also encourage farmers to use less water.
The difference lies in the incentives.
When the Energy Constraint Disappears
India has an enormous agricultural groundwater economy. About two-thirds of the country’s irrigation depends on groundwater, while India has an estimated 23 million agricultural pumps. Around three-quarters of these pumps are electric, according to recent research on solar irrigation.
For decades, electricity availability and the cost of pumping have acted as constraints on groundwater extraction. Solar pumps can weaken those constraints. Once the initial investment is made, the cost of running a solar pump is considerably lower than continuously buying diesel. In areas where electricity is subsidised, solarisation can similarly reduce the financial cost associated with irrigation.
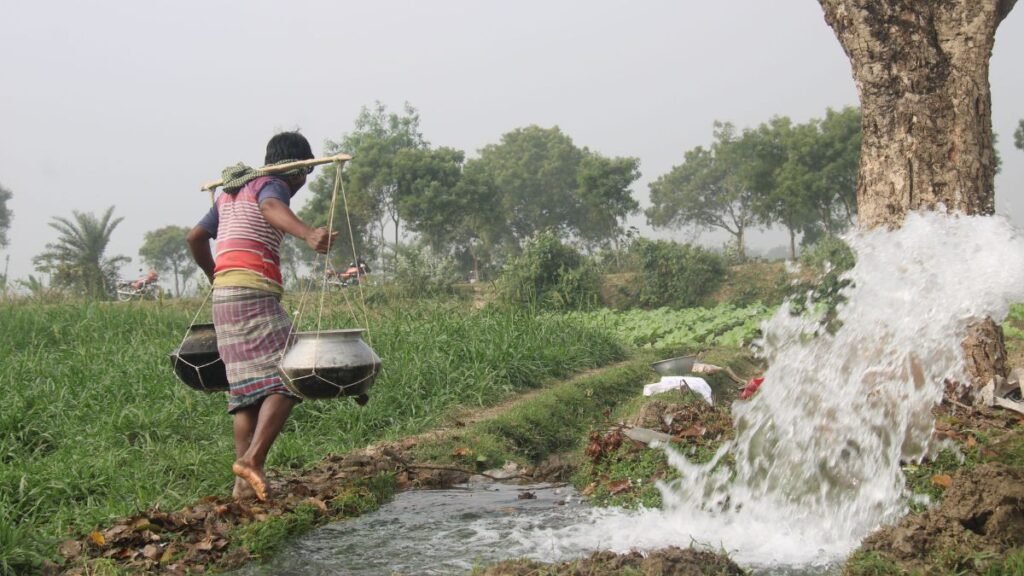
That can be good news for farmers. It can also encourage them to irrigate more land, grow additional crops or pump water for longer periods. Research from Rajasthan provides some evidence of this effect.
A study of 414 farmers across six districts found that solar-pump adoption increased groundwater consumption by 16–39% in Jaipur and Sikar. At the same time, farmers benefited from lower energy costs and higher farm incomes. The finding is important because it shows that groundwater depletion does not necessarily result from farmers making an environmentally harmful choice. They may simply be responding to a new economic reality. If irrigation becomes cheaper, using more water can make financial sense.
The Groundwater Problem is Already Severe
Solarisation is also arriving at a time when several parts of India are already extracting groundwater faster than their aquifers can sustainably provide it. The 2025 national groundwater assessment estimated India’s annual extractable groundwater resource at 407.75 billion cubic metres. Annual extraction stood at 247.22 billion cubic metres, putting the country’s overall stage of groundwater extraction at 60.63%.
But the national average hides the severity of the problem in several states. In 2025, the stage of groundwater extraction was estimated at: Punjab: (156%), Rajasthan: (147%), Haryana: (137%), Tamil Nadu: (74%), Uttar Pradesh: (70%), Karnataka: (66%) A figure above 100% indicates that annual groundwater extraction exceeds the state’s annual extractable groundwater resource.
At the national level, 730 of 6,762 groundwater assessment units were classified as over-exploited in 2025. This is why the location of a solar pump matters. A pump installed in an area with a healthy aquifer is not equivalent to one installed in a region where groundwater levels are already falling.
Rajasthan Offers a Warning
Rajasthan illustrates the tension particularly clearly. The state had a groundwater extraction stage of 147% in 2025. At the same time, it has become one of India’s major beneficiaries of solar irrigation programmes.
But it would be misleading to directly attribute Rajasthan’s groundwater crisis to solar pumps. Groundwater depletion in the state has deeper roots: intensive agriculture, rainfall variability, water-intensive cropping and decades of groundwater dependence all play a role. The significance of solarisation is different.
It can potentially remove one of the constraints on further extraction. The Rajasthan study found that solar-pump adopters increased groundwater consumption in some districts while also seeing substantial economic gains. In districts that had previously relied heavily on diesel, diesel consumption fell sharply after solar-pump adoption.
This is the paradox at the heart of the solar irrigation story. The technology can simultaneously make farming more sustainable in energy terms and less sustainable in water terms.
Gujarat Shows How Outcome can be Different
There is another side to the story. Research from Gujarat has found that solarisation does not necessarily lead to more groundwater extraction. A 2026 study examined grid-connected solar irrigation pumps in Anand and Botad, two areas with different aquifer conditions. In Anand, farmers using solar pumps actually used 556–608 mm less irrigation water than the comparison group across the two years studied. The reason is crucial. Farmers with grid-connected solar pumps could sell surplus electricity to the grid.
That creates a different economic calculation. Instead of using every available unit of electricity to pump water, a farmer has a financial incentive to conserve electricity—and therefore potentially water—and sell the surplus.
The same study found no significant difference in irrigation water use between solar and non-solar farmers in hard-rock Botad, where water availability itself was a stronger constraint. The lesson is not that solar pumps are either good or bad for groundwater. It is that the policy surrounding the pump determines much of the outcome.
The Missing Link: Energy Policy and Water Policy
India has already acknowledged the groundwater risks associated with solar irrigation. PM-KUSUM guidelines restrict the installation of new standalone solar pumps in groundwater-depleted areas identified as dark zones. In such areas, solarisation of existing electric pumps is subject to conditions including the adoption of micro-irrigation.
But the scale of India’s solarisation means that groundwater considerations cannot remain a safeguard attached to individual schemes. They need to become part of the planning process itself. That means asking three questions before expanding solar irrigation in a region:
How much solar capacity is being installed? How much groundwater is available? How much additional water could that energy make it possible to extract? Those questions are particularly important in states such as Punjab, Rajasthan and Haryana, where groundwater extraction is already above the annual extractable resource.
Solarisation could also be used to change farmers’ incentives rather than simply increase their pumping capacity. Electricity buyback, efficient irrigation, crop diversification and groundwater monitoring could make conserving water financially attractive.
The Transition Below the Ground
India needs more clean electricity in rural areas. Solar power can reduce diesel dependence, improve the reliability of agricultural power and give farmers greater control over irrigation. Those are real gains. But electricity and water are not separate systems on a farm.
The same solar panel that produces clean energy can power a pump drawing hundreds of litres of groundwater from an aquifer. Whether that becomes a problem depends on how much water is available, what crops are being grown, how efficiently water is used and what incentives farmers face.
The evidence from Rajasthan suggests that cheap solar pumping can increase groundwater use. The evidence from Gujarat suggests that a different policy design can encourage farmers to conserve water instead. So the question for India’s solarisation drive is no longer simply how many pumps can be solarised.
It is whether the country can make sure that the electricity transition above the ground does not quietly deepen the water crisis below it. India may have solved part of its rural power problem. The next challenge is making sure the solution does not come at the cost of its aquifers.






Sustainability
India Captures 5.7% of Global Greenfield Investment, Outpacing China
India accounted for 5.7% of global greenfield investment between 2020 and 2025, more than double China’s share. UNCTAD data highlight the concentration of investment in AI infrastructure, semiconductors and energy-transition technologies.
Sustainability
The Climate Problem Hiding in Your Kitchen Bin
Food waste sent to landfills can generate methane as it decomposes without oxygen, adding to greenhouse gas emissions and the climate crisis.
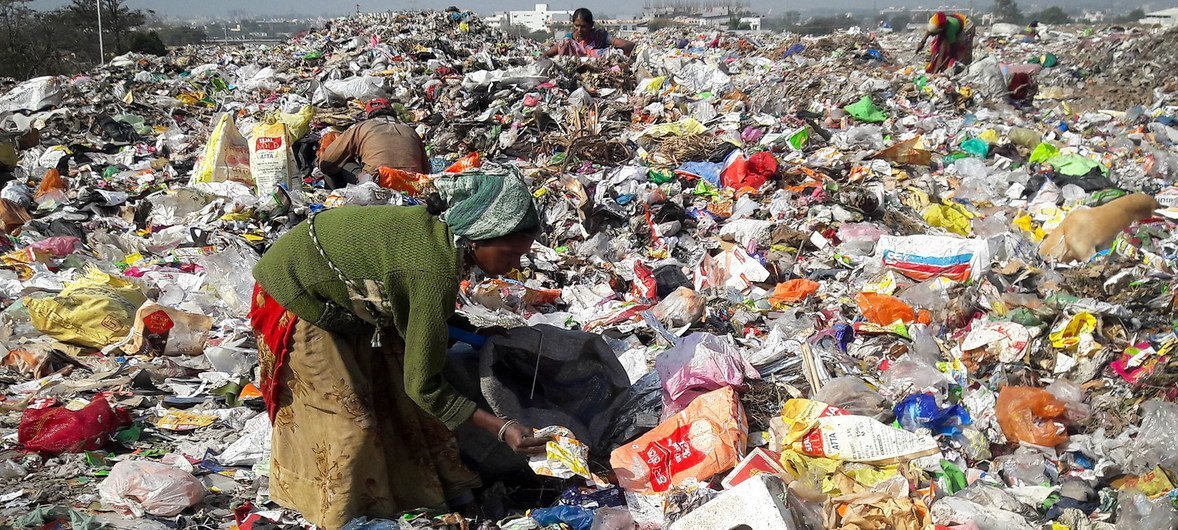
Every day, more than one billion meals go uneaten around the world. What appears to be a problem of excess food, poor planning or household waste is also becoming a climate problem, as discarded food can generate methane when it decomposes in landfills.
Global food waste reached an estimated 1.05 billion tonnes in 2022, accounting for nearly one-fifth of all food available to consumers at the retail, food service and household levels, according to the United Nations Environment Programme (UNEP) Food Waste Index Report 2024.
Households accounted for about 60 per cent of this waste, highlighting how everyday food consumption is closely connected to the global climate challenge.
How wasted food becomes a climate problem
Food waste becomes particularly problematic when it is sent to landfills. Buried beneath layers of other waste, organic matter decomposes in oxygen-poor conditions. Microorganisms then break it down and release methane.
Methane is a far more powerful heat-trapping gas than carbon dioxide over shorter periods. The UN estimates that methane traps about 86 times more heat than carbon dioxide over a 20-year period.
Landfills are therefore an important source of human-caused methane emissions. In the United States, municipal solid waste landfills are the third-largest source of human-related methane emissions.
The scale of food waste also means that the climate impact begins long before food reaches a landfill. Food that is never eaten still requires land, water, energy and other resources to produce, process, transport and store.
The Food and Agriculture Organization (FAO) estimates that around 1.4 billion hectares of agricultural land ,roughly 28 per cent of the world’s agricultural land is used to produce food that is ultimately lost or wasted.
Food waste can also contribute indirectly to deforestation because agricultural expansion remains a major driver of forest loss. Wasting food therefore means wasting the land and natural resources used to produce it.
Cutting waste could deliver faster climate benefits
The climate implications are significant, but methane’s relatively short atmospheric lifetime also presents an opportunity.
Unlike carbon dioxide, which can remain in the atmosphere for centuries, methane breaks down much faster. Cutting methane emissions can therefore produce climate benefits within decades.
“At a time when the world is searching for practical ways to slow warming quickly, tackling food waste may be one of the most immediate and cost-effective climate solutions available,” said Martin Krause, Director of the Climate Change Division at UNEP.
The Food Waste Breakthrough initiative aims to halve food waste by 2030 and could reduce methane emissions by up to 7 per cent.
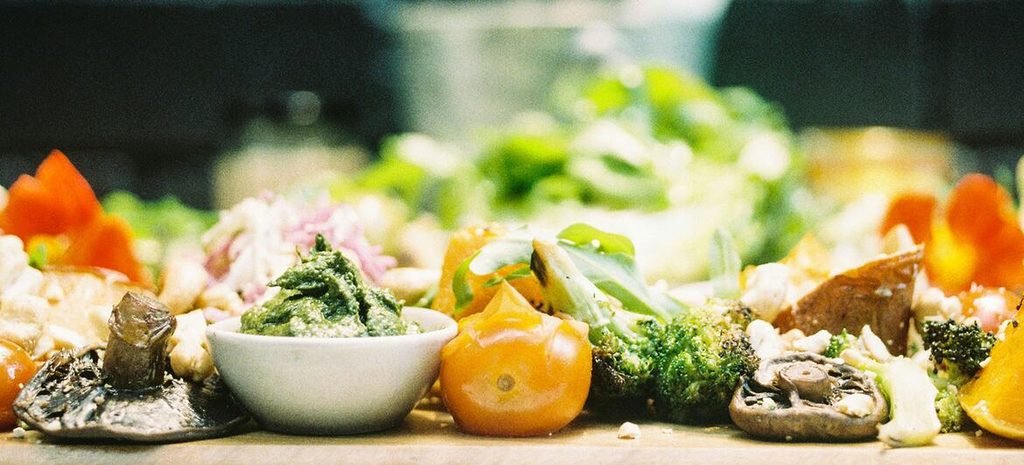
Food waste represents a major environmental threat .Image credit: Unsplash/Simon Peel
Several countries are already attempting to reduce waste before it reaches landfills. Brazil has introduced national plans focused on reducing food and organic waste, while UNEP is working with authorities, schools, communities and food businesses in Rio de Janeiro to reduce food waste.
In Kenya, a UNEP-supported initiative is recovering surplus food from across the agricultural value chain and redirecting it to early childhood education centres in underserved communities.
What happens to unavoidable food scraps?
Preventing food waste is the most effective way to avoid methane emissions. But food scraps that cannot be prevented can also be managed differently.
When organic waste is separated from other rubbish and composted in oxygen-rich conditions, it does not produce methane in the same way as food buried in an anaerobic landfill environment.
This approach is being promoted in several African countries, where organic material makes up more than half of municipal solid waste. Eleven governments, with support from the UNEP-convened Climate and Clean Air Coalition, have committed to incorporating waste pickers into formal waste-management systems and training them to sort and compost organic waste.
Another emerging approach uses black soldier flies. Their larvae consume organic waste, allowing food scraps to be converted into useful biomass. The approach is already being used in waste-management systems in countries including Uganda and Malawi.
A climate solution hiding in the bin
Global efforts to tackle food waste have gained momentum, but progress remains insufficient. The world is still far from meeting the Sustainable Development Goal of halving per-capita food waste by 2030.
More than 60 countries have also pledged, through the Declaration on Reducing Methane from Organic Waste, to cut waste-sector methane emissions by 30 to 35 per cent below 2020 levels by 2030.
For consumers, the climate connection can begin with something as simple as buying only what is needed, storing food properly and using leftovers.
“Every meal rescued, shared or never wasted is food put to better use. It is also methane avoided,” Krause said.
The message is straightforward: reducing food waste is not only about saving food. It is also about reducing the methane released when that food becomes rubbish and slowing warming in the process.
Earth
Hunter Valley Coal Mine Gets Approval to Run to 2045. What Does It Mean for Australia’s Climate Transition?
Australia’s Hunter Valley coal mine has been approved to operate until 2045, raising questions about how the extension fits into the country’s transition towards lower emissions and its net-zero target.
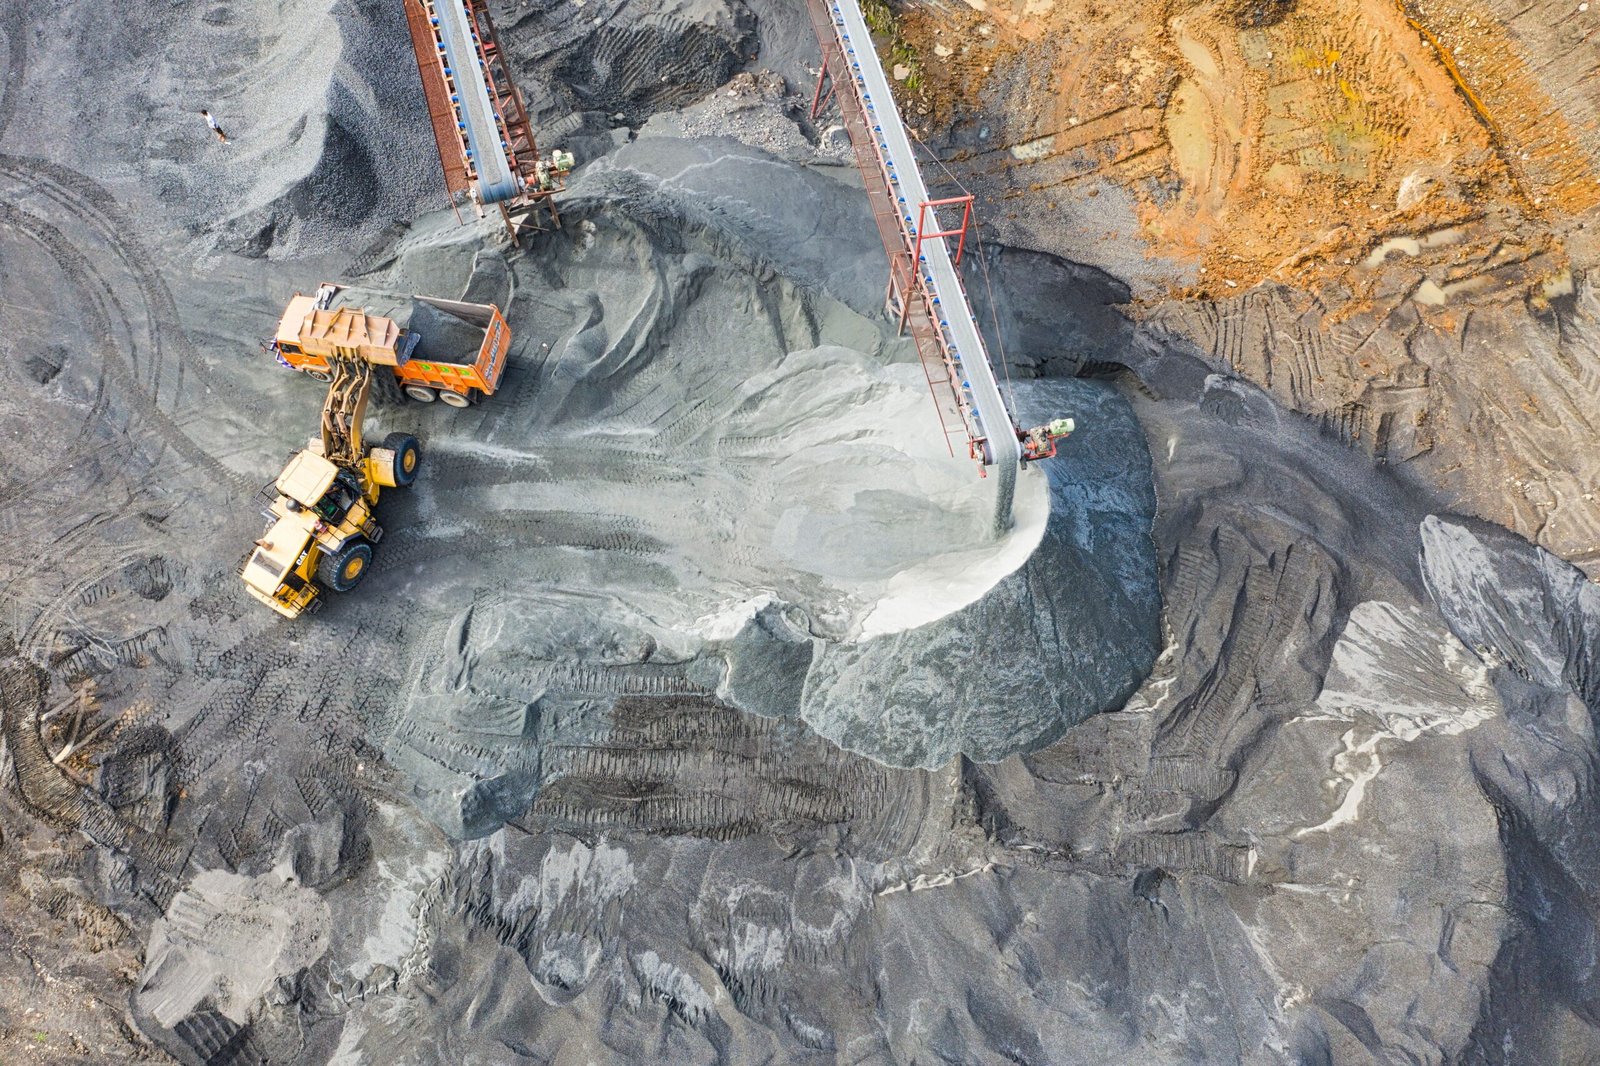
Australia’s transition away from fossil fuels faces a new test after New South Wales approved the continuation of the Hunter Valley Operations (HVO) coal mine until 2045.
The NSW Independent Planning Commission (IPC) on September 30 approved the continuation of HVO North until the end of 2045 and HVO South until the end of 2042. The project would allow an estimated 429 million tonnes of coal to be extracted from the Hunter Valley near Singleton.
The decision is significant not only because of the scale of the mine, but because it extends a major coal operation into the period in which Australia is committed to sharply reducing its greenhouse-gas emissions.
Australia’s current climate commitments include cutting national emissions by 43 per cent from 2005 levels by 2030 and by 62–70 per cent by 2035, with net-zero emissions targeted for 2050.
The latest government inventory estimates Australia’s emissions at 452.4 million tonnes of carbon dioxide equivalent in the year to June 2026, a preliminary 1.8 per cent decline from the previous year. Emissions in the year to March 2026 were 25 per cent below 2005 levels.
Against that backdrop, the IPC acknowledged that the HVO project would have a substantial climate footprint. Its statement of reasons estimates that the project could result in about 809 million tonnes of greenhouse-gas emissions from local mining operations and the eventual combustion of exported coal overseas. The commission said those emissions would contribute to climate impacts in the Hunter, NSW and globally.
The 809-million-tonne figure needs an important qualification to note. it is a lifecycle-related estimate that includes overseas combustion emissions and should not be interpreted as emissions produced directly by the mine.
Coal mine.Representational image.Image credit:Pexels
The economic case for the extension is substantial. HVO employs more than 1,500 people and engages more than 800 suppliers, according to evidence presented to the IPC. The NSW Government says the continuation could secure up to 1,500 ongoing jobs and create about 600 temporary positions through infrastructure upgrades, subject to federal approval.
The approval also comes with conditions intended to address the mine’s emissions and its eventual transition. HVO must prepare a Scope 3 Management Plan dealing with emissions associated with exported coal, maximise renewable electricity use at the mine and purchase additional carbon offsets. It must also prepare a comprehensive closure plan within 12 months, in consultation with local councils and communities, outlining how the mine will transition towards closure while supporting workers and the local economy.
The NSW Government argues that the decision can support regional employment while maintaining the state’s broader emissions-reduction pathway. It says the approved proposal has 43 per cent lower Scope 1 emissions than the company’s 2022 application. NSW’s 2026–50 coal policy also allows extensions of existing mines while ruling out applications for new greenfield coal mines.
At the national level, the federal Safeguard Mechanism is intended to reduce emissions from Australia’s largest industrial facilities. The government says the mechanism is designed to put covered facilities on a trajectory consistent with the country’s 2030 target and net-zero goal.
That creates the central question around HVO’s extension. How does Australia manages the economic and employment role of existing coal regions while reducing emissions over the same period.
The NSW approval does not settle that question. The project still requires approval from the Australian Government under the Environment Protection and Biodiversity Conservation Act.
For the Hunter Valley, the decision provides a longer operating horizon for an established coal industry. For Australia’s climate transition, it brings the challenge of managing an economy in which existing fossil-fuel assets continue operating while national policy seeks progressively sustainable energy and lower emissions.


How Scientists Traced the Flow of Matter Around a Dead Star Using X-rays

India Scores Just 2 Out of 32 for Integrating Health into Climate Commitments

Global Job Market Faces a Growing Inclusion Gap as AI and Digitalisation Reshape Work

FSSAI Moves to Restrict Added Sugars in Infant Foods, Citing Need for Stronger Nutritional Safeguards

NMC Directs Medical Colleges to Set Up Patient Safety Committees

From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story

Knowing When to Think for Ourselves: AI, Intuition and the Education of Discernment

After a Scorching Summer, Delhi’s Children Are Slow to Return Outdoors

Two Chemists Win Nobel Prize for Solving a Century-Old Puzzle: Why Life Picks One Hand Over the Other

Marshall Islands: Why the US Nuclear Legacy Is Back Before the UN
-

 Math3 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
EP Deep Dive: Data & Solutions3 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
EP Deep Dive: Data & Solutions4 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics5 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Interviews4 weeks ago
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
-
Climate5 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society3 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society4 months ago
From Bell Labs to the Classroom: A Second Career in Teaching