Interviews
From Scams to Screens: How the National Stock Exchange Rewrote India’s Equity Story
As the NSE gets listed, veteran capital markets expert Uday Tardalkar reflects on the exchange’s transformation of India’s capital markets, technology, investor participation and financial inclusion.

Interviews
From a 12-Year-Old’s Robot to AI for India: Raul Aju John’s Journey
As India pushes to become a global AI leader through initiatives such as the IndiaAI Mission, the focus is shifting from adopting artificial intelligence to building sovereign AI: systems and models designed for India’s languages, laws, and societal needs. One of the young minds shaping this vision is Raul Aju John, popularly known as the “AI Kid of India,” whose work focuses on building AI solutions for real-world problems.

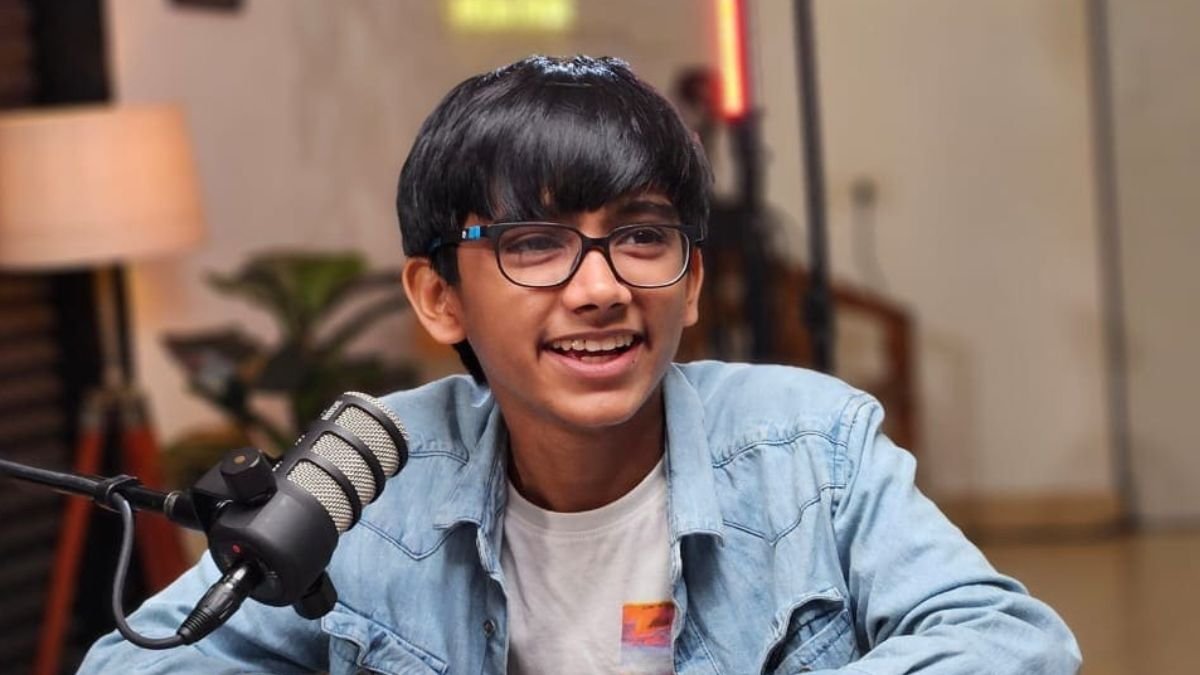
A student, entrepreneur, educator, TEDx speaker, and founder of AIRealm Technologies, Raul Aju John began his AI journey at the age of 12 by building Mebot, a robot powered by an AI version of himself. Since then, he has developed AI solutions in education, legal assistance, robotics, and business automation, delivered AI workshops to thousands of students, and represented his work at national technology forums, including the India Today Conclave.
In this interview with EdPublica, Raul reflects on his journey, the promise of sovereign AI, building responsible and sustainable technologies, and why the next generation should focus on solving real problems rather than chasing trends.
Raul, you built your first robot, Mebot, when you were just 12. What made you so interested in robotics and AI at such a young age?
I think it started with curiosity. I was never satisfied with simply using technology — I always wanted to understand how it worked and see whether I could build something of my own.
Before Mebot became a robot, I had created a software version of myself using my information, voice, and the way I responded to questions. The idea was that it could speak and explain things in a way that sounded like me. I then wondered: instead of keeping this AI inside a computer, what would happen if I gave it a physical body?
That is how Mebot was created. I used an NVIDIA Jetson Nano and placed the software inside a robot body, allowing people to interact with my AI clone physically instead of only through a screen. It was not an extremely complicated idea, but it changed the way I looked at technology. It showed me that software and hardware could be combined to create something people could actually interact with. That experience encouraged me to continue experimenting with AI, robotics, and automation.
Looking back on your journey so far, what has been the biggest challenge you’ve faced, and how did you navigate it?
The biggest challenge has been balancing everything. I am still a student, but at the same time, I run a company, work with a team, develop AI products, create content, teach people, and speak at different events. Every one of these responsibilities needs time and attention, and there are days when managing all of them becomes difficult.
Another major challenge has been getting people to take me seriously because of my age. In some meetings or events, people initially see me only as a school student. I realised quite early that arguing with them or repeatedly explaining what I had achieved would not change their perception. The only thing that could change it was the quality of my work.
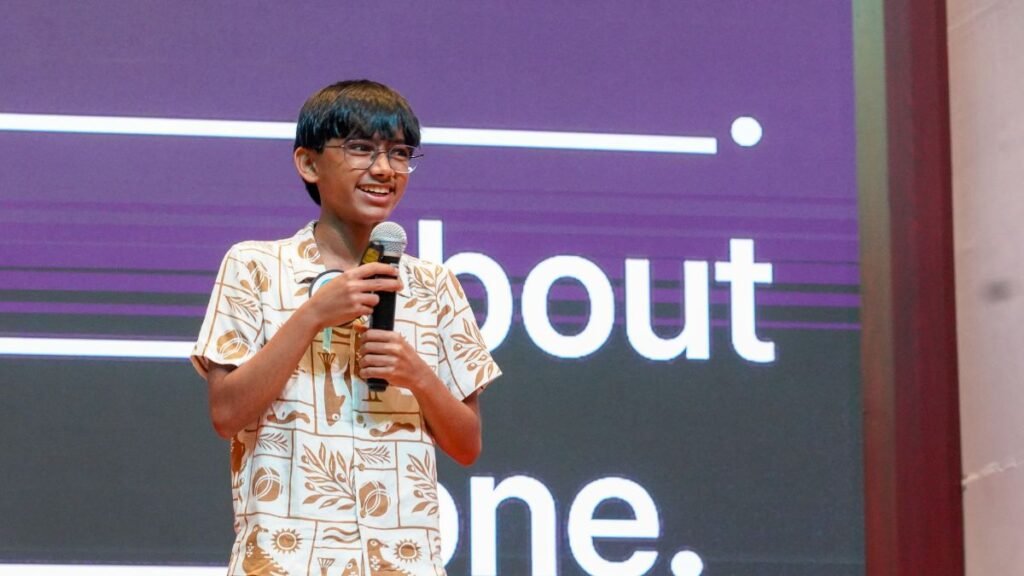
So instead of trying to prove myself through words, I focused on consistently building products, improving my knowledge, teaching people, and delivering results. Public platforms such as the India Today Conclave and technology summits gave me opportunities to demonstrate my work, but the real credibility came from continuing to build even when nobody was watching.
There have also been failed projects, technical issues, rejected ideas, and plans that did not work. I have learned not to treat those situations as the end of a project. I analyse what went wrong, take the feedback seriously, improve the idea, and move forward. In technology, failure is usually not a final result — it is information that helps you build the next version better.
Among the AI projects you’ve built in education, legal assistance, robotics, and business, which one means the most to you, and why?
Although Mebot is the project that began my journey, the project I am most proud of right now is ThinkCraft, our AI education platform.
Through my sessions, content, and interactions with students, I have met many young people who are genuinely interested in AI but have no idea where to start. A lot of existing AI education is either too technical, too expensive, or focused only on theory. Students may watch many tutorials but still not know how to build something useful.
ThinkCraft was created to change that. The goal is to make AI education practical, engaging, and accessible — even for someone who has never written a line of code. I want students to learn by building real projects, experimenting with tools, and understanding how AI can solve problems around them rather than simply memorising definitions.
I am also deeply proud of projects such as NyayaSathi and our legal-assistance systems. Legal information is often complicated, and ordinary people may not know what steps to take during an emergency or legal problem. These projects aim to make that information easier to understand while supporting — not replacing — lawyers and other professionals.
What makes these projects special to me is that they are not being built merely to demonstrate that we can use AI. They are being built because there is a real problem, and AI can help solve a part of it. That is the kind of technology I want to continue creating.
AI is growing very fast, but it also uses a lot of energy and resources. Do you think AI can grow without harming the environment? What should companies do to make AI more sustainable?
I believe AI can continue growing, but sustainability cannot be treated as something companies think about only after building the technology. It has to be considered from the beginning.
One of the biggest mistakes in AI today is assuming that every problem requires the largest and most powerful model. A simple task does not always need a massive system running in a data centre. Companies should choose models according to the problem — using smaller, specialised, and more efficient models whenever possible.
They should also optimise models properly, reduce unnecessary computing, improve the efficiency of their hardware, and avoid repeatedly processing information that could be cached or handled locally. For some applications, smaller AI models can run directly on phones, computers, robots, or other devices instead of sending every request to a large cloud system.
Data centres should increasingly use cleaner sources of energy, improve cooling systems, reuse waste heat where possible, and carefully manage water consumption. Companies should also be transparent about the energy, water, and computing resources required to train and operate their AI systems.
I do not think the solution is to stop developing AI. The solution is to stop using unlimited computing as the answer to every problem. The future of AI should not only be more powerful — it should also be smaller, faster, more efficient, and more responsible.
What are your goals for the future? Is there a problem you dream of solving with AI, and what advice would you give to other young people who want to start building with AI?
My goal is to continue building AI products that solve practical problems, particularly in education, legal awareness, accessibility, public services, and business.
One problem I care deeply about is the widening gap between people who benefit from technology and those who are left behind. AI is developing incredibly quickly, but millions of people still lack access to quality education, understandable legal information, useful digital tools, and technology in the languages they are most comfortable using.
“I want to help build AI from India that works for Indian realities.”
Our languages, communities, schools, businesses, and public systems — while still creating products that can have a global impact. My aim is not to build another general chatbot simply because chatbots are popular. I want to build focused systems that solve specific and meaningful problems. This practical, problem-first approach has also shaped the tools we are developing through AIRealm Technologies.
My advice to other young people is to start before they feel completely ready. You do not need expensive equipment, a huge team, or perfect technical knowledge. Choose a small problem that genuinely interests you and create the simplest possible solution. Show it to people, listen to what they say, improve it, and repeat the process.
“In technology, failure is usually not a final result — it is information that helps you build the next version better.”
Do not spend years watching tutorials while waiting to learn everything. Tutorials can teach you how individual tools work, but building projects teaches you how to think, make decisions, deal with failure, and solve real problems.
Most importantly, do not build something only because it is trending. Start with the problem, not the technology. Your first project probably will not be perfect, and it does not have to be. Mebot was not the final destination for me — it was simply the project that made me realise what else might be possible.
Women In Science
Rewriting cancer: Ankita Bansal’s quest to decode tumour metabolism
From aging research to precision cancer therapeutics, Ankita Bansal’s work sits at the intersection of metabolism, technology, and patient-centred science—seeking to transform how cancer is detected and treated in India
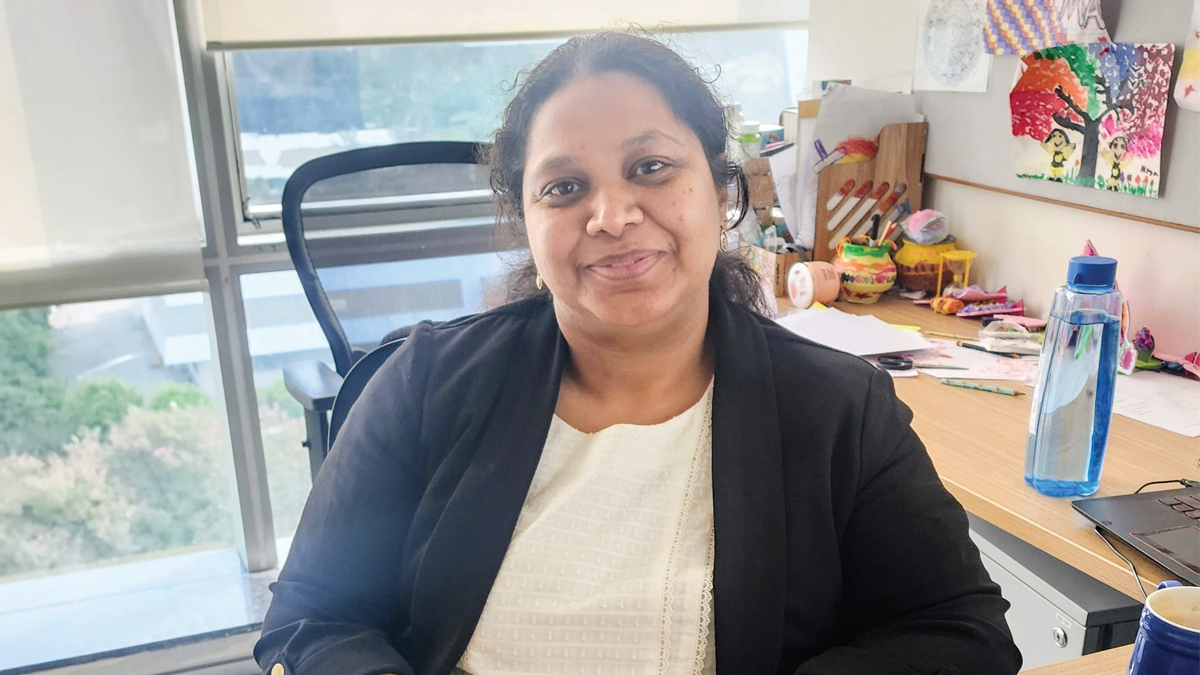
Scientist Ankita Bansal is investigating cancer metabolism to uncover new pathways for precision cancer therapies and early detection. Her research aims to make cancer treatment more personalised, accessible, and effective for Indian patients.
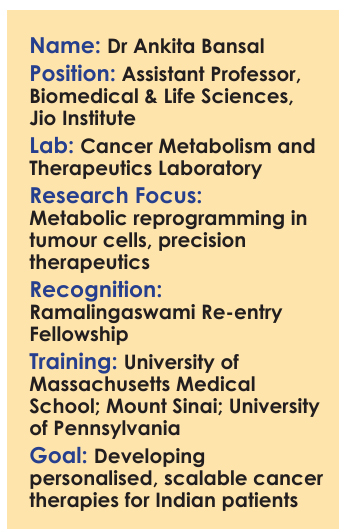
In the evolving landscape of cancer research, where breakthroughs increasingly depend on understanding the invisible workings of cells, metabolism is emerging as one of the most powerful frontiers. At the centre of this shift is Dr Ankita Bansal—scientist, educator, and one of the new voices shaping India’s precision medicine ecosystem. As part of Education Publica’s ‘Women in Science’ series, Bansal represents a generation of researchers redefining not just what science discovers, but how it translates into real-world impact. An Assistant Professor at Jio Institute, Mumbai and recipient of the prestigious Ramalingaswami Re-entry Fellowship, her work focuses on decoding how cancer cells reprogram their metabolism—and how these hidden dependencies can be turned into targeted, patient-specific therapies. Trained across leading global institutions, Bansal’s scientific journey spans aging biology to cancer metabolism, united by a single question: how do we move from understanding disease to meaningfully improving lives? Her research now centres on identifying metabolic signatures unique to Indian patients, with the aim of building scalable, accessible precision therapeutics. At a time when India is positioning itself as a hub for translational science, Bansal’s work sits at a critical intersection—where biology meets technology, and where discovery is measured not just in publications, but in its potential to reach patients.
From Cells to Systems: Rethinking Cancer with Ankita Bansal
Ankita Bansal is exploring how cancer cells rewire their metabolism – unlocking new pathways for precision therapies tailored to Indian patients
What first sparked your curiosity about biology – and was there a moment when you knew research was the path you wanted to take?
It started with simple observations and asking “why?” Over time, that curiosity deepened into a desire to understand why living systems behave the way they do. I began tinkering with home experiments to tease things apart, though I never actually set out to become a researcher. I simply followed my instinct to test ideas and see what happens when you change a variable. It was only much later that I realized what I had been doing all along had a formal name: research.
During your PhD, your work showed that living longer and living healthier are not necessarily driven by the same genes. How did that discovery change the way you think about aging – and about what science should aim for?
Longevity without quality of life is not worth aspiring to. Healthspan is about independence, resilience, and the ability to engage with the world—it isn’t just a fixed number of years on a chart. This philosophy carries directly into my cancer work, where improving how people live, staying in remission, and catching cancer early matters as much as extending survival.
Science operates the same way. It is not just about metrics—publications, h-index, or grants—but the broader ecosystem: the people, the communities it touches, and how it shapes society.
Decoding Cancer Metabolism for Better Care
You’ve worked across systems from C. elegans to cancer cells. How has this shaped you as a scientist?
Training in C. elegans grounded me in systems biology and metabolism, constantly reminding me that disease is rarely a single-gene or single-pathway problem. Moving into cancer research reinforced the complexity of biological networks and the importance of thinking at the level of the whole organism. This journey shaped me into a scientist who views disease as a dynamic interaction between metabolism, environment, and time, rather than an isolated molecular event.
What fascinates you most about targeting cancer through its metabolism rather than more traditional approaches?
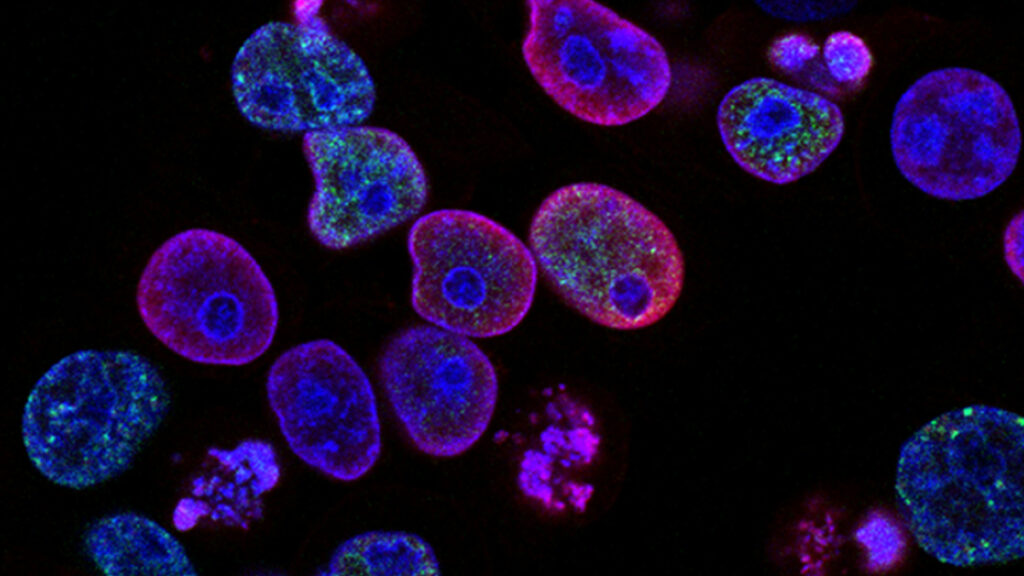
Cancer cells are highly adaptable, yet they remain dependent on specific metabolic sources. That paradox is what fascinates me; that dependency is a vulnerability we can exploit. Metabolism fuels growth. A cancer cell can carry every genetic mutation imaginable, but without access to specific metabolic building blocks, it cannot sustain itself.
It also opens questions beyond treatment: Why do some cancers stay in remission while others metastasize? What metabolic signatures appear early enough to catch a tumor before it becomes a clinical problem? Understanding these dependencies allows us to build early detection approaches that are scalable and accessible to broader populations.
Are there experiences from your global training that influence how you mentor students or run your lab?
If you cannot explain your science to a ten-year-old or a ninety-year-old grandmother, the project might not be good enough. In my lab, I want to train scientists who communicate well, take ownership, and think like mavericks—be the goat, not the sheep.
It is okay to fail, provided you learn during the process. I want people who question assumptions and feel safe doing so. This culture can be difficult to implement in India, where deference runs deep in academic structures, but that makes it all the more important to try.
Why is the gap between academic discovery and patient-ready products still so wide – and what needs to change?
The biggest misconception is that academia and patient-ready products exist in separate silos. They don’t; they exist on a continuum. While this is a global problem, it is particularly acute in India. Academia rewards novelty, while translation requires scalability and collaboration. You cannot simply license a ready technology and call it translation; you have to be part of the process from day one. Academia must take real ownership in nation-building, with the patient’s needs as the starting point, not an afterthought. Scientists, clinicians, industry, and policymakers need to be in the room together far earlier than they currently are.
Building a research lab from the ground up is no small task. As a woman leading a lab, what challenges have surprised you the most?
The juggling act that no one adequately prepares you for: running a competitive research program while raising a family. In India, the lack of high-quality childcare and reliable after-school programs is a significant challenge. It is a major hurdle that directly affects productivity and well-being. Being open about these realities matters, because pretending they don’t exist helps no one.
Gender disparities in science are still very visible in India. Where do you see genuine opportunities for change?
Every day is better than the last. Things are genuinely improving, and I don’t want to paint a picture darker than reality. The most persistent barriers remain inadequate childcare infrastructure and the “two-body problem.” Beyond that, there are no impossible bottlenecks. The trajectory is positive. The key is to keep making the case that these structural issues are solvable through dialogue and goodwill.
How can Indian institutions better support women in science?
We need childcare infrastructure, flexible timelines, and open communication channels. These should be framed not as “accommodations,” but as essential investments in retaining top-tier talent.
Did role models play a part in your journey?
My grandmother pursued a double MA after marriage and showed me that learning has no expiration date. My mother embodied the resilience required of a working woman, and my father taught me that success comes through sacrifice. My PhD mentor ignited my passion for research, even while facing her own health challenges, shaping my approach to science with both rigor and empathy. I also value the scientific dialogue I share with my husband, a scientist-entrepreneur whose translational outlook broadens my perspective.
Visibility matters. When women scientists share not only their achievements but also their doubts and unconventional paths, the journey becomes more accessible. There is no single template for success.
What excites you most about building a precision therapeutics lab in India right now?
Our time has begun. India is at a unique point in its trajectory—our Amrit Kaal. We have growing technological capacity, vast patient populations, and massive unmet clinical needs. Out-of-the-box thinking is now highly sought after. Translating discoveries into affordable, scalable solutions that directly impact patients is what motivates me every morning.
Looking ahead a decade, what legacy do you hope your work leaves behind?
I hope to leave behind frameworks that integrate metabolism, technology, and clinical insight to revolutionize early cancer detection. More importantly, I hope to foster a culture where science is patient-centered first—where we start with the patient’s needs, not the publication, and build everything outward from there.
Interviews
India Industrial Growth Is Reshaping Global Economics
India’s greatest advantage is its youth—ambitious, skilled, and ready to compete globally. With the right discipline and leadership, this demographic strength can redefine the country’s future
India industrial growth is entering a defining phase as manufacturing, infrastructure, technology and demographic advantages converge to reposition the country at the centre of global economic expansion.
From late industrialisation to emerging global leadership, India’s growth story is increasingly shaped by its ability to integrate capital, technology, and youthful ambition with a long-term national vision, says management education expert Bharat Nadkarni in a conversation with Education Publica magazine.
A Mumbai-based expert with decades of experience across multinational corporations, including the Tata Group, Nadkarni has worked extensively in leadership development, corporate strategy, and global business transformation. He continues to engage with industry and academia on India’s evolving role in the global economy, as well as emerging trends in management education.
Why India Industrial Growth Matters Now
Industrialisation began in developed countries nearly 200 years ago. India, by comparison, is a late entrant. Our industrial journey only truly gathered momentum in the last 25 to 40 years, with a more decisive acceleration in the 21st century. Today, however, India is not just catching up—it is beginning to move faster.
This late start has shaped our needs. To grow, India requires capital, advanced skills, and cutting-edge technology—resources that largely reside in developed economies. At the same time, India offers what many of these countries increasingly lack: land, labour, raw materials, and a vast untapped market.
This complementary equation presents a powerful opportunity.
How India Industrial Growth Is Reshaping Manufacturing
India’s proposition to the world is simple yet compelling. Global organisations with access to capital, technology, and expertise should bring these into India through foreign direct investment. In return, India provides the scale, workforce, and market access necessary for growth.
Consider the example of Germany. It may not have the land, labour, or raw material resources at scale, but it possesses strong technological capabilities and capital strength. India, on the other hand, offers the physical and demographic advantages. Together, this creates a natural partnership model—one that can drive mutual growth.
This is precisely why global corporations increasingly view India not only as a major market but also as a manufacturing hub.
From China to India: A Shift in Focus
In the 1990s and early 2000s, global attention was firmly on China. However, China’s economic model, shaped by its political system, has certain limitations in terms of openness and flexibility.
India, as a vibrant and evolving democracy, offers a different value proposition. It is open, dynamic, and increasingly business-friendly. There is a growing belief that India can contribute more to the global economy in the coming decades than China, provided it addresses its internal challenges.
The potential is undeniable. What is needed is greater discipline and execution.
The Power of India’s Youth
One of India’s greatest strengths lies in its young population. Today’s Indian youth are talented, ambitious, and globally aware. They aspire to build meaningful careers and compete on the world stage.
This demographic advantage positions India uniquely. While many Western nations face ageing populations, India is becoming a young, energetic economy ready to take on the future.
The Missing Link: Political Maturity
While corporate India has demonstrated remarkable progress, political maturity remains a critical factor in determining the pace of national development.
India needs leadership that is not just focused on the present, but deeply invested in the future. Visionary politics—driven by long-term thinking and strategic clarity—can significantly accelerate economic growth.
Encouragingly, there are emerging leaders who embody this vision. If nurtured, they can help bridge the gap between political intent and economic execution.
Corporate India Goes Global
Indian companies are no longer confined to domestic markets. There is a clear shift towards global ambition.
The Tata Group offers a compelling example. Tata Steel’s acquisition of Corus positioned it among the world’s leading steel producers. Tata Motors’ acquisition of Jaguar Land Rover demonstrated India’s ability to own and grow global brands. Tata Consultancy Services operates across continents, reinforcing India’s strength in IT services.
This trend extends beyond one group. Larsen & Toubro, Gammon India, and several others are expanding internationally. In the FMCG sector, companies like Hindustan Unilever, Godrej, Marico, ITC, and Dabur are strengthening their presence, while global players such as Nestlé and Procter & Gamble continue to invest in India.
Indian enterprise is no longer inward-looking—it is global in aspiration and execution.
The Global Fulcrum is Shifting
Over the next 50 years, the balance of economic power is likely to shift from the West to Asia.
There was a time when global conversations revolved around cities like New York, London, and Paris. Today, the narrative is changing. Cities like Singapore, Dubai, and Mumbai are becoming central to global business and economic activity.
The energy, the momentum, and the opportunity are increasingly concentrated here.
A Young Nation Ready to Lead
Much of the Western world is transitioning into an ageing phase, while India is entering its prime. It is a young country, full of possibility, ready to move forward.
The real action is no longer confined to traditional power centres. It is unfolding in emerging economies, and India is at the heart of this transformation.
The path ahead is clear. With the right mix of global collaboration, internal discipline, and visionary leadership, India has the potential not just to participate in the global economy—but to lead it.
-

 Math2 months ago
The 2026 Fields Medals: Four Proofs, Four Decades-Old Problems Solved
-
Climate2 months ago
After Kerala’s Deadliest Landslide, the Hardest Thing to Rebuild Was Childhood
-
Society3 months ago
West Asia Crisis: Can Kerala’s Returning Gulf Migrants Find a Future in the Green Economy?
-
Space & Physics4 months ago
India Semiconductor Mission: ‘It’s Not About Fabs. It’s About Building An Entire Ecosystem’
-
Climate4 months ago
The Climate World Cup? How Climate Change Could Affect Player Performance at the 2026 World Cup
-
Society2 months ago
What Is Civilisational Diplomacy? Understanding India’s Newest Foreign Policy Tool
-
Society3 months ago
From Bell Labs to the Classroom: A Second Career in Teaching
-
Space & Physics4 months ago
Engineers Develop Dual-Mode Propulsion System for Next-Generation Small Satellites